Christmas light installation insurance: 3 checks before you hang a single strand.
• The homeowner's policy generally won't cover your crew if someone gets hurt
• Cash jobs still count as payroll at your workers' comp audit
• Make sure light installs fit your GL classification
Hanging lights this season? Send us your policy and we'll take a look.
949.305.5577
#ChristmasLightInstallation #WorkersComp #ContractorInsurance #HolidayLighting #GeneralLiability
Christmas light installation this season? Don't count on the homeowner's insurance to cover your crew.
In California, a homeowner's policy generally won't provide workers' comp for someone who worked less than 52 hours for that homeowner in the last 90 days, no matter what they got paid. A one-day light install doesn't come close.
If it's your crew on the ladder, your workers' comp is the coverage that matters. Two things to check:
• Cash jobs are still payroll. The auditor counts it.
• Your general liability covers the work you told the carrier you do. If holiday light installs aren't part of that, ask before you take the job.
Not sure your policies fit this kind of work? Call before you book the first house.
949.305.5577
#ChristmasLightInstallation #HolidayLightInstallation #WorkersComp #ContractorInsurance #CaliforniaContractors
Curtiss got the roofer's certificate. Laminated, even. 🏠📄
But a certificate alone doesn't make you additional insured. That comes from the endorsement on the sub's policy.
Before your sub's crew is on the roof:
✅ Get the certificate
✅ Ask for the additional insured endorsement
✅ Confirm both with the agent who issued them
Trust is good. Verification is better.
#contractorinsurance #certificateofinsurance #additionalinsured #generalcontractor #constructionbusiness #roofing #subcontractor
You had the payroll records. You didn’t send them on time. Starting January 1, California may not let you use them to defend yourself.
Under SB 1316, if the Labor Commissioner sends a written request for payroll, time or employment records and you miss the deadline, you may be barred from using those records later when you contest a wage or penalty assessment.
It’s written with public works in mind, but a similar rule applies to wage cases outside public works too.
What that means in practice:
A records request is a hard deadline, not paperwork to get to later.
Make sure requests reach the right person the day they arrive.
If you need more time, ask in writing before the deadline. The law gives an automatic 15-day extension for good-faith requests.
Call your labor attorney the moment one shows up.
The insurance side: clean, organized payroll records are also how you win a workers’ comp audit. Contractors who keep good records can defend themselves in both places.
Want a second set of eyes on your payroll before your next audit? Send it over.
A contractor needs a COI. The board calls an emergency meeting. 🏛️
Episode 1 of Paperwork & Casualty. New episodes every Thursday.
Fictional satire. Not a real insurer.
#contractors#construction#insurance#COI
Planning a holiday party for your crew? Read this before you book the venue.
In California, contractor GL policies generally exclude liquor liability, even at your own party. If someone drinks at your event and hurts someone, don’t count on your general liability policy to respond.
And under California case law, if an employee drinks at your party and causes a crash on the way home, your company can be on the hook.
Before the party:
Check your policy for a liquor exclusion. Most contractors assume they’re covered.
Ask the venue what coverage they require. Many require a one-day event policy with liquor liability.
Make attendance truly optional. If employees are expected to be there, an injury at the party can become a workers’ comp claim.
Plan the ride home: drink tickets, a set end time, paid rides.
Want to know what your policy actually excludes? Send it over and I’ll show you.
949.305.5577
“Can you just cover my deductible?” It sounds like good customer service. In California, it can be a crime.
Under Penal Code §551, a contractor can’t knowingly offer or give a discount meant to offset a customer’s insurance deductible on repairs to a home or commercial building.
That nice-guy move can cost you a lot more than the deductible.
How to handle it:
Tell the customer upfront that the deductible is theirs to pay.
Put the deductible in the contract.
Collect it at signing or with the first draw, not at the end.
If they push, point to the law. You’re not being difficult.
Doing insurance work and want to make sure your contract handles it right? Talk to your attorney, then let’s look at your coverage.
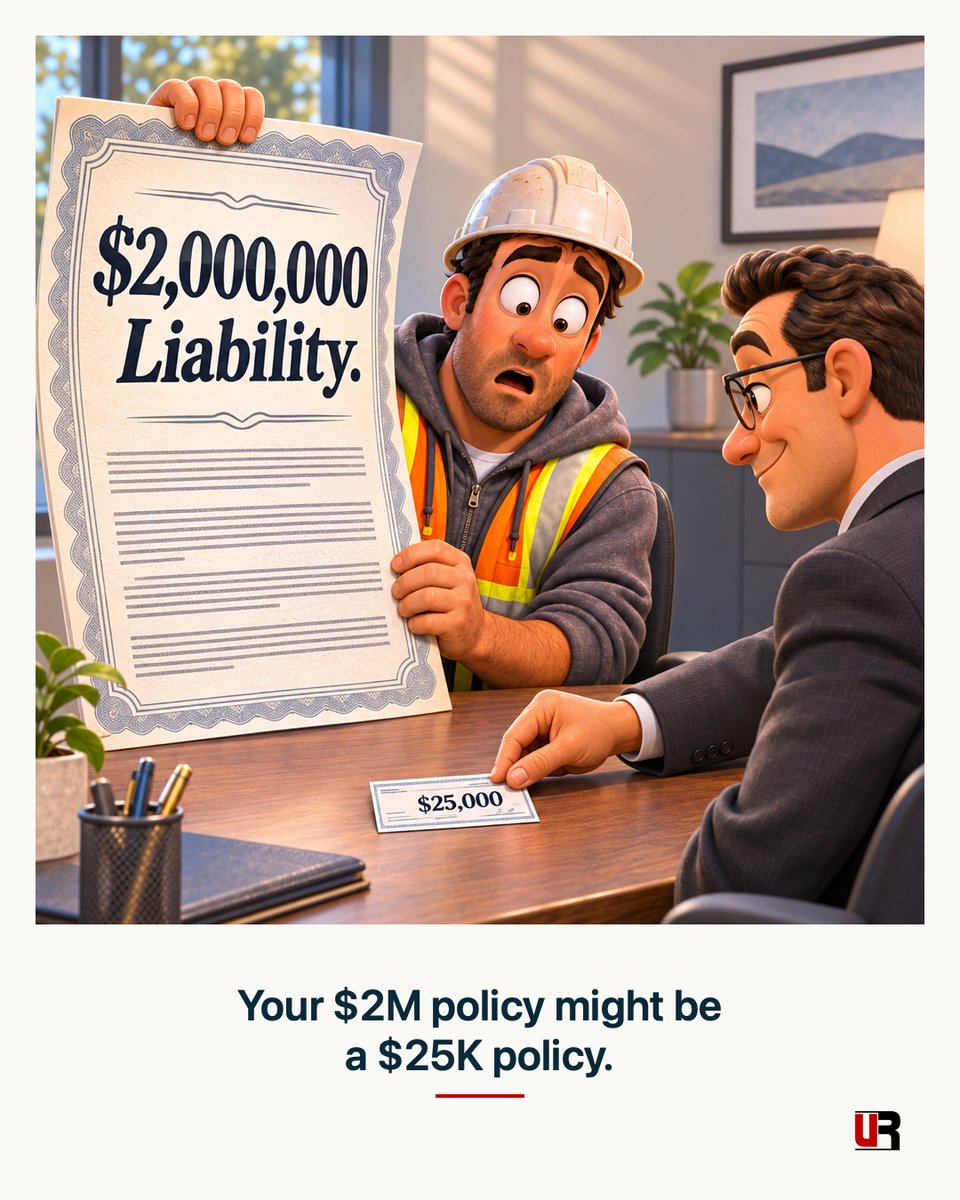
Your $2M liability policy might really be a $25K policy, and you won’t find out until there’s a claim.
A contractor posted about this online: deck claim, $2M GL policy, and the carrier offered $25K. Why? A sublimit, plus the work had been subcontracted.
Some GL policies put conditions on using subs. Miss one, and coverage for that work can shrink or disappear.
What to check before your next sub starts:
Your policy’s sub conditions. Some require subs to carry their own GL at set limits, name you as additional insured, and sign a written contract.
The endorsement, not just the certificate. A COI with “AI” checked isn’t the endorsement. Ask for the endorsement itself.
Completed operations. Make sure the additional insured coverage continues after the job ends. Most claims show up after you leave.
Limits. Confirm the sub’s limits meet what your policy requires, not just what the GC asked for.
Timing. Get all of it on file before they start, not after a claim.
Not sure what your policy requires of subs? Send it over and I’ll show you where the conditions are.
949.305.5577
Saturday’s targeted Southern California Red Flag Warning is a reason to reassess spark-producing work near dry brush.
Before the crew starts: check the jobsite forecast and local restrictions, review the work area, and decide whether that task needs to move.
A full schedule shouldn’t make the safety decision for you.
Contractors: what’s the weirdest insurance requirement you’ve seen in a contract?
A $5M umbrella for a $20K remodel? Twelve additional insureds on one certificate? An endorsement your carrier won’t issue?
Drop it in the comments. 👇
#Contractors#ContractorLife #ConstructionBusiness #ContractorInsurance #GeneralContractor
Policy renewing January 1? The application is going out soon, if it hasn’t already.
Yesterday’s Short showed what happens when an application doesn’t match the business. Get these together now so your renewal reflects the work you actually do:
✅ Payroll by class code (actuals, not estimates)
✅ Gross receipts, current and projected
✅ Largest jobs, completed and contracted
✅ Sub list with current COIs
✅ Loss runs
✅ Any new trades or scope changes
#ContractorInsurance #InsuranceRenewal #WorkersComp #CaliforniaContractor #ConstructionBusiness
Your GL policy is written around the work you told the insurance company you do.
Many contractor policies include an endorsement that limits coverage to the classifications or operations listed. Take on work outside that description, and a claim on that job could be denied.
Where it shows up:
A framer picks up a roofing job
A painter starts doing stucco
A remodeler adds a second story
Before you take on work outside your normal scope, have your agent check your classifications and endorsements.
#ContractorInsurance #GeneralLiability #CaliforniaContractor #ConstructionBusiness #RiskManagement