@mark_collins09@dig_with_kyle Super helpful.
What needs to happen for things to turn? With oil prices falling (basically pre-conflict levels) and constant uncertainty from Ottawa, the set up looks strong for CY2027.
What do you think happens in the NTM? Any leading indicators?
$BRZE
Clean print all around
3rd straight quarter of subscription revenue accel'ing
DBNR stepped up 300 bps this quarter
Customers >$500k up 35% Y/Y
$100mm repurchase autho.
Even at $21, this trades at ~2x NTM sales
@Rationaldomain1 This stock takes a hit anytime the company talks. Happened at Cowen a few weeks ago and is happening now with Oppenheimer.
Company sounded fine
$EVH
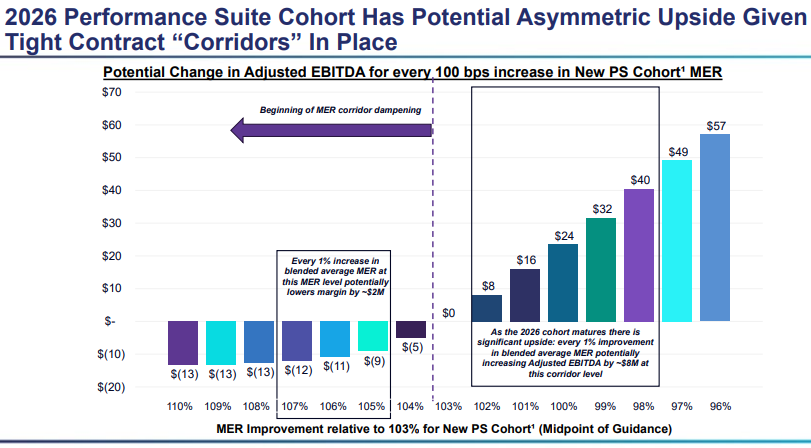
2026 EBITDA guide a touch weaker than I expected but driven by a conservative approach to reserving new contracts + losses of mid-year launches higher due to higher-than-expected membership volumes.
I'm fine with that as long as they continue executing on new PS wins
Add in:
Legacy PS EBITDA growth from core cohort for 2027 (idk, 30-40mm?) + MER improvement from the 2026 cohort (idk, 100%?)
Your 2027 EBITDA quickly bridges to $180mm+ with multiple levers for it to become much higher than that in the years beyond.
$AMN
Looks like Labor Disruption Revenue more positive than I had initially imagined.
Assume 10% EBITDA margin on this $600mm. That's $60mm of accretion on a $600mm market cap business.
Rest of the business looks fine/trending as expected.
Not easy to get a read thru on $AMN data given recent strikes.
We know that based on on-the-ground data, management believes the correction is close to being finished and sees margin expansion in 2026 + MSD growth in 2027.
This is despite weakness shown in the Aya dataset.
So clearly there's noise between what we're seeing and tracking vs. what management is seeing.
Not very clear whether these strikes persisting are a net positive or negative (more revenue but lower margin?)
@Michhhhh43 My guess is it just has a shitty, pod & retail investor base.
It also got cranked prior to last quarter's print on zero news. They then printed a clean Q3 and still continued to draw down.
Can't win.
Ultimately, the deleverage and growth will drag it back up.