@signalnoise8020 They're the same but different. A Canadian interested in personal finance must be 'bilingual' and understand the US instruments to make use of all the articles and resources published. Like 401k, RRSP can be a massive tax planning issue, and TFSA like Roth, a very valuable tool!
I ran my Coast FIRE number and felt relief. Then I changed the assumed return from 7% to 5% and the number I needed nearly doubled.
That is Coast FIRE in one line: a useful idea sitting on an assumption most calculators quietly make for you.
https://t.co/d3b1FaMolQ
@signalnoise8020 Nifty calculator - thanks!
I have to put some thought into inputting CPP & OAS (Canada's version of Social Security) and RRSP meltdown (a bit of flexibility of 401k & IRA withdrawls to optimize lifetime tax a maximize OAS) and our TFSA (a very flexible Roth)
In the unofficial count, separation led in just two Alberta electoral divisions: Central Peace-Notley and Rimbey-Rocky Mountain House-Sundre. The federalist side led everywhere else.
https://t.co/Czbkbiktsm
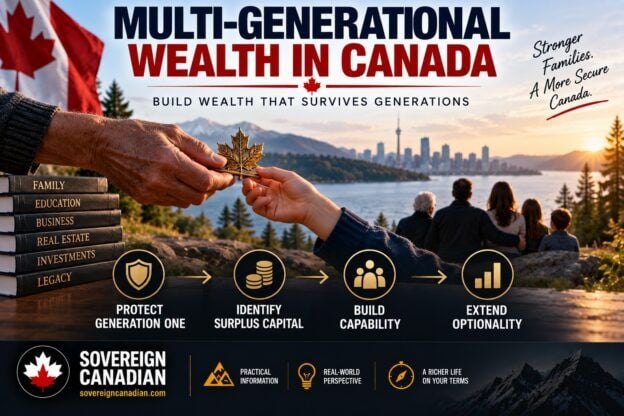
A business worth 5 million CAD with a near zero cost base can still owe something like 655,000 CAD in tax at death, even after two spouses shelter 2.5 million combined through the lifetime capital gains exemption.
https://t.co/1g9EEeaVEm
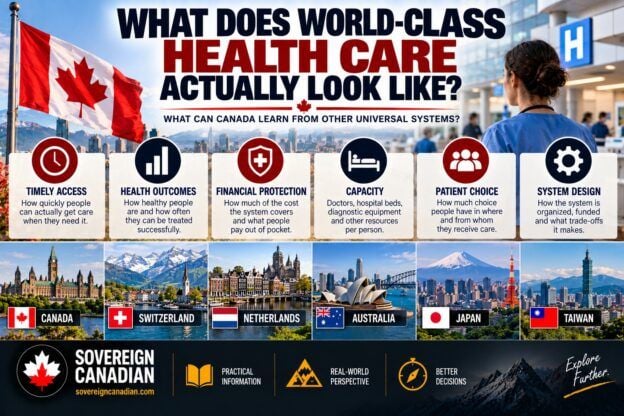
Australia pairs tax-funded Medicare with a large private sector. About 46% of Australians hold private hospital cover.
It ranked 1st overall in 2024, but 9th of 10 on access.
Private involvement is not a cure-all.
Canada has 26 CT, MRI and PET scanners per million people. The OECD average is 51. More machines are not automatically better care, but Canadian scanners run long hours. https://t.co/T6HM8lYogP
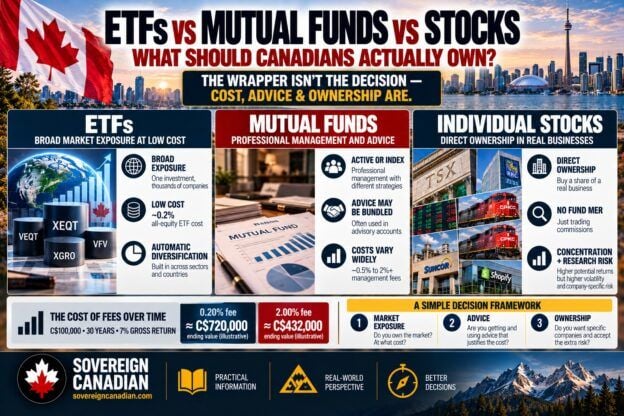
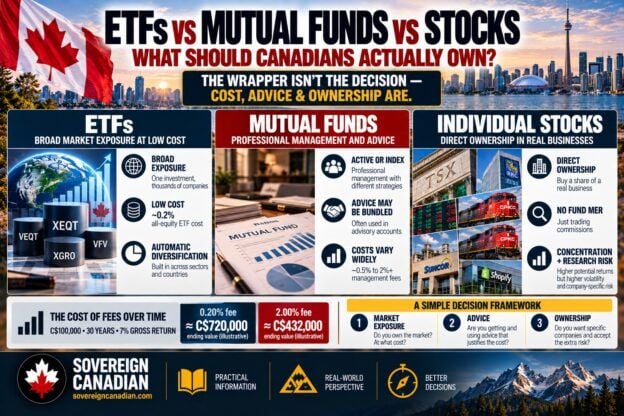
Owning stocks directly gives you more granular tax control: tax lots, loss harvesting, timing of gains. That is not the same as being more tax-efficient than an ETF. https://t.co/llbhmADmQu
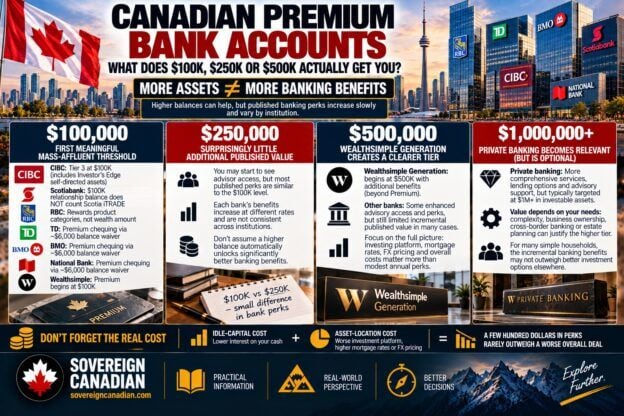
Wealthsimple's line of credit isn't a HELOC. It's secured by investments, capped around 35% of eligible assets, and TFSAs count but RRSPs don't. Falling markets shrink the room. https://t.co/KSHnm5C6jn
The ballot didn’t ask Alberta to leave. Question 10 asked whether to begin the legal process toward a binding separation referendum. A referendum on a referendum, and non-binding at that.
https://t.co/Czbkbiktsm
Same $200K household income.
Family A invests $10K/year → $298K
Family B invests $30K/year → $893K
20 years. Same assumed 4% real return.
Income creates opportunity. What you keep and invest builds wealth.
🇨🇦 New Sovereign Canadian video:
https://t.co/waOIrvYERo
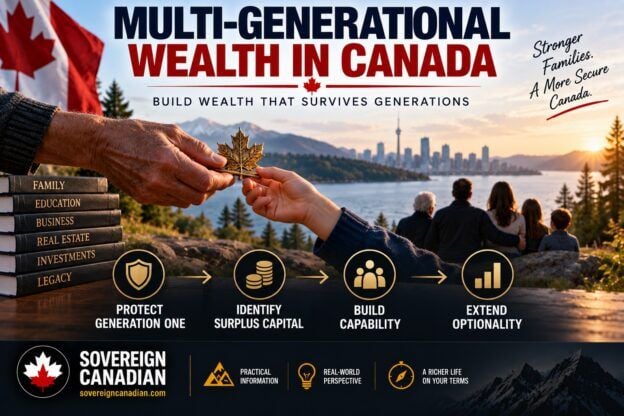
Have one child spend the money instead of investing it and the family that waited ends up ahead, by almost exactly what that money would have grown into. Early transfer only wins when something happens to the dollar after it moves.
https://t.co/1g9EEeaVEm
The Netherlands runs universal coverage on competing private insurers.
It is heavily regulated, mandatory and ranked first on access in the Commonwealth Fund's 2024 comparison.
Universal does not require a government insurance monopoly.
Why wait stats mislead: CIHI starts the clock at ready to treat, AIHW at listing, Fraser at GP referral. Canada: 65% of hip and knee replacements within 182 days (CIHI) vs 28.6 weeks from referral to treatment (Fraser). Different clocks. https://t.co/T6HM8lYogP
Is twenty stocks diversified? Depends on how they move together. Twenty correlated names still carry plenty of single-stock risk. And the TSX is already heavy in financials. https://t.co/llbhmADmQu
Wealthsimple has the clearest published wealth ladder: tiers at $100k and $500k change chequing rates, USD accounts, margin and its line of credit. At Generation, prime minus 0.5%. https://t.co/KSHnm5C6jn
Albertans voted to stay in Canada, and it wasn’t close. Roughly three out of four chose remain in the province’s first-ever referendum touching on separation. The count is unofficial until Oct 29, but the margin isn’t in doubt.
https://t.co/Czbkbiktsm
Same starting capital, same 30 year horizon, two families. If both generations earn an identical after tax return and nothing gets spent, they land in exactly the same place. Timing alone is not the lever people think it is.
https://t.co/1g9EEeaVEm
Canada ranked 7th of 10 overall in the Commonwealth Fund's 2024 comparison.
4th on outcomes. 4th on care process. 7th on access.
The quality of care is not the main problem. Getting in is.
https://t.co/T1bqs7lvdA
The mean Swiss adult premium is about CHF 393 a month in 2026, plus a deductible of CHF 300 to 2,500 and 10% coinsurance. Best life expectancy in the OECD. Not cheap. https://t.co/T6HM8lYogP
Individual stocks can be a fine choice if you want the control, the concentration and the work. In U.S. data, only 42.6% of stocks beat T-bills over their lifetimes, and a small slice created nearly all the wealth. https://t.co/llbhmADmQu