🚨 FOMC Member Update: Waller says March is a coin flip
Source: Governor Christopher J. Waller
Speech on Feb 23, 2026
NABE Economic Policy Conference, Washington, D.C.
Waller called the labor market rebound “signal or noise” after January’s strong jobs print.
Key points:
2025 was one of the weakest job years outside a recession
January payrolls surprised higher, but concentrated in healthcare & construction
PCE inflation ~2.8%, but Waller “looks through” tariff effects
March rate decision = 50/50
If February jobs confirm strength → pause
If January gets revised down → 25bp cut possible
Data-dependent Fed. March is live.
#FOMC #Fed #Rates #Macro
📊 AAII Sentiment turns more cautious
Bullish sentiment falls to 34.5% (38.5% prior), now below its long-term avg of 37.5%.
Bearish remains elevated at 36.9%, still above the historical norm (31%).
Neutrals rise to 28.5%.
Optimism is fading, but there is no panic.
Positioning looks more hesitant than fearful.
Historically, sustained rallies often start when sentiment is decisively negative — not just mildly cautious.
For now, the mood is fragile rather than washed out.
#AAII #Sentiment #Markets #Macro
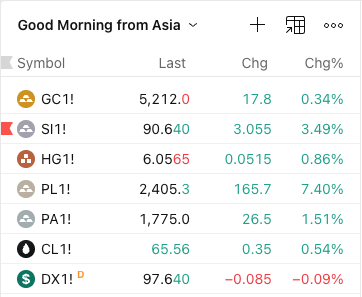
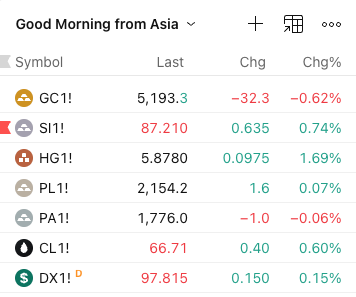
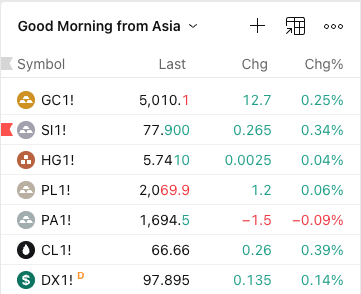
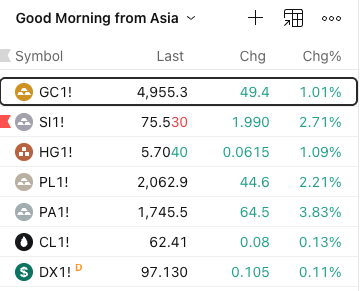
Good Morning from Asia 🌏
Gold holding above $5,000
Silver near $78
WTI back above $66
DXY firm at 97.9
🛢️ Iran tensions intensifying → crude risk premium building
📊 Today: GDP | Core PCE | Income/Spending | Michigan | New Home Sales | Rig Count
Markets face a double trigger:
Macro data volatility + geopolitical tail risk.
Oil sensitive.
Gold supported.
Dollar steady — for now.
This could turn into a high-vol session.
#Macro #Oil #Gold #Energy
Key events next week (Feb 23 – Feb 27)
📌 Macro focus:
China reopens after the Spring Festival — liquidity normalizes.
Fed speakers dominate the calendar, with PPI on Friday as the key inflation read.
Mon
🇨🇳 Spring Festival ends | 🇩🇪 Ifo Business Climate
🇺🇸 Fed Waller | Chicago Fed Activity Index
🇺🇸 Factory Orders | Dallas Fed Mfg
🇪🇺 ECB President Lagarde
Tue
🇺🇸 ADP Employment Change | CB Consumer Confidence
🇺🇸 Case-Shiller Home Prices
🇺🇸 Fed Golsbee, Bostic, Collins, Waller, Cook
Wed
🇦🇺 CPI | 🇩🇪 GfK Confidence | 🇪🇺 CPI
🇺🇸 API & EIA Crude Oil Stocks
🇺🇸 Fed Barkin, Collins, Musalem
Thu
🇺🇸 Initial Jobless Claims (all)
🇺🇸 EIA Natural Gas Stocks
🇺🇸 Fed Bowman
Fri
🇺🇸 PPI MoM | Chicago PMI
🇺🇸 Baker Hughes Rig Count
🟢 Focus:
Fed communication throughout the week.
ADP gives early labor signals Tuesday — PPI likely sets the tone into the weekend.
#Macro #Markets #Fed #PPI
🚨 The Fed path just got messier
US GDP slowed sharply to +1.4% (vs 3.5% expected), partly dragged down by the record Oct–Nov government shutdown.
At the same time, Core PCE came in hot at +0.4% m/m → inflation pressure remains sticky.
FOMC Minutes confirm internal divisions.
Markets have already repriced:
June cut → now July at the earliest
Only max 2 cuts priced for this year.
What does this mean for USD, yields and risk assets?
Full breakdown in the pinned article:
“FED-WATCH WEEKLY UPDATE” 👇
#Fed #Macro #Rates #Markets
🔥 US NatGas tight — but not panicking
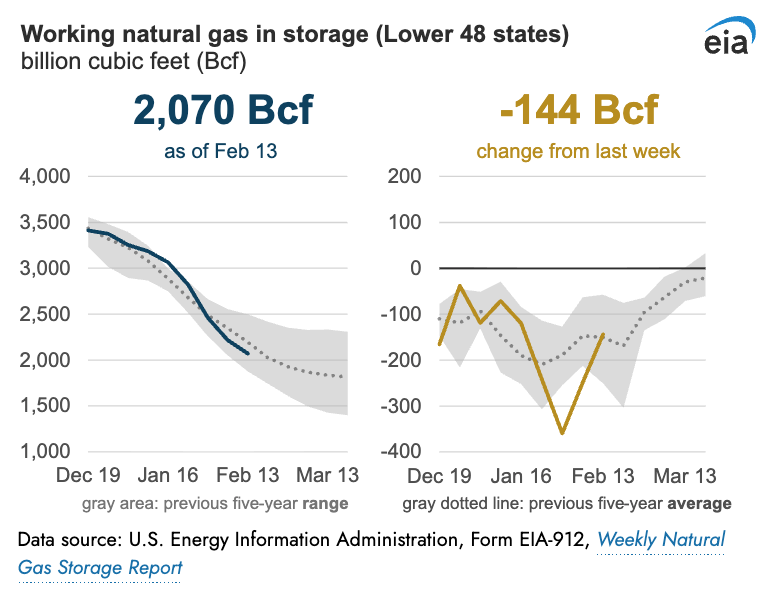
EIA (week ended Feb 13):
• Storage: 2,070 Bcf
• Weekly draw: –144 Bcf
• 6% below 5-yr avg
• 3% below last year
Withdrawals this season running +18% vs 5-yr avg.
Yet Henry Hub trades near $3.00 — 4-month low.
Why?
📈 Production up to 108.7 bcfd
🌡️ Mild weather ahead
🚢 LNG flows strong at 18.6 bcfd
Deficit remains — but supply growth is cushioning it.
Gas isn’t tight.
It’s balanced… for now.
#NaturalGas #HenryHub #Energy #LNG
🚨 WTI inventories shock the market
EIA (week ended Feb 13):
• Crude: –9.0M bbl (vs +1.7M exp.)
• Gasoline: –3.2M bbl
• Distillates: –4.6M bbl
• Total petroleum stocks: –19.1M bbl
Crude inventories now 5% below 5-yr avg.
Refinery runs at 91%.
Imports down.
This wasn’t a headline draw.
It was a broad-based tightening.
With Iran risk premium building, the physical backdrop just turned more supportive.
Is the curve too complacent?
#OOTT #WTI #Oil #Energy
🚨 The Fed didn’t pivot — the market did
FOMC Minutes (Jan 27–28) show a central bank still in wait-and-see mode.
• Inflation above target and potentially sticky
• Labor market stable
• Growth solid
• Some members even see hike risk
The Fed is not preparing to ease.
It is preparing to react.
📉 Markets price cuts
🏦 Fed wants proof
This is a conditional easing regime:
Rates fall only if inflation allows it.
#Fed #FOMC #Macro #Rates
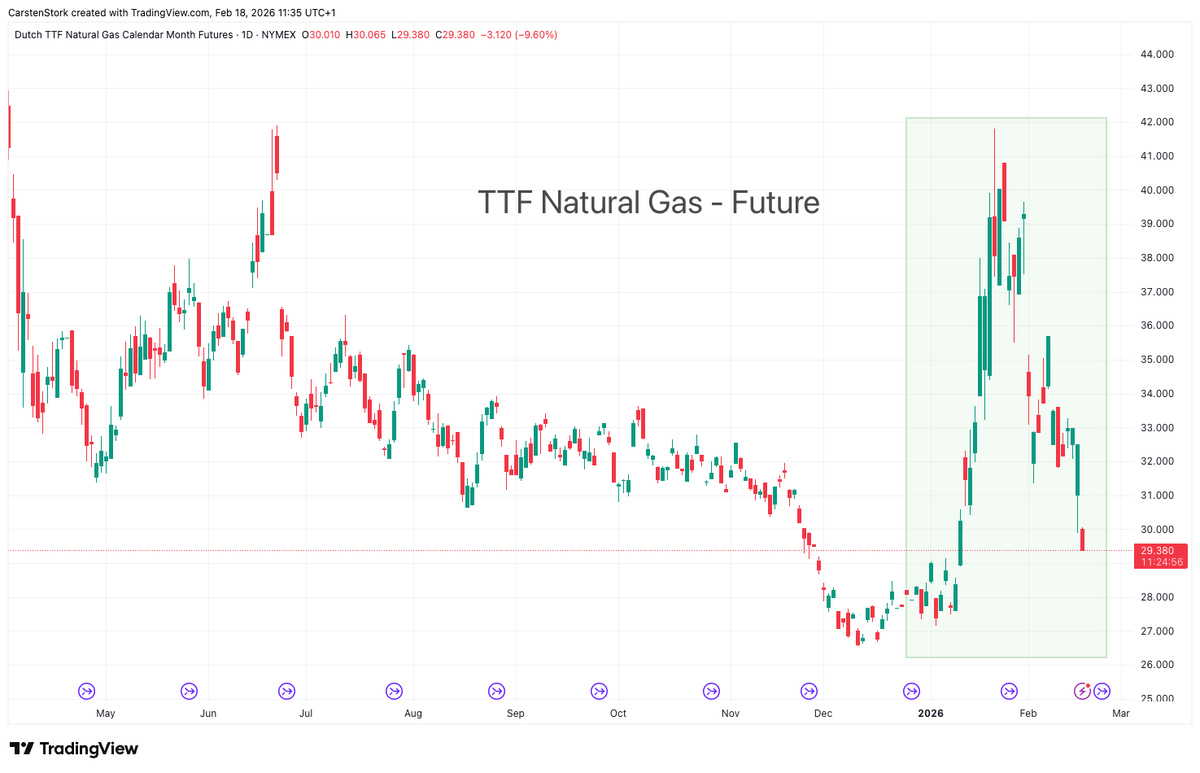
🚨 Europe gas is no longer trading supply — it’s trading fear
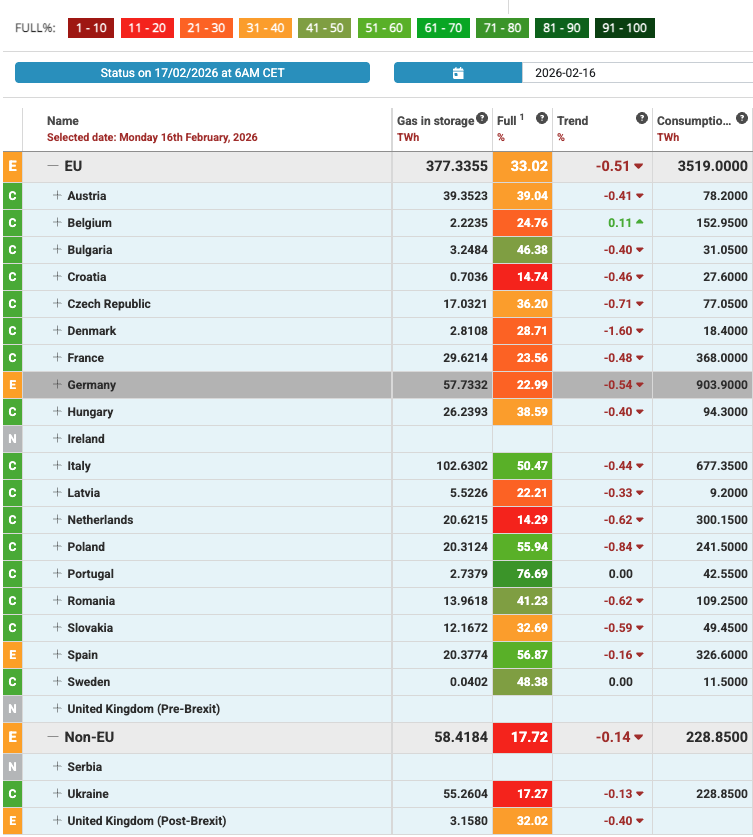
EU storage: 33% full
Low for this time of year.
Normally prices would already grind higher.
Instead, TTF keeps violently swinging between €27 and €40.
Why?
The market shifted from stocks → flows
As long as LNG arrives → calm
Any doubt → panic
Low inventories don’t move price immediately anymore —
they change the reaction function:
• Colder weather → spikes
• LNG disruption → spikes
• Geopolitics → spikes
Not because gas is scarce today —
but because refill risk is rising fast.
This summer Europe may have to bid aggressively for LNG.
Gas isn’t bullish yet.
It’s fragile.
#NaturalGas #TTF #Energy #OOTT
🚨 Fed Barr (Feb 17, New York Association for Business Economics – New York)
Key takeaways:
• Labor market stabilizing but vulnerable to shocks
• Inflation around 3% → risk of remaining above target
• Policy should stay unchanged for some time while assessing data
• Fed needs clear evidence inflation is sustainably falling before cutting
• AI unlikely to be a reason to lower policy rates
Barr also noted AI could:
– raise productivity and long-term equilibrium rates (r*)
– create short-term inflation via energy and investment demand
#Fed #Macro #Rates #Economy
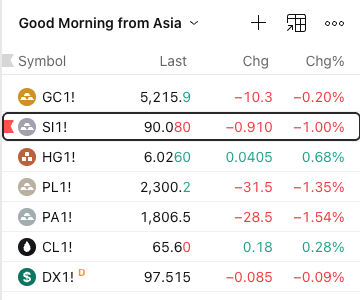
🌏 Good Morning from Asia
Metals start the session under pressure:
Gold −2.4%
Silver −4.6%
Copper −1.6%
Platinum −3.2%
Palladium +1.6%
Liquidity remains distorted — yesterday was a U.S. holiday and China is in Spring Festival Golden Week.
That means one of the key physical buyers is missing… and metals feel it.
Moves in this environment tend to exaggerate — not confirm trend.
#Gold #Silver #Commodities #Macro