I Study IPOs irrespective of what GMP is, If that's your primary parameter to apply an IPO, I might Dissapoint You
Views Are Personal |
Non SEBI Registered |
Another flood of 10-15 Mainboard IPOs is set to hit the markets very soon
But this won't be like August, where 3-4 out of 5 IPOs very of Good/ High Quality
This month will see more Tier-2 and Tier-3 Mandates, very few will be of a good quality, this month The ratio between good quality and poor quality will be 1:2
Hence one needs to be very careful, I am sure that the disparity and Volatility between Anticipated Listing and Real Listing & Post-Listing Action will be very high
In terms of number of Mainboard IPOs, The month of September should be a new record
Keep Minting!
Elevate Campuses IPO
I Am Applying For Post-Listing Action, Happy to hold for Medium Term as well
Elevate is the Largest Institutionalized and Independent Eduacation Platform across Student Accommodation across Higher Eduacation Institutes (HEI) and also own K-12 Assets
It's Portfolio Includes 17 HEIs, 18 K-12 Assets, student capacity of ~95,000, Occupancy of owned Portfolio stands at 99.47%
Top notch KEI Portfolio, solid K-12 Assets, solid Anchor Book, attractive Valuations
Valued at 10× FY27E EV/ EBITDA, on this valuation there is nothing to loose
Highly Predictable Cash Flows, Impressive Management, Ever-growing segment
This is one of those companies which won't be understood by many but will do well
Two Mainboard Anchor Books
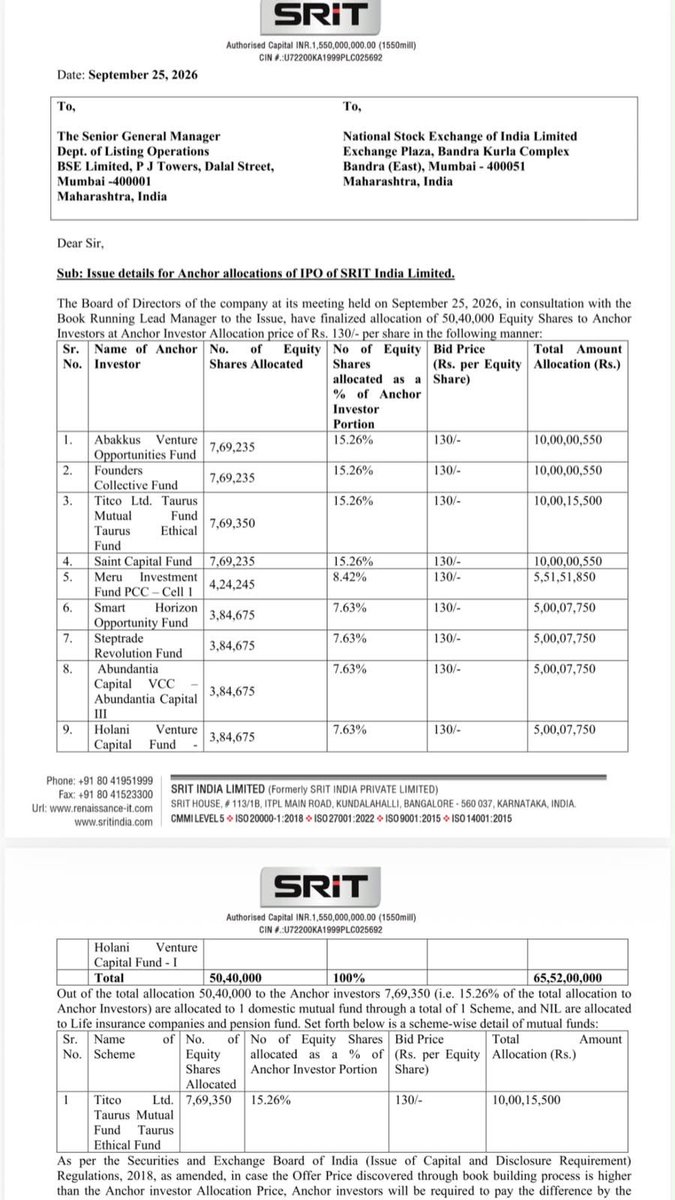
▪ SRIT India Limited
Investors Include :
• Abakkus Venture Fund
• Founders Collective Fund
• Taurus Mutual Fund
• Saint Capital Fund
• Meru Investment PCC
• Smart Horizon Opportunity
• Steptrade Revolution Fund
• Abundantia Capital VCC
• Holani Venture Capital
▪︎ Shah Investor's Home Limited
Investors Include :
• Anubhuti Value Trust
• Gagandeep Credit Capital
• Compact Structure Fund
• Sunrise Investment Trust
Both average books
▪︎ Armee Infotech Limited IPO
Avoiding ❌️
Armee is a combination of IT Infrastructure, Managed Services, RE EPC and RE IPP businesses
The company is now shifting its business model to predominantly Solar EPC
Expensive Valuations, No Growth, 52.5% Retail Quota, Khichdi of RE and IT business
▪︎ Swastika Infra Limited IPO
I would be skipping, neutral on this
T&D EPC Company focusing purely on Government utilities
Good Financials and Financial Position even after growing that fast, buy there are lot of players in the segment
At 9-10× FY27E PE, Follows an Asset-Light Approach, average Anchor Book
Not a bad company, but no compelling
pointer to invest
Adroit Industries Limited IPO Closing Today
I Am Applying Full Reasonable Listing Gains And Long-term
Adroit is a vertically integrated manufacturer and supplier of propeller shafts and torque transmission components used in driveline systems
Product Portfolio :
▪︎ Propeller Shafts
▪︎ CV Double Cardan Driveshaft Assemblies
▪︎ Flanges and Yokes
▪︎ U-Joints
▪︎ Forged products
▪︎ Sleeve/ Slip Yokes
▪︎ Tube/ Weld Yokes
▪︎ Center support Bearings
▪︎ Splined Tube Shafts
▪︎ Short Coupled Shafts
▪︎ End Yokes (Bore, Keyway, Clamp, Splined)
▪︎ Companion Flanges
▪︎ External Splines
▪︎ Mechanics style Cardian Parts and Accessories
Exports account for ~85% revenues for the company, export countries include the US, Canada, Latin America
Clientele : VE Commercial, BEML, Ashok Leyland, Dana, Machine Service Inc, Midwest Auto Parts, Johnson Power, Dacomsa, Godrej and Boyce, Conmat, Oilgear India, Hailstone Innovations, Etc.
Priced at ~17× FY27E PAT, There a good scope left on the table
Good Fundamentals, Good Anchors, Good Segment
Do your own due diligence
Orient Cables IPO Anchor Book
Blockbuster Anchors 🔥👏
Investors Include :
▪︎ Nippon Mutual Fund
▪︎ ICICI Prudential Mutual Fund
▪︎ Border to Coast Pensions Partnership Fund
▪︎ Goldman Sachs Funds
▪︎ Ashoka WhiteOak Capital
▪︎ Aditya Birla Sun Life MF
▪︎ Invesco India Mutual Fund
▪︎ Motilal Oswal Mutual Fund
▪︎ Bandhan Mutual Fund
▪︎ Sundaram Mutual Fund
▪︎ 360 One Equity Fund
▪︎ Edelweiss Mutual Fund
▪︎ Aditya Birla Sun Life Insurance
▪︎ Edelweiss Life Insurance
This one is going to be a super hot IPO, Optic fibre companies are now in solid taste, and attractive valuations are cherry on the top
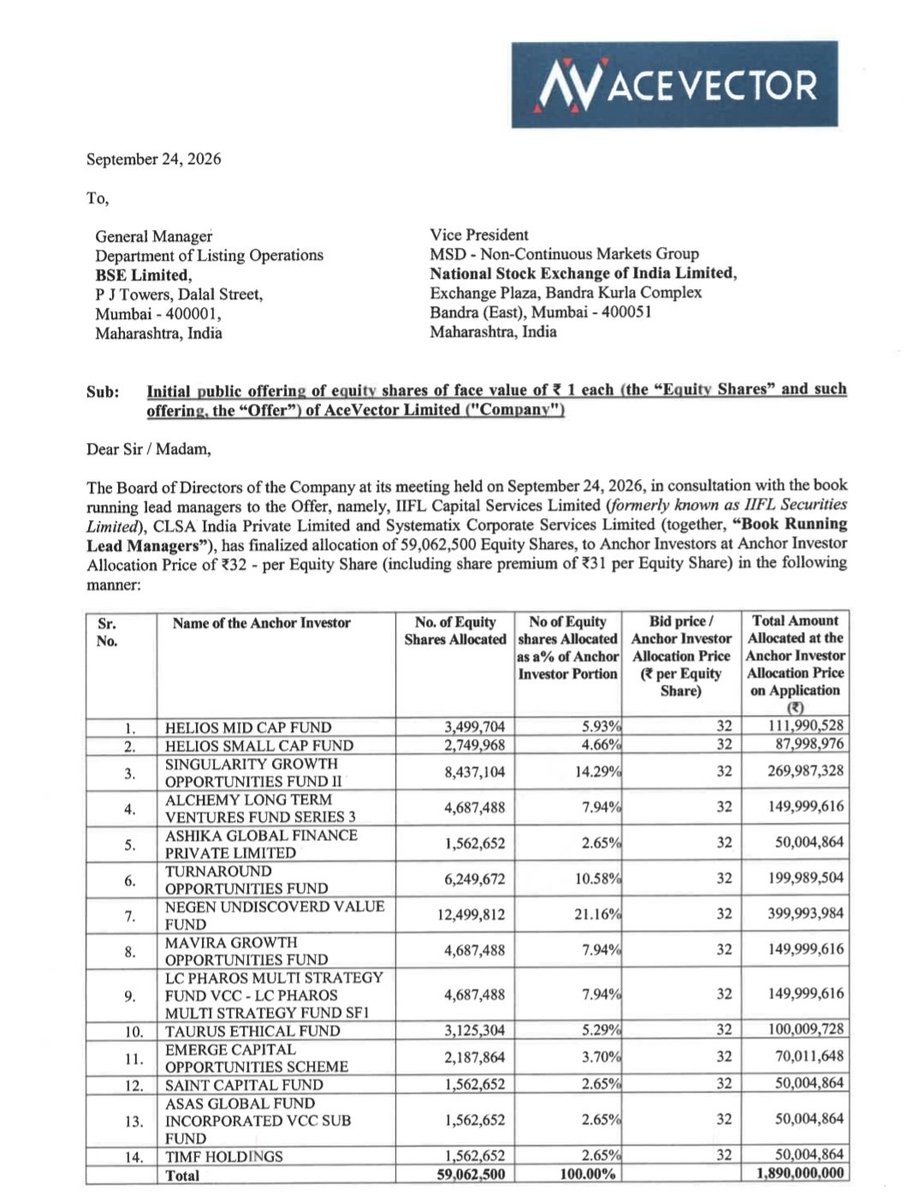
AceVector Limited IPO Anchor Book
Good Names 👍
Investors Include :
▪︎ Helios Mutual Fund
▪︎ Singularity Growth Fund
▪︎ Alchemy Capital
▪︎ IIFL Asset Management
▪ Negen Undiscovered Fund
▪︎ Mavira Growth Opportunities
▪︎ LC Pharoas Multi Strategy
▪︎ Taurus Mutual Fund
▪︎ Emerge Capital
▪︎ Saint Capital Fund
▪︎ ASAS Global Fund
▪︎ TIMF Holdings
Varmora Granito Limited IPO Closing Today
I will be avoiding ❌
Good Company, Solid Brand but has came expensively for the future earnings, the Q1 and Q2 should take a hit due to RM shortage in Morbi
It’s FY27 Growth will be around 6.5-9% (even I doubt this growth), this company can never grow beyond that 10-12%, earnings should be flat to minimal growth in FY27, even on normalised FY28 earnings, it’s at ~30x FY28E PAT, around ~12x FY28E EV/ EBITDA, Kajaria trades at 13x FY28 EV/EBITDA, Somani trades at ~6x FY28 EV/EBITDA
Hence Varmora leaves less/no scope for its upcoming shareholders, GVT segment will grow at 8-10% and rest segments would remain flat to a 2-4% degrowth, hence a slow growth company at expensive valuations
Hopeful that the Assam expansion will drive some growth, but again that’s a new geography for the company
Found no compelling reason to invest in Varmora, although it’s a fundamentally a decent company
Do your own due diligence
A Direct Play into the Robustly growing Light-weight and Affordable jewellery
Priority Jewels Limited IPO
Detailed Analysis
Applying For Reasonable-Big Listing Gains And Long-term
Highlights of the Issue :
Date : 28 August to 1 September
Price Band : 190-200
Size : 91.5 Crore (Full Fresh)
M.cap : 360 Crore
Objects Of The Issue :
▪︎ Repayment Of Debt - 75 Cr
▪︎ GCP - 16.5 Cr
Key Pointers :
▪︎ Priority is engaged in the designing, manufacturing and selling Light-weight, affordable diamond-studded gold and platinum fine jewellery
▪︎ The Company operates in the B2B Segment, It sells to independent jewellers and Retail chains in India as well as International Markets
▪︎ It's Clinetele Includes Caratlane, Kalyan Jewellers, Reliance Retail, Malabar Gold, TBZ Jewellers, Senco Gold, Bafleh Gems, DV Jewelry Corp, Etc.
▪︎ Priority's portfolio comprises Light-weight and Affordable Daily wear jewellery including Rings, Earrings, Pendants, Neckwear, Bracelets as well as occasion couture jewellery, it also makes Lab-grown diamond jewellery based on orders from specific customers
▪︎ The Company currently has 200+ customers, which includes 125 Independent Jewellers and 53 Jewellery Chains; It has presence across 21 states and 3 UTs in India and Exports to 13 countries including the US, UAE, Hong Kong, Belgium and Norway
▪︎ The Company operates through a Gold Metal Loan (GML) Model, which makes its inventory 100% hedged, they have followed this method since a very long time, leading to no exposure of commodity Volatility and generation of pure Operational Profitability rather than inventory gains
▪︎ The Company has 2 manufacturing facilities with an installed capacity of 700 Kgs (currently at ~70% Utilization), equipped with CAD/CAM and 3D Printing Technology
▪︎ Priority is looking to deleverage its books by 75 Crore, which will lead to a straight 6-7 Cr increase in the Bottomline
▪︎ The Company is exploring opportunities in the Middle-east markets and Deepening presence in the US Markets and also expanding its product portfolio into High-end jewellery and silver jewellery
Financials and Personal Assumptions :
FY24
Revenue : 410.6 Crore
PAT : 7.1 Crore
FY25
Revenue : 435.9 Crore
PAT : 10.5 Crore
FY26
Revenue : 539 Crore
PAT : 17.6 Crore
Q1 FY27
Revenue : 147.4 Crore
PAT : 6.5 Crore
FY27E
Revenue : 730 Crore
PAT : 35 Crore
FY28E
Revenue : 900 Crore
PAT : 51 Crore
Valuing Priority at 15× FY28E PAT, Anticipated Value Comes 420, Implying An Upside Of 110%
(Assumptions are based on volume growth of organised Lightweight and Affordable jewellery segment and commodity prices growth)
Better product mix, increase in Utilisation and operational efficiencies will improve the margins going forward with 7-8 cr interest cost savings
The Pre-IPO names were highly notable including Plutus, Cheay Investments (Rosyblue group), Maple Leaf (Keynote Financial), Suvankar Sen (Senco), Abdul Salem (Malabar), Majvibhai Patel (Kiran jewels), Hiren and Samir Sagar (Manubhai jewellers), Shrikant Zaveri (TBZ), Alukkas Varghese Joy (Joyallukas), Tehmasp Printer (IGI), Invicta, Etc.
The biggest Right To Win for this Company is the positioning, the particular segment of Lightweight and Affordable jewellery should grow ~3× than regular jewellery and this Company sits exactly in the segment and also serving Highly-funded, healthy balance sheet driven customers,
And 2nd is the 100% hedged model which will give significant comfort to investors at all the level
Good Anchor Book, Super Juicy Valuations, High Management Quality
Just A Personal View, Only For Educational Purposes
The Largest Stock Exchange is now finally listed after a wait of more than a decade
I would call it a solid debut even though listed at <1% Premium, now 4% above Issue price
It's not easy to control such an enormous float supported by regulatory shocks and expensive Valuations
Happy for all the allotees, but could have wished better and investor friendly Valuations from the crown Jewel of Indian Capital Markets
Expecting 2 quarters of earnings degradation and extended regulatory tightness, so if you're View is short term, 5% return is a superb return
The Crown Jewel of India’s Robust Capital Market Ecosystem
National Stock Exchange Of India Limited IPO (NSE)
Detailed Analysis
Small Risk Takers Can Evaluate For A Horizon beyond 12 months
Keep these three factors into consideration before investing :
▪︎ Short-Term Earnings Headwind
▪︎ Regulatory changes on CAS and options framework
▪︎ Supply from Cat-2 and Cat-3 AIFs without any Lock-in (supply out of the IPO)
Highlights of the Issue :
Date : 17-21 September
Price Band : 1,700-1,785
Size : 22,569 Crore (Full OFS)
M.cap : 4,41,788 Crore
Objects Of The Issue :
▪︎ To Carry out the Offer For Sale for Promoters and Existing Investors and achieving the benefits of listing the shares on the exchanges
Key Pointers :
▪︎ NSE is India's Largest Stock Exchange and one of the Largest Multi-asset Exchange platform Globally
▪︎ NSE is a vertically integrated platform for trading, clearing,
listing and other services comprising data feed, data terminal and licensing services
▪︎ NSE’s product offerings span across multiple asset classes, including cash market, futures, options, mutual funds platform, commodity derivatives, exchange-traded currency derivatives, wholesale debt market and interest rate futures, among others
▪︎ Company's Verticals include :
(Revenue split in bracket)
– Cash Market (11%)
– Futures (8.1%)
– Options (60.2%)
– Mutual Funds Platform (0.1%)
– Listing Services (1.7%)
– Data Connectivity Charges (5.7%)
– Data Centre Rack Charges (1.3%)
▪︎ Data Feed and Terminal Charges (3.3%)
– Licensing Services (1%)
– Clearing and Settlement Charges (1.8%)
– Others (~6%)
▪︎ Till March FY26, the unique registered investors base has grown at a CAGR of ~26% from ~30.9 mn to ~129.1 mn and further reaching to ~132.4 mn. NSE supported 261.4 mn registered investor accounts, 1,328 trading members and 3,005 listed entities
▪︎ The Exchange is looking to deleverage itself by entering new products and expanding its existing portfolio and deepen its penetration
▪︎ NSE is well positioned to benefit from the continued evolution of Indian and global markets, aided by financialization of savings, fund raising, depth of liquidity, wide product offerings, market leadership and operational scale.
Financial and Personal Assumptions :
(*in Crores)
FY24
Revenue : 16,352
EBITDA : 11,442
Normalized PBT : 12,675
FY25
Revenue : 19,176
EBITDA : 13,317
Normalized PBT : 14,914
FY26
Revenue : 18,713
EBITDA : 12,656
Normalized PBT : 14,120
Q1 FY27
Revenue : 5,252
EBITDA : 3,546
Normalized PBT : 4,100
FY27E
Revenue : 20,200
EBITDA : 13,400
Normalized PBT : 14,800
FY28E
Revenue : 22,800
EBITDA : 15,300
Normalized PBT : 16,900
Valuing NSE at 25× FY28E Normalized PBT, Anticipated Value Comes At 1,705, Implying An Downside of 4.5%
Positives :
▪︎ Professional Management
▪︎ Solid Market Leadership Globally and domestically
▪︎ Superb Margin Profile and Return Ratios
▪︎ A Direct Beneficiary of India's Robust Capital Market Growth
▪︎ Entering and ramping up new products
▪︎ Good Anchor Book
▪︎ Extremely Large Scale of Operations
▪︎ Elite Grade Captable
Negatives :
▪︎ High Dependance of Options
▪︎ Regulator continously striking down the trading on F&O
▪︎ Recent ban of Jane Street will itself have a meaningful impact
▪︎ Enormous Supply awaiting to hit the markets without Lockin (in the short term)
▪︎ Significant Supply post Lockin opens
▪︎ Super Short Term Headwind on Earnings
▪︎ Significant decrease in volumes of option trading
▪︎ Regulatory action against many KMPs
It's a superbly high quality company coming at a very wrong time and Valuations not giving any level of comfort, it should've been atleast 10% cheaper from currenct valuations
Institutions would surely get this Stock below Issue Price as Lot of supply is yet to knock the markets
Would have been more happy to give it an apply for short term as well :(
Just A Personal View, Only For Educational Purposes
Moneyview Limited IPO Anchor Book
Solid Book 👏
Investors Include :
▪︎ SBI Mutual Fund
▪︎ ICICI Prudential Mutual Fund
▪︎ HDFC Mutual Fund
▪︎ Goldman Sachs Funds
▪︎ Mirae Asset Mutual Fund
▪︎ Motilal Oswal Mutual Fund
▪︎ WhiteOak Capital MF
▪︎ Aditya Birla Sun Life MF
▪︎ Quant Mutual Fund
▪︎ 360 One Equity Fund
▪︎ Amundi Asset Management
▪︎ HDFC Life Insurance Company
3 SME IPOs Closing Today and two SME IPOs closing tomorrow
1. Robokidz Eduventures
Applying For Reasonable Listing Gains
We had interviewed this company, can have a look
2. FX Multitech
Small Risk Takers can apply for Listing Gains and Medium Term
3. Vivekanand Cotspin
Avoid ❌
4. Anand Seamless
Avoid ❌
5. Himalaya Nutravedics
Risk takers can apply for some Post-listing momentum
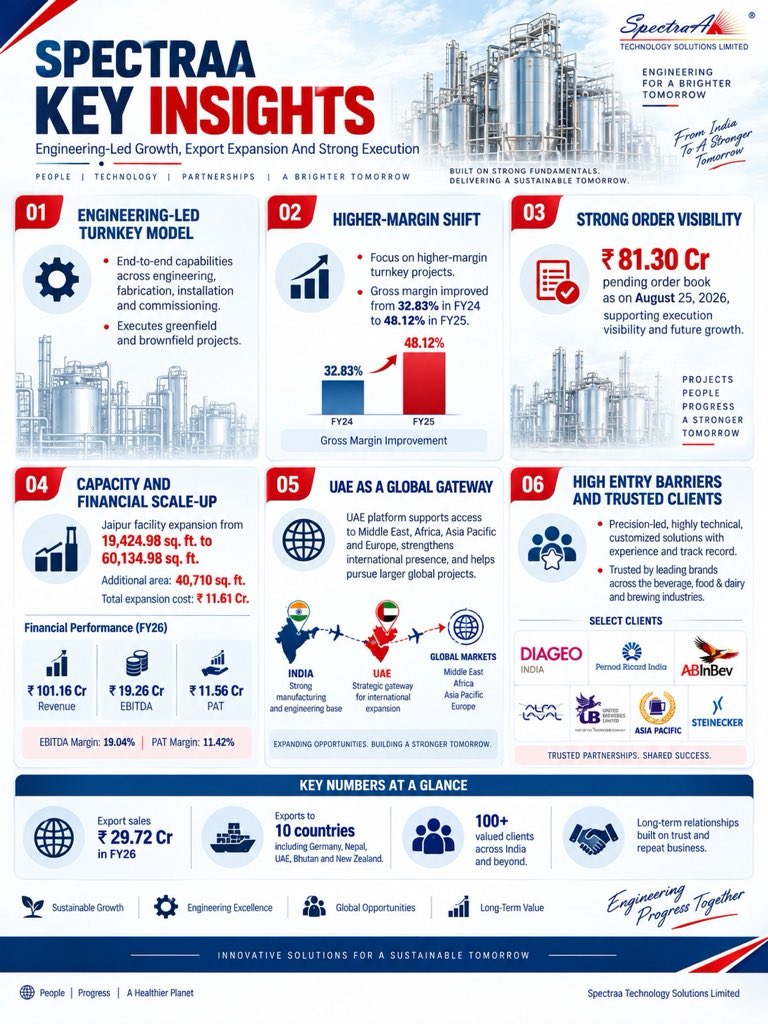
SpectraA Technology Solutions Limited SME IPO
Applying 👍
The Company is a process equipment manufacturer for greenfield and brownfield projects involving Commercial Brewery Equipments, Distilleries, Food & Beverages, Dairy, and other Process Industries
Its capabilities include designing, Fabrication, installation and commissioning
It's clientele includes Diageo India, Pernod Ricard India, AbInBev, Alfa Laval, UBL, Asia Pacific, Steinecker, Etc.
Company Raising 36 Crore in Fresh Issue, Majorly Capital Expenditure (11 Cr), Working Capital (9.5 Cr) Repayment Of Debt (6.5 Cr) and rest for GCP
Priced at roughly ~13.6× FY26
Exports account for ~30% revenues with operations in countries like Germany, Nepal, UAE, Bhutan, New Zealand, Etc; and looking to expand in more overseas geographies
Pre-IPO Investors Include Convivial Advisors (A Motilal Oswal affiliate)
Do your own due diligence