👁️ WOULD YOU SCAN YOUR IRIS TO PROTECT YOUR MONEY?
World has launched World ID for banking and finance, offering proof-of-human tools against AI impersonation and deepfakes.
More security. More biometric questions.
Would you opt in before a high-value transfer?
Correlation breaks can be an early warning - but not a trigger by themselves.
The stronger setup is when BTC/altcoin divergence appears alongside rising open interest, crowded funding and nearby liquidation clusters.
That’s when “decoupling” can turn into forced volatility fast. ⚡
@MadupuruV Appreciate it - enjoyed the exchange too.
And agreed: the follow-through matters more than the first breakout move.
Let’s see if $TIA can keep that relative strength once BTC picks a direction.
📊 THE WEEKLY MARKET LEADERS
Bitcoin finished the week lower.
ETF flows stayed negative.
But a few altcoins clearly broke away from the pack.
Who led? What moved them?
Full Week 42 breakdown 👇 https://t.co/6m9RsNebdm
This may be the clearest sign of real adoption:
The technology disappears from the user experience.
People won’t care whether settlement runs on a blockchain, stablecoin rail or traditional network - they’ll care that money moves instantly, globally and reliably.
Invisible infrastructure can have very visible impact. 🌐
@MaxCrypto The bigger story isn’t a $10K ETH prediction.
JPM Coin is now expanding from Base to Ethereum, giving institutional clients 24/7 access to tokenized bank deposits across the EVM ecosystem.
That’s another major bank moving settlement onto public blockchain infrastructure. 🏦
The bigger signal isn’t just $482B in payment volume.
Visa, Mastercard and Stripe are all turning stablecoins into actual payment infrastructure at the same time.
That’s the transition that matters: from crypto-native settlement to rails businesses and consumers can use without thinking about blockchain. 🌍
The Mastercard/BVNK launch may be the biggest signal here.
Stablecoins are moving from a crypto product into global payments infrastructure - accounts, conversion, payouts and card spending through one stack.
When users can spend stablecoins anywhere Mastercard is accepted, adoption starts to look very different. 🌍
@MadupuruV $TIA is the one I’m watching most closely right now.
A +47% week gets attention - but the real test starts after the breakout.
If it can hold relative strength while Bitcoin stays weak or sideways, that would be much more meaningful than the initial move itself.
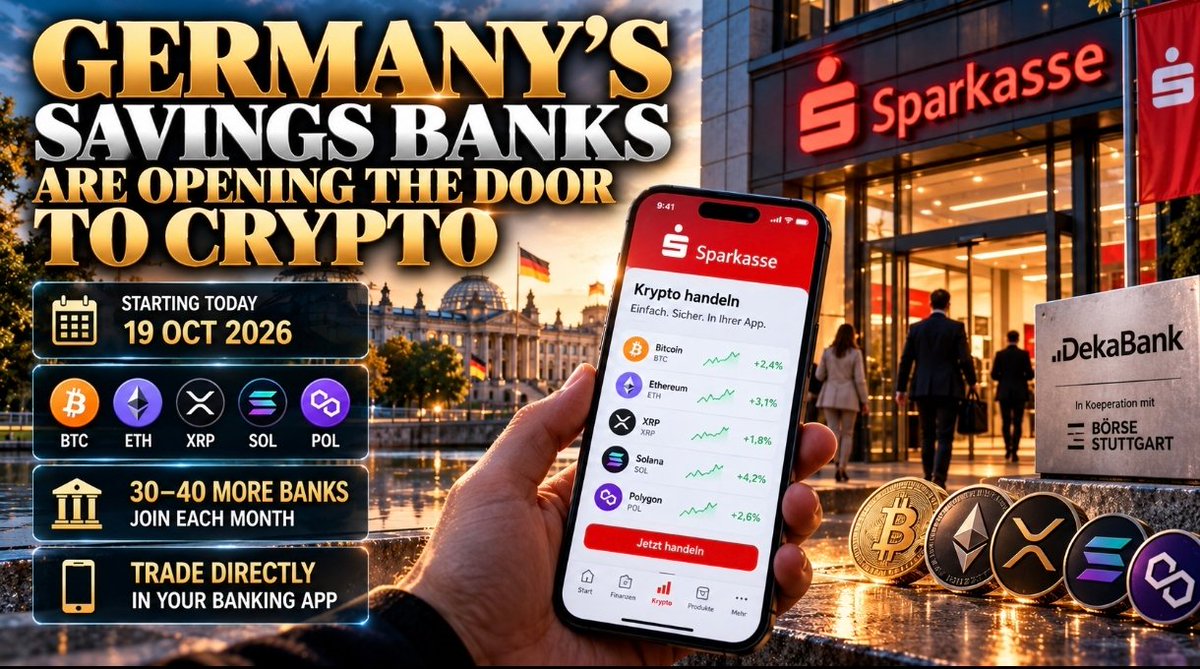
🚨 GERMANY'S SAVINGS BANKS ARE OPENING THE DOOR TO CRYPTO!
Starting today, selected Sparkassen customers can trade $BTC, $ETH, $XRP, $SOL and $POL directly inside their banking app.
30-40 more banks are expected to join each month.
Crypto is moving into everyday banking. 🇩🇪
@MadupuruV Exactly - that’s the part I find most interesting too.
A red week can still hide pockets of real relative strength.
The question now is whether those leaders can hold up once Bitcoin starts moving again.
557M stablecoin transfers is a huge activity signal.
But the bigger question is what sits underneath that number - payments, trading, bots or app activity.
If Solana can turn this transaction lead into sustained real-world payment usage, that’s where the network effect gets much more interesting. 🌐
The real story here is institutional integration.
Securitize is bringing 1:1-backed U.S. equities onchain, and Ripple Prime plans to help plug those assets into a broader institutional trading stack.
That’s meaningful for Ripple’s TradFi footprint.
But it’s not automatically an XRP demand story - the infrastructure angle is the stronger one. 🏦
A new week. New catalysts. New opportunities. ⚡
Our latest Guardian Weekly Outlook covers the inflation shock, Bitcoin's critical levels and two possible paths ahead.
What's your market bias for next week? 📊
The interesting part isn’t just that Solana is catching Ethereum.
USD1 supply on Solana has stayed remarkably resilient while supply on Ethereum and BNB Chain has recently contracted.
If that persists, Solana could become the largest home for USD1 - another sign that stablecoin competition between chains is increasingly about distribution and usage, not just TVL. 🌐
This is the shift worth watching.
Tokenization is moving from “future infrastructure” to actual banking rails.
Wells Fargo is already cutting cross-border settlement from days to minutes, while Goldman and Morgan Stanley openly frame tokenization as a growth opportunity.
TradFi isn’t fighting blockchain anymore.
It’s starting to build on it. 🏦
🚨 CARDANO'S TREASURY ISN'T EMPTY. ITS SPENDING ROOM IS SHRINKING.
On-chain records: 457.4M of 500M $ADA withdrawal allowance used (91.5%).
Only 42.6M ADA remains through mid-2027 - despite ~1.38B ADA in treasury.
Governance now faces a real funding trade-off. 📊
🚨 BITCOIN'S $80K TEST CHANGES THE OUTLOOK.
Hot inflation. Rising Fed concerns. Weakening risk appetite.
But institutional crypto adoption keeps moving forward.
📊 What moved crypto this week?
🟢🔴 3 catalysts. 2 scenarios each.
🧭 Our new Guardian Outlook.
Issue #02 is live.
👇 Read the full analysis: [ARTICLE LINK]
This is an important monetary signal.
Stablecoins aren’t competing only with crypto assets - they’re also competing with bank deposits for short-term dollar liquidity.
If even a 1 bp change in deposit rates measurably slows stablecoin growth, then bank pricing still has real power over onchain dollar demand.
USDC reacting more strongly than USDT makes that even more interesting. 🏦