2025 is in the books, and it was both outstanding and unsatisfying.
If you had told me at the beginning of the year, the Asymmetric Portfolio would more than double the market's performance, I would have taken it.
But after being up 53% early in October, the final results feel unsatisfying.
The good news is, this is a long game. I'm happy to buy some of my favorite stocks 30-50% off their highs, and long-term, these compounding businesses will become compounding stocks.
Thank you to everyone who subscribes, and if you want to see the portfolio's performance, the linked article is free to view.
Bring on 2026!
https://t.co/HjkEtGeWs3
No matter how much work you do on a stock, there's a hard lesson we all learn, eventually:
You might be wrong.
Admitting that upfront and if frees you to make mistakes, which will happen anyway.
@ArunCherian12@growthrapidly Patience. This isn’t even a correction, yet.
A lot of these companies (IREN included) will go to $0. Wait for the trough of disillusionment.
No matter how much work you do on a stock, there's a hard lesson we all learn, eventually:
You might be wrong.
Admitting that upfront and if frees you to make mistakes, which will happen anyway.
Being an investor isn't a part-time hobby. It permeates every part of your life.
You think about investing when watching a movie.
You think about investing when you're shopping.
You think about investing when you're sleeping.
Just ask my wife, this is a blessing and a curse.
$FIX is down because the margin expansion story is over.
HVAC only has so much pricing power and if/when supply and demand go back to normal we could see operating margins cut to historical norms of ~5%.
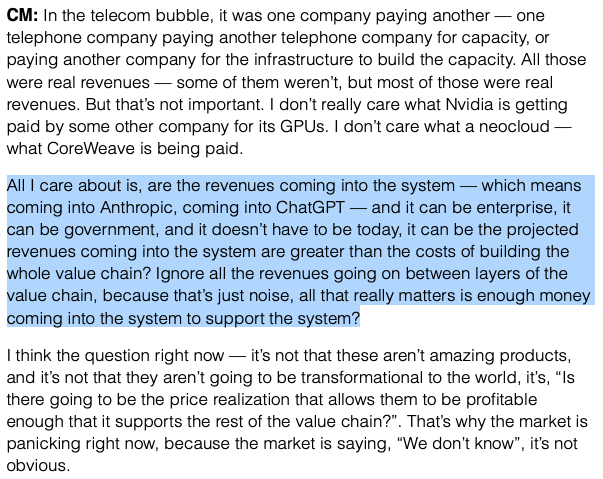
Ben Thompson interviewed Craig Moffett today and he articulated something I've been saying and wring about for a while in a great way.
Neocloud revenue, chip revenue, equipment revenue is all meaningless when it comes to the bubble discussion. The only thing that matters is money coming into the system. If the money coming into the system (Anthropic, OpenAI, etc) doesn't justify the Capex, none of the details matter.
What if everyone is right about AI but wrong about the investment?
This will probably get under the skin of quite a few people, particularly those heavily invested in AI infrastructure businesses. But I would encourage everyone to put their biases aside for a moment, forget about the stocks they own, and examine these businesses from a bird’s eye view. Are they truly extraordinary businesses with wonderful economics, sustainable competitive advantages, pricing power, and high returns on capital? Or are we confusing extraordinary demand for something with the existence of an extraordinary business?
I think this is something too many investors overlook. History is filled with industries that transformed the world and experienced tremendous growth, yet many of the businesses operating within them struggled to generate attractive returns for shareholders. Airlines revolutionized transportation, telecommunications connected the world, and railroads transformed economies, but that didn’t automatically make the companies wonderful investments. Just because the world desperately needs something doesn’t mean providing it is an extraordinary business.
When I examine AI infrastructure businesses, I see extraordinary demand and revenue growth, but also staggering capital requirements, huge financing needs, and expensive equipment that becomes outdated surprisingly quickly. Unlike businesses that can grow enormously without requiring much additional capital, these companies need to spend billions simply to expand their capacity. And eventually, actually rather quickly, much of that equipment will need to be replaced. So how much of this impressive growth will actually translate into cash that belongs to shareholders?
Consider depreciation, which I think is one of the most underappreciated aspects of these businesses. Imagine a company purchases $10 billion of computing equipment and assumes it will remain economically useful for 5 years, resulting in $2 billion of annual depreciation. But if the equipment’s actual economic life turns out to be 4 years, that annual economic cost increases to $2.5 billion. That’s a $500 million difference simply because one assumption about the useful life of the equipment changed.
And here’s something even more fascinating. The same technological advancements making AI increasingly powerful may simultaneously make existing computing equipment less competitive. If tomorrow’s equipment delivers twice the computing power for the same price, what happens to the economics of yesterday’s infrastructure? Technological progress can create extraordinary value for society while simultaneously destroying some of the economic value of the assets purchased to support it.
Then there’s pricing power, which deserves considerably more scrutiny. When demand exceeds supply, providers can enjoy attractive prices, but that doesn’t establish a durable competitive advantage. What happens when competitors expand capacity, supply catches up to demand, and customers gain more alternatives? Will these businesses retain attractive pricing, or will competition eventually transfer much of the economic benefit to customers in the form of lower prices?
I’m also fascinated by the enormous emphasis on EBITDA and revenue growth. Imagine a company invests $10 billion in infrastructure and generates $3 billion in annual EBITDA, which sounds extraordinary until you subtract $2 billion in economic depreciation and $600 million in financing expenses. Suddenly, you’re left with just $400 million in pretax earnings. The business hasn’t changed, but your understanding of its economics certainly has.
1/👇
This video with @TMFJaguar was pretty timely earlier this week. $META has a lot of questions about how it's going to monetize all of this spending, even if the core business gets better.
https://t.co/pQWrtdKt85