$NBIS personal view:
Q3 revenue came in at $981 million, up 571% year over year. AI cloud adjusted EBITDA margin reached 53%.
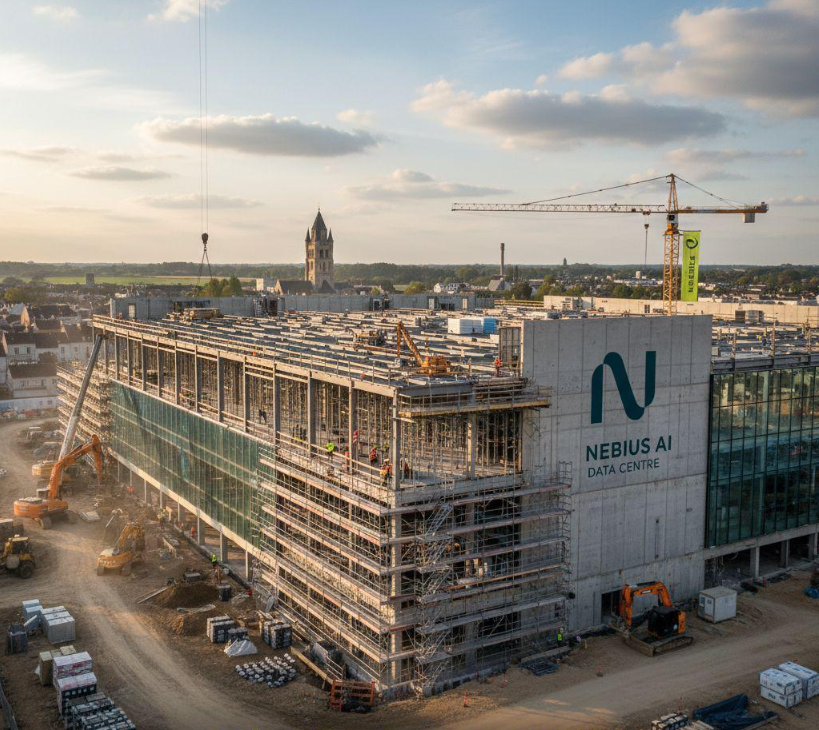
The company cut its 2026 revenue outlook to the low end of the previous range due to third-party data center delays. Some capacity has been pushed into 2027, but management said the contracts are still in place.
Management continues to guide for significant scale in 2027, with revenue expected to reach $12–13 billion.
The main risk right now is execution and delivery timing. If they can bring the delayed capacity online, operating leverage should improve and support a valuation reset.
I still see $NBIS as a high-conviction name. If execution holds, I think the stock can retest $195 by the time they report Q4 results.
Like❤️ and follow🔂 me for more news and information.
$KEEL insiders bought shares in the open market.
On November 16, COO Liam Wilson purchased 28,942 shares at $1.73 per share in the open market.
His total holdings increased to 129,920 shares (about 30% of his position).
On November 9, Director Edith Hofmeister bought 15,000 shares at $1.89 per share.
Both transactions were reported as open-market purchases, not awards or grants.
Like❤️ and follow for more stock analysis.
$NBIS is down ~57% from its October peak of $255, now around $109.
The business hasn’t changed much. It still has strong contracted revenue, a large RPO backlog, and major deals with Microsoft and Meta.
If the company executes on its 2027 scale-up plan, margins could improve quickly.
The selloff looks more sentiment-driven than fundamental.
Remember to like❤️ and follow for more stock analysis.
$KEEL is one of the best value plays in the AI data center space right now.
It has fallen more than most of its peers.
$Hive peaked at $4.2 and is now around $1.6.
$KEEL peaked at $7.4 and is now around $1.8.
The drawdown has been deeper, which means the upside potential is also larger if the company executes.
Among the AI data center names, $KEEL currently offers one of the biggest gaps between its peak and current price.
$KEEL
Remember to like❤️ and follow for more stock analysis.
Anthropic is going public this week.
Expected to price on November 18
Start trading on November 19 on Nasdaq under ticker $ANT
Price range: $70 – $78 per share
Offering 825 million shares
Fully diluted valuation could reach up to ~$1.4 trillion
Nvidia is also participating through a private placement.
This will be one of the largest IPOs ever and the first pure-play frontier AI lab on the public markets.
Like❤️ and follow for more stock analysis.
$NVDA reports earnings this week under new leadership.
Jensen Huang has stepped down as CEO. CFO Colette Kress is now interim CEO.
This will be the first earnings report without Huang.The market is watching two things:
1⃣Whether data center demand is still strong
2⃣Whether the leadership change affects customer orders or guidance
$NVDA has already lost a significant amount of market value since October amid broader concerns about the AI buildout.
Tuesday’s report will show if the core business is still accelerating, or if the noise is starting to matter.
$NVDA
Remember to like❤️and follow for more stock analysis.
JUST IN: FAA returns to full operations after nationwide ground stop
The FAA is back to full operations after decades-old equipment issues caused a nationwide ground stop, according to Secretary Sean Duffy.
This is the third nationwide grounding of all departures since 9/11.
More than 12,500 flights have been canceled since Friday.
Duffy is now asking Congress for $50 billion to replace the old analog telecom equipment that failed.
Remember to like❤️ and follow for more stock analysis.
$NBIS is now an execution story.
The company added roughly $7B in debt in Q3, and 2027 capex is expected to be $40–45B.
If they execute, 2027 revenue could reach $12–13B with an exit run rate around $18B.
But that would still leave them with an estimated $20–25B in net debt by the end of 2027.
That puts leverage around 4.5x 2027 revenue — getting into a higher-risk zone.
The upside is real if they deliver on the Microsoft and Meta contracts.
The downside is also real if they don’t.
This is high risk, high reward.
More of a trade than a low-risk investment right now.
$NBIS
Remember to like❤️ and follow for more stock analysis.
AI infrastructure stocks have a bigger problem than most people think: the cost of capital.
Higher rates mean higher funding costs, and these companies are spending tens of billions building AI capacity.
Look at the numbers:
$CRWV — $47.5B debt | $4.1B cash | $37–39B FY26 capex
$NBIS — $40–45B expected FY27 capex
$IREN — $15B remaining FY27 capex
$SPCX — ~$89.9B cash + short-term securities
$ASTS — heavy satellite spending, funding and cash runway matter
The key point is simple:
Even if rates fall and lower the cost of capital, it won’t save companies with weak execution, project delays, or tight cash flow.
Capital efficiency matters more than ever.
If rates start coming down, which company benefits the most?
$CRWV, $NBIS, $IREN or $ASTS?
Drop your pick below👇
Remember to like❤️ and follow for more stock analysis.
🚨 $NBIS BEAT THE NUMBERS. SO WHY IS THE MARKET STILL DOUBTING IT?
Q3 revenue hit $980M, up from just $50M in Q1 2025.
Look at what's coming:
🔹 2027 revenue outlook: $12–13B
🔹 Pre-tax breakeven targeted by end of 2027.
🔹 75–85% of 2027 CapEx expected to be covered by customer prepayments and contract-backed financing.
Rapid growth, a path to profitability, and less reliance on shareholder dilution.
Maybe the problem isn't $NBIS. Maybe the market isn't looking far enough ahead.
#NBIS #AI
If this was helpful, please like and follow for more.
$NBIS Q3 revenue: $981M (+571% YoY)
Beat estimates by ~$70M.
Stock still fell ~16%.
Market is focused on:
- 2026 revenue guidance cut
- Capex raised to ~$27B
Q3 AI Cloud adjusted EBITDA margin: 53.2%
Is the market overreacting to the guidance, or is the execution risk real?
Your attention is my motivation to update. Thank you for your support!