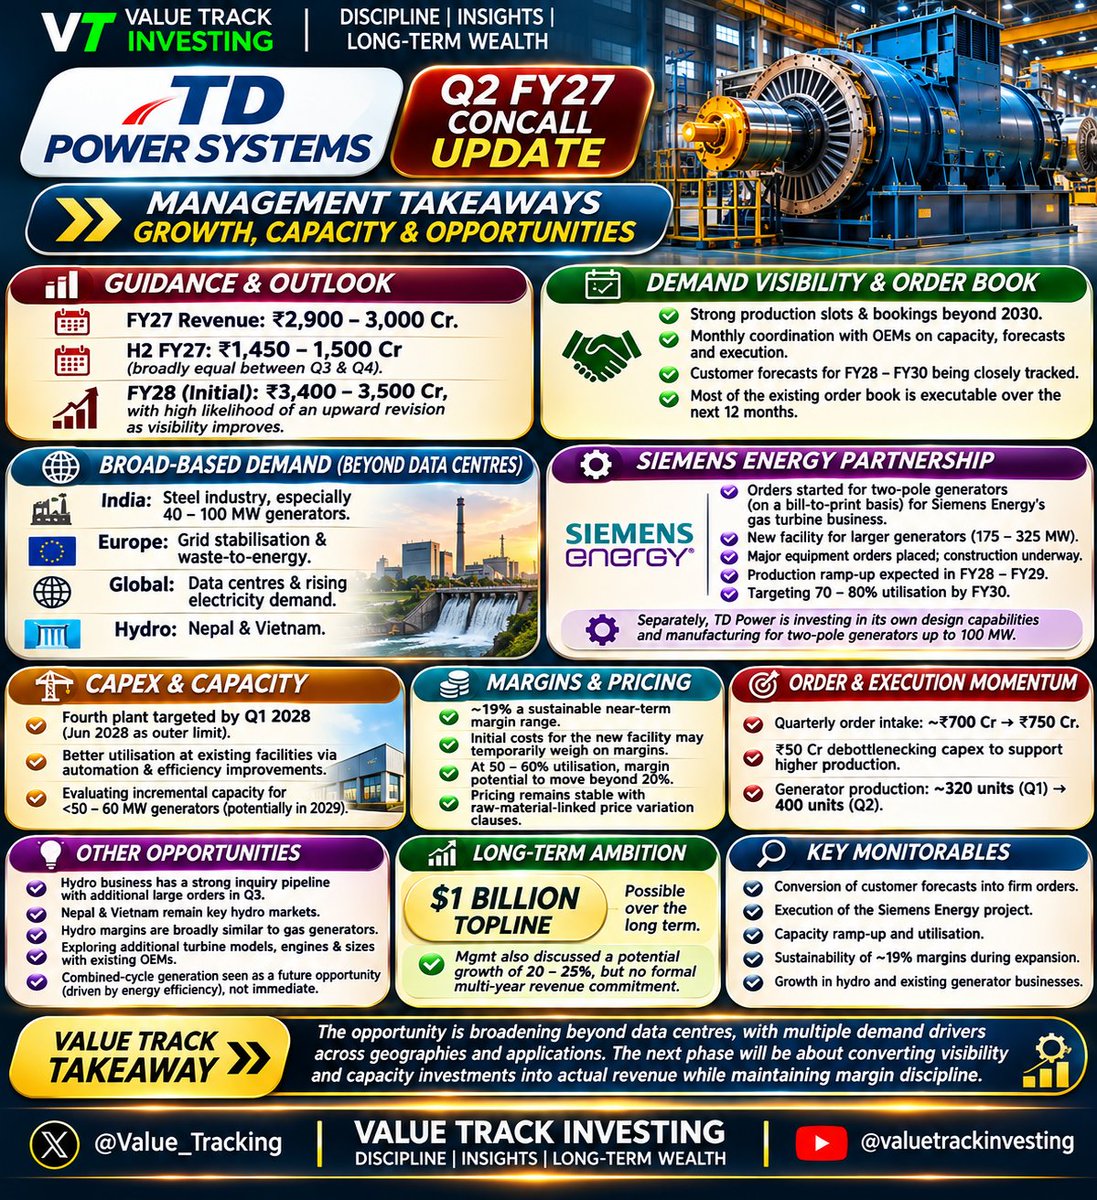
⚡ TD POWER SYSTEMS: BEYOND THE DATA CENTRE STORY!
The Q2 FY27 concall points to expanding demand across multiple industries, strong order visibility and a significant capacity expansion cycle.
📊 Management Guidance
• FY27 revenue: ₹2,900–3,000 Cr.
• FY28 initial guidance: ₹3,400–3,500 Cr.
• H2 FY27 revenue expected at ₹1,450–1,500 Cr.
• Management sees potential for an upward FY28 revision as visibility improves.
🌍 Demand Visibility
• Production slots and bookings extending beyond 2030.
• Strong demand from Indian steel, European grid stabilisation and waste-to-energy.
• Global data centre demand and rising electricity requirements.
• Hydro opportunities in Nepal and Vietnam.
🤝 Siemens Energy Partnership
• Manufacturing two-pole generators for Siemens Energy.
• New facility designed for 175–325 MW generators.
• Production ramp-up expected in FY28–FY29.
• Targeting 70–80% utilisation by FY30.
🏭 Capacity & Margins
• Fourth plant targeted by Q1 2028.
• ~19% sustainable near-term margin outlook.
• Potential to exceed 20% margins as new facility utilisation improves.
• Quarterly order intake increased from ~₹700 Cr to ~₹750 Cr.
💡 Long-Term Opportunity
Management believes a $1 billion revenue opportunity is possible, without committing to a timeline.
⚠️ Key Monitorables
• Customer forecasts converting into firm orders.
• Siemens project execution and capacity utilisation.
• Margin sustainability during expansion.
• Hydro business growth and new OEM opportunities.
🎯 VALUE TRACK TAKEAWAY
The growth opportunity is broadening beyond data centres. TD Power's next phase depends on converting demand visibility and capacity investments into revenue while protecting margins.
▶️ Watch more analysis on YouTube:
https://t.co/YAV6QVfvST
Disclaimer: For educational purposes only. Not investment advice.
#TDPowerSystems #TDPS #Q2FY27 #ConcallHighlights #PowerGeneration #DataCentres #SiemensEnergy #RenewableEnergy #ElectricalEngineering #ValueTrackInvesting
⚙️ RACL GEARTECH: MORE THAN JUST Q2 NUMBERS!
RACL is gradually transforming from a two-wheeler gear supplier into a global precision engineering partner.
📊 Q2 FY27 Highlights
• Revenue: ₹139 Cr | +11% YoY
• EBITDA: ₹36.7 Cr | +16% YoY
• PAT: ₹17.6 Cr | +46% YoY
• Operating margin: ~26%
🌍 What Makes the Story Interesting?
• Global OEM relationships: BMW, ZF, KTM and Royal Enfield.
• Europe contributes 51% of Q2 sales; North America 15%.
• Expanding into passenger cars, EVs and premium components.
• BMW programmes and ZF steering products offer future ramp-up potential.
⚠️ Key Risks to Monitor
• H1 operating cash flow: ₹14.4 Cr against PAT of ₹26.5 Cr.
• Debt increased approximately ₹37 Cr in six months.
• New programme selection must translate into regular volumes.
• Valuation around 33x P/E needs earnings growth to justify it.
🎯 VALUE TRACK VIEW
RACL's customer relationships, product complexity and global reach are encouraging. However, cash conversion, debt discipline and execution will determine whether this opportunity translates into sustained shareholder value.
▶️ Watch more analysis on YouTube:
https://t.co/YAV6QVfvST
Disclaimer: For educational purposes only. Not investment advice.
#RACLGeartech #RACL #Q2FY27 #AutoAncillary #PrecisionEngineering #AutomotiveComponents #EVComponents #MakeInIndia #IndianStockMarket #ValueTrackInvesting
🏍️ EICHER MOTORS Q2 FY27 CONCALL: WHAT MANAGEMENT IS SAYING
Royal Enfield's demand momentum remains strong, while Eicher Motors is preparing for its next phase of capacity-led growth.
🔍 Key Management Takeaways
• Strong bookings momentum with no signs of rural demand slowdown.
• UP, West Bengal and Bihar continue to show robust demand.
• Himalayan 440 received an exceptional response.
• Flying Flea C6 expands Royal Enfield's electric mobility ambitions.
• Capacity expansion targets 2 million units by Q2 FY28.
• New Andhra Pradesh plant to add 4.5 lakh units of annual capacity.
• VECV continues to see healthy commercial vehicle demand.
• Management prioritises absolute profit growth over margin guidance.
• Focus remains on the 250–750cc segment.
🎯 Value Track View
Strong demand, product innovation and aggressive capacity expansion support the long-term growth outlook. Monitor cost inflation, margin protection and execution of expansion plans.
What is your view on Royal Enfield's long-term growth opportunity?
▶️ YouTube: https://t.co/YAV6QVfvST
#EicherMotors #RoyalEnfield #Q2FY27 #ConcallHighlights #ManagementCommentary #AutomobileSector #TwoWheelers #CommercialVehicles #ElectricMobility #IndianStockMarket #ValueTrackInvesting
🇮🇳🇺🇸 INDIA–US TRADE DEAL: A POTENTIAL TARIFF ADVANTAGE FOR INDIA
The US has reportedly assured India of more favourable tariff treatment compared with competing economies.
📌 Why this matters:
- Could improve India's competitiveness in export markets.
- Potential advantage for textiles, apparel, leather, footwear and engineering goods.
- May strengthen India's position against competing suppliers such as Vietnam, Bangladesh and Cambodia.
🔍 What investors should watch:
- Final tariff rates and product coverage.
- Progress of the Section 301 investigation.
- Trade agreement negotiations and implementation timeline.
- Impact on export-oriented companies and order flows.
⚠️ Important: An assurance is not a signed trade agreement. Final terms and implementation details remain subject to negotiations.
📊 Value Track View: A potentially positive development for Indian exporters, but the actual benefit will depend on the final tariff structure.
▶️ YouTube: https://t.co/YAV6QVfvST
#IndiaUSTradeDeal #IndiaUSRelations #USIndiaTrade #IndianExports #TariffNews #TradeAgreement #TextileStocks #EngineeringExports #ExportStocks #IndianEconomy #StockMarketIndia #ValueTrackInvesting
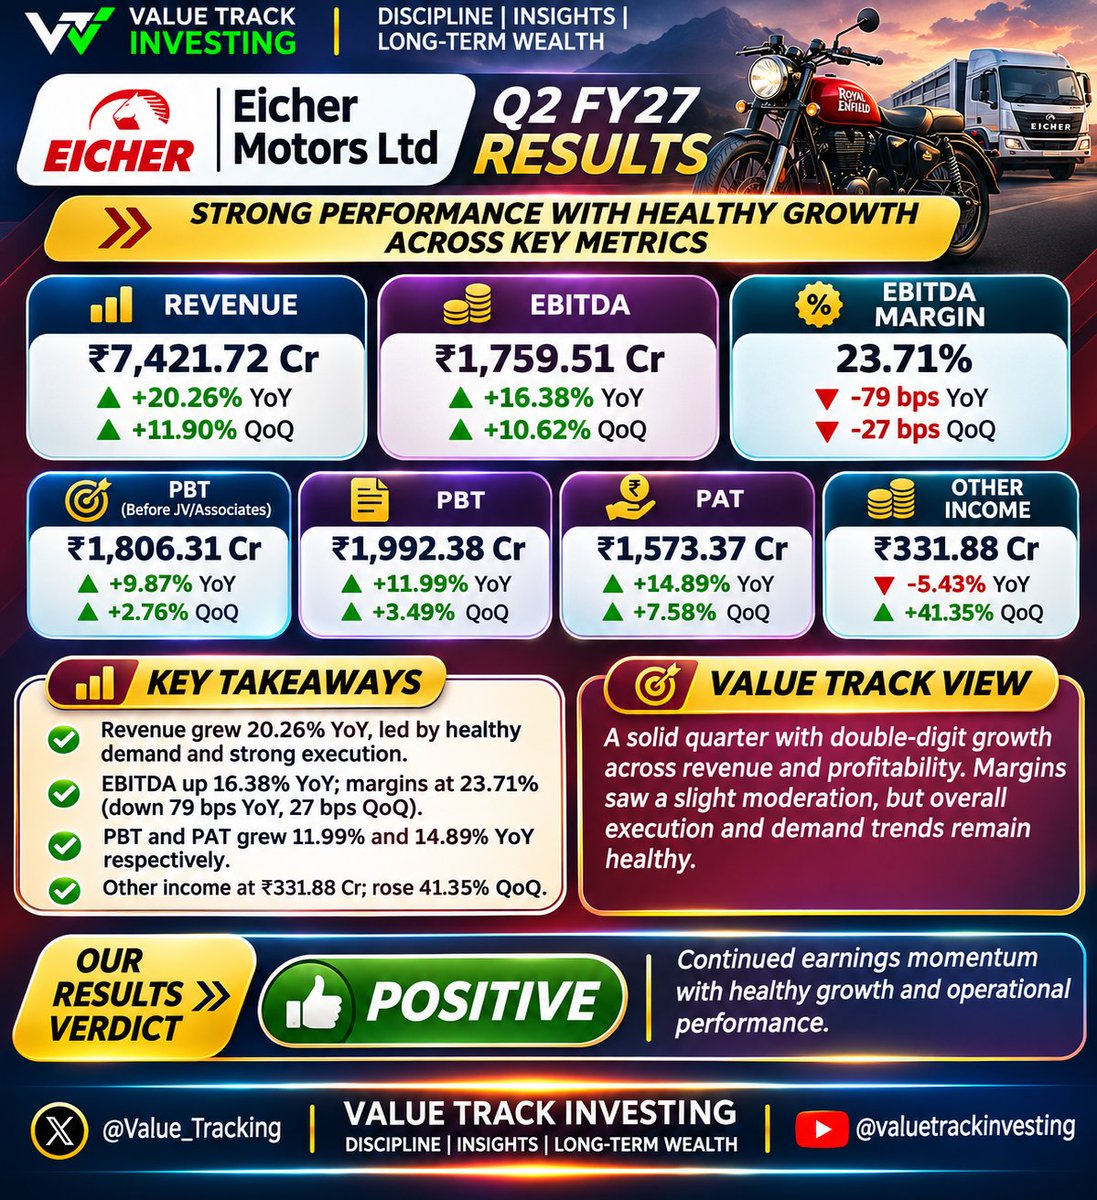
EICHER MOTORS Q2 FY27: Strong Growth, Slight Margin Pressure 🏍️
Eicher Motors delivered a healthy quarter, with double-digit growth across revenue, EBITDA and PAT.
📊 Q2 FY27 Highlights
- Revenue: ₹7,421.72 Cr | +20.26% YoY
- EBITDA: ₹1,759.51 Cr | +16.38% YoY
- EBITDA Margin: 23.71% | Down 79 bps YoY
- PBT: ₹1,992.38 Cr | +11.99% YoY
- PAT: ₹1,573.37 Cr | +14.89% YoY
Business Overview
Eicher Motors operates in the automotive sector through Royal Enfield motorcycles and VE Commercial Vehicles, its commercial vehicle joint venture with Volvo Group.
🔍 Key Takeaways
- Revenue growth remained strong.
- Profitability improved in absolute terms.
- Margin contracted compared with last year.
- PAT growth was supported by healthy operating performance.
📌 Value Track Verdict: POSITIVE
A solid quarter with healthy top-line and earnings growth. However, investors should monitor margin trends, demand momentum and operating costs in upcoming quarters.
What is your view on Eicher Motors at current valuations?
#EicherMotors #RoyalEnfield #Q2Results #Q2FY27 #StockMarketIndia #IndianStocks #AutoSector #AutomobileStocks #EarningsUpdate #ValueTrackInvesting