Finance & technology. Medium & long-term holds. Research, not tips. Not financial advice - do your own due diligence. Follow for the names I’m actually holding.
$OII — Unpopular opinion: the most successful robotics company in the stock market trades at 13x earnings and gets filed under "energy equipment."
Oceaneering International closed Tuesday at $46.11 (+0.39%), up ~92% year to date. And almost nobody in the robotics conversation has heard of it. The robots are 3,000 feet underwater.
WHAT IT ACTUALLY DOES
Five segments: Subsea Robotics (the crown jewel), Manufactured Products, Offshore Projects Group, Integrity Management & Digital Solutions, and Aerospace & Defense Technologies. Founded 1964, ~11,100 employees, Houston. This isn't a startup pitch — it's a six-decade-old operation that became a robotics company from the inside out.
THE MOAT, IN ONE NUMBER: 275
Oceaneering runs the world's largest fleet of work-class ROVs — 275 work-class vehicles plus ~60 observation-class, with ~2,400 people running ROV ops and over 100,000 missions a year (per SVP Martin McDonald). A January teardown put hard numbers on it: 99% uptime in 2024, 61,000+ days of fleet utilization, 420,000+ dive hours logged, 400,000+ km of seabed surveyed. Nobody else operates at anything close to this scale.
The edge isn't just iron. Oceaneering has been advancing onshore-controlled remote operations for more than 20 years — moving pilots off vessels and into operations centers. That's exactly where the industry's "resident autonomy" trend is going: seabed-resident systems doing pipeline inspection without a surface vessel at all. One North Sea field running Oceaneering resident systems reportedly cut dedicated inspection-vessel campaigns by ~60%. When the daily cost of a vessel is the bottleneck, autonomy is the margin.
THE NUMBERS
~$4.55B market cap. Trailing P/E 13.0x on $3.49 EPS. Net income $353.76M, net margin 12.2%, ROE 18.4%, debt-to-equity 0.42, annual sales $2.78B, 93.9% institutional ownership. YTD +91.89%, 1-year +81.89% — but it's cooled 13% in the last month, sitting well under its $54.25 52-week high. Last August it locked in ~$180M of 4-year Petrobras ROV contracts in Brazil — backlog visibility in a services business that usually lives quarter to quarter.
Here's the tension: the Street rates it a consensus Hold — four Holds, one Buy, average $45 price target, which is BELOW the $46.11 price it's already trading at. Citi (Aug 11) took the target to $52 with a neutral; Barclays took it to $47, equal weight, back in July. Translation: the stock has outrun the targets and the analysts haven't chased it. Either they know something, or they haven't recategorized it yet.
WHY THE FUTURE-OF-MONEY LENS APPLIES
Subsea is the last frontier of industrial automation: inspection, maintenance, repair, and decommissioning on equipment humans literally cannot reach. Every offshore wind farm, every deepwater tieback, every platform slated for decommissioning needs exactly this. And the defense kicker is real — Oceaneering's Aerospace & Defense Technologies segment does real work for the U.S. Navy, and CEO Rod Larson just presented the segment at the Gabelli Aerospace & Defense Symposium on Sept 10.
Catalyst calendar: CFO Mike Sumruld is at the TD Cowen Energy Conference in Austin on Sept 24 and the PEP Energy Conference on Sept 29. That's historically where backlog and day-rate commentary drops.
The honest risk: it's still an offshore-energy cyclical. When oil capex pulls back, day rates compress and the robots sit. The Street's tepid stance is basically a bet that the cycle turns before the autonomy premium ever shows up in the multiple.
THE READ-THROUGH
$FTI is the other resident-subsea-autonomy horse — TechnipFMC is building the same future from the EPC side. $RRX sells the motion layer (servo motors, drives) that every one of these robots runs on. $KTOS is the defense-unmanned comp for the Navy side of the house. And $CGNX is the machine-vision layer that will eventually sit on top of every autonomous inspection vehicle.
So the question: is $OII an oil-services cyclical at 13x — or mispriced industrial robotics that Wall Street hasn't recategorized yet? Drop your take below.
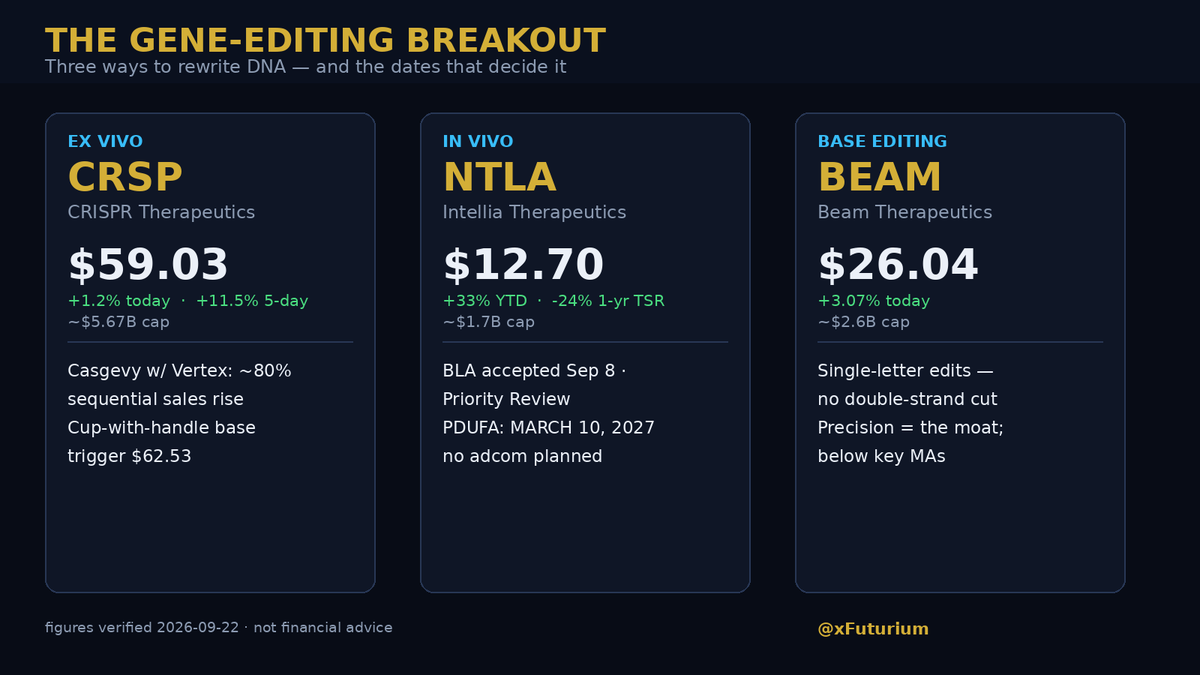
$NTLA is racing toward the first-ever in-body gene-editing approval — and the whole group is breaking out. $CRSP is carving a cup-with-handle base, $BEAM ripped 3% today, and one $CRSP director just dumped 45% of his stake. The gene-editing trade is splitting open.
Last Thursday the group moved as one. Investor's Business Daily flagged it: $CRSP surged 9.8% to $57.33, $BEAM jumped 6.8% to $24.67, $NTLA popped 6.7% to $12.26 — right after the gene-editing names presented at the H.C. Wainwright conference. Even newcomer Scribe Therapeutics ($SCTX, public since July) bounded 10.5% to $32.14. MarketSurge shows $CRSP forming a cup-with-handle base with a $62.53 breakout trigger. Today the momentum got its retail seal: the Motley Fool published its "4 best CRISPR companies for 2026" list — data as of today.
$CRSP — the ex vivo incumbent. The technology: edit the patient's cells outside the body, infuse them back. Casgevy, developed with $VRTX, is the world's first approved CRISPR therapy — a one-time treatment for beta thalassemia and sickle cell — and its sales reportedly rose nearly 80% sequentially (Fool, Sept 8). The company sits on ~$2.36 billion in cash to fund the pipeline. $59.03 at today's close (+1.2%), ~$5.67 billion market cap, 5-day run of +11.5%. The skeptic file: director Ali Behbahani sold 13,679 shares on Sept 17 — about $781,000 — cutting his position by 45%, per the SEC filing. Negative earnings, negative margins: this stock is priced on pipeline belief, and insiders selling into a breakout is the data point that keeps the honest.
$NTLA — the in vivo first-mover. The technology: edit the genes inside the body, delivered by lipid nanoparticles. The lead drug, lonvoguran ziclumeran (lonvo-z), targets hereditary angioedema — a rare, potentially fatal swelling disorder where current treatments mean injections or pills as often as twice a week. The Phase 3 HAELO trial (April): a single infusion cut swelling attacks 87%, and more than 60% of treated patients were attack-free and off all other therapy for a full six months, vs 11% on placebo. Then the regulatory catalyst: on Sept 8 the FDA accepted the Biologics License Application and granted Priority Review — PDUFA target action date March 10, 2027, with no advisory committee meeting planned. If approved, it would be the world's first in vivo CRISPR-based therapy and the only one-time treatment for HAE. The partner math: Regeneron is alongside on nex-z for ATTR amyloidosis, where the FDA just lifted a clinical hold and the ATTR-PN study restarted — but the hold (a patient hospitalization, serious liver toxicity) is the risk file in one line. $12.70 today, ~$1.7 billion cap, +33% YTD — but still -24% on a 1-year total-return basis. Citigroup reiterated Outperform; MarketBeat's average target is ~$20.98. And remember: the company sold $150 million of new stock in April. Dilution is the tax this sector pays for progress.
$BEAM — the molecular pencil. Base editing rewrites a single genetic letter instead of cutting both DNA strands — the industry's answer to the persistent safety question that keeps some investors away from classic CRISPR-Cas9. $26.04 today (+3.07%), ~$2.6 billion market cap. The honest read: per IBD, shares remain below their key moving averages even after the Thursday pop. Precision is the moat; execution is the open question.
The second-order read: a one-time cure rewrites revenue math. HAE patients inject twice a week forever under the old model; a single $NTLA dose at an insurer-approved price converts a lifetime of chronic drug revenue into one payment — and that flips the economics for every rare-disease franchise downstream. The names that capture the economics alongside: $VRTX on Casgevy, $REGN on nex-z. The names creating dilution risk: $SCTX, $PRME, $DTIL — the newcomers pricing IPOs into the momentum. And the longest-run read-through is on my own sector list: S30's surgical giants ($ISRG, $SYK, $MDT) sell the scalpels and robots for diseases gene editing wants to eliminate. If in vivo editing works, procedure volume is the final thing that reprices.
Context: Nasdaq closed at a record +0.45% Tuesday; biotechs had a bullish session with the XBI flashing buy signals (IBD, after-hours). The group moves together until the FDA separates them. March 10, 2027 is the first date that does.
Which of the three do you trust most by 2030: the ex vivo incumbent ($CRSP), the in vivo first-mover ($NTLA), or the molecular pencil ($BEAM)? Reply with your pick.
One ticker you'd hold for a decade. No trading, no peeking — just locked in.
My pick: $TSM. Chips are the oil of the next decade, and TSMC is the world's leading-edge refinery — a lead nobody's rebuilding in ten years. The whole AI boom rents a floor in its fabs.
Drop yours (and your why) in the replies.
THE MARKET CLOSED. HERE'S EVERYTHING THAT MOVED IT TODAY:
THE CLOSE
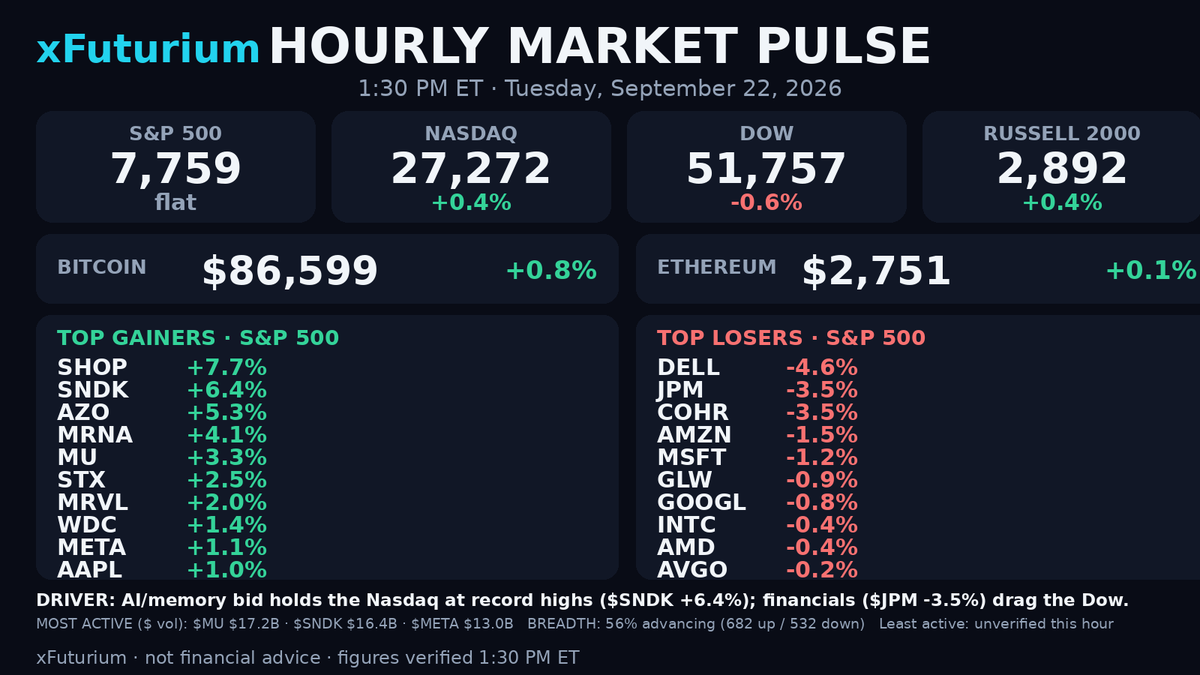
The Nasdaq Composite rose 0.5% to ~27,222 — its second straight record close. The S&P 500 finished essentially flat at ~7,767. The Dow fell 185 points, 0.4%, to 51,864 as financial shares sagged. The 10-year Treasury yield sat at ~4.97%, Brent crude slid 1.1% back below $100 to $99.25, and Bitcoin held near $86.6K. The day's character: the AI bid rotated down the stack — megacaps fell while memory and the chip supply chain carried the tape, and the whole market held its breath for Thursday's Trump–Xi meeting.
THE WINNERS
$SNDK — Sandisk ripped 6.9% to $1,888.91, one of the S&P 500's top gainers, after Rosenblatt initiated coverage with a Buy and a $2,400 price target. The stock is up nearly 700% this year on the memory supercycle — DRAM prices are up 4.4x in a year, NAND 9x, and every AI build is a storage build.
$SHOP — Shopify jumped 7.5% after CEO Tobi Lütke said the company is "partnering deeply with Muse" to enable agentic checkout with Shop Pay on all Shopify stores. Users will find products from Shopify merchants and buy through Shop Pay inside the Muse experience. This is the Meta × Shopify integration in the flesh — platform-scale distribution for agentic commerce.
$MU — Micron added to Monday's gains, finishing among the day's top S&P 500 names with Sandisk. The Roundhill Memory ETF closed ~3.5% higher and the SOXX ~2.5%. Memory is doing the heavy lifting into Micron's own Q4 report next week.
$LEN — Lennar rose 5.6% after Berkshire Hathaway bought over $200M of its Class A shares across three trading days and now owns just over 10% of the country's second-largest homebuilder. When Berkshire builds a double-digit stake, housing investors listen.
$BABA — Alibaba rose 0.6% on substance: it unveiled the Zhenwu V900, its most powerful AI chip at 3x the performance of its predecessor, and launched Qwen3.8-Max, its largest AI model release yet. China's AI stack is shipping its own silicon story.
$VICR — Vicor surged ~13% after raising its sequential Q3 growth guide from ~10% to over 20% on non-exclusive patent-license royalties. A patent, not a product, moved the stock — the cleanest kind of margin expansion in power electronics.
THE LOSERS
$SCHW — Charles Schwab fell 5.7%, one of the S&P's worst names today, as Meta's Muse agent spooked the brokerage complex. Wall Street is starting to price in what a #1-ranked AI agent means for trading engagement and advisory fees. LPL and Allstate fell with it.
$JPM — JPMorgan dropped 3.5% on no real news — the read-through is the Treasury curve, which has flattened dramatically since the Iran war started, squeezing bank profit margins. Amex and Visa ranked among the Dow's biggest decliners too.
$META — Meta gave back 0.6% after Monday's 11.4% moonshot — textbook cooling, and the Magnificent Seven ETF fell 0.5% alongside it. The tape rotates; the Muse moment isn't over, with Meta Connect keynoting tomorrow.
$DELL — Dell slid 4.6% to ~$549 with no confirmed catalyst this run — rotation out of AI-server names after Monday's memory-led rally, and likely profit-taking on a 336% YTD run.
$COHR — Coherent fell 3.4%, handing back some of the photon layer's gains. And enterprise software stayed in the penalty box: $ADBE, $CRM, $NOW, $WDAY all finished red while the memory layer printed.
SECTOR SCORECARD
Leaders: memory/storage and semiconductors — the DRAM ETF +3.5%, SOXX +2.5%, with Lumentum, Marvell, Seagate, Corning and Western Digital all advancing. Laggards: financials — brokers hammered on the Muse scare, big banks sagged on the flat curve, and refiners fell on Jefferies cuts. The cross-sector read-through of the day: the AI trade is rotating down the stack. Megacap software fell while the physical layer — memory, power, photons — re-rated. And watch the flattening yield curve since the Iran war: it's quietly becoming the macro signal on this tape, with banks as the pressure valve and AI hardware as the relief valve.
THE STORY OF THE DAY
The record ran down the stack. Tuesday's second straight Nasdaq record close did not come from the logos — the Magnificent Seven finished 0.6% lower. It came from memory: $SNDK +6.9% on a fresh Rosenblatt Buy, $MU among the day's top gainers, the memory ETF up ~3.5%. This is the AI buildout going physical — the shortage trade moving from GPUs to the storage and components underneath them. Meanwhile the rest of the market is positioning for Thursday: Trump meets Xi in Washington, with AI policy, tariff rates, rare earths, and the Iran war on the agenda. The quiet tape is a held breath — one meeting, and every name in the supply chain reprices.
EARNINGS
$AZO — AutoZone reported Q4 before the open: EPS beat Wall Street's estimates, lifting the stock 6% — but sales and same-store sales both missed consensus, so the beat has an asterisk. After the close: $KBH — KB Home reported Q3 with ~$0.89 EPS on ~$1.3B revenue expected; and $WOR — Worthington Enterprises reported FQ1, with the conference call Wednesday at 8:30 AM ET.
FLOW
$GME — CEO Ryan Cohen bought 1.15M more GameStop shares, disclosed in a Form 4 filing, and the stock rose 5%. Cohen keeps buying when the tape doubts — the whale move is the headline. $LEN — Berkshire Hathaway's $200M+, three-day build to a 10%+ stake in Lennar is the day's most meaningful institutional accumulation, disclosed and done at the open market.
TOMORROW'S SETUP
Meta Connect keynotes tomorrow — Muse sits at #1 in the App Store, so expect the agentic-commerce push to go prime time. General Mills and Cintas report Wednesday — watch consumer-staples demand and the uniform/jobs bellwether read. Thursday is the main event: Trump–Xi in Washington — AI, tariffs, rare earths — plus Costco and Darden earnings after the close. Friday the calendar thins; expect a position-light tape into the weekend.
WALL STREET IS THE GREATEST SHOW ON EARTH.
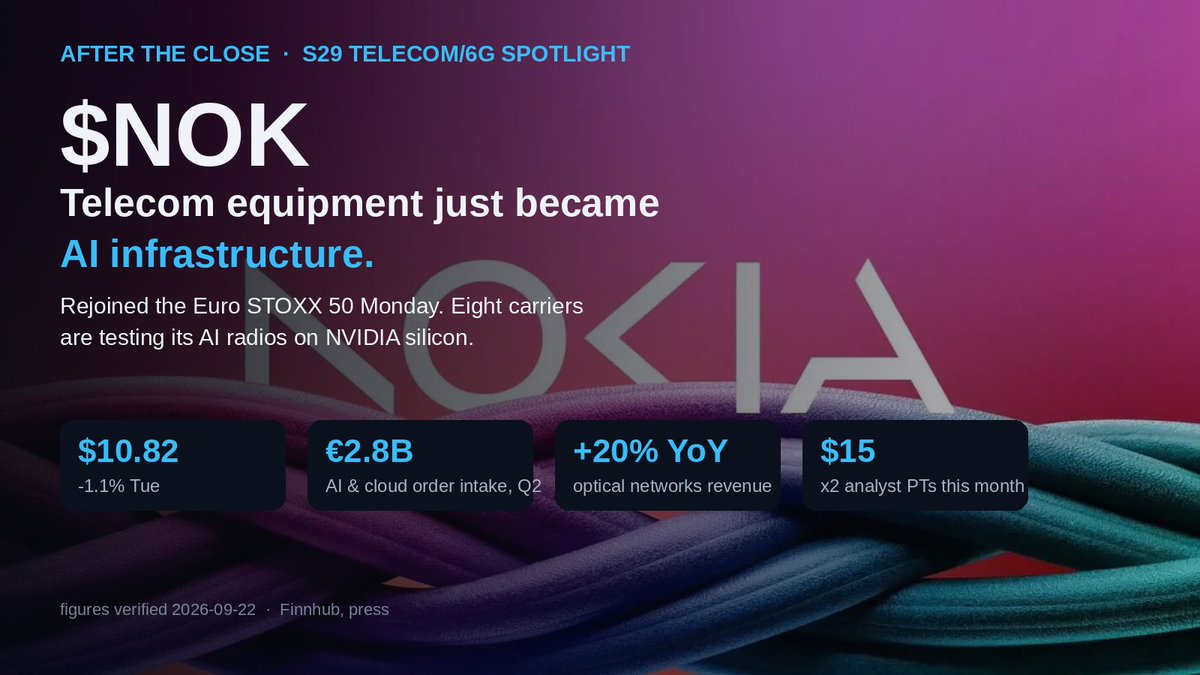
$NOK just rejoined the Euro STOXX 50 — and Wall Street is suddenly valuing a telecom equipment maker like AI infrastructure. NVIDIA put $1B in. Eight carriers are testing its AI radios. Here's the re-rating nobody's writing about.
Monday, Nokia returned to the Euro STOXX 50, replacing Volkswagen's preferred shares. The index add is mechanical — passive funds had to buy — but the timing is the story: it landed in the middle of the best fundamental week Nokia has had in years. Shares closed Monday at $10.94, up 2.4% on 83 million shares.
Wall Street noticed. Rosenblatt initiated with a Buy and a $15 target, calling Nokia's Network Infrastructure division "quietly emerging as one of the most strategically positioned optical players in the AI expansion." B. Riley followed two days later: Buy, $15. Consensus is now Moderate Buy with an average target around $14 — roughly 30% above Tuesday's $10.82 close. Northland is at $20, JPMorgan overweight with a $21 target.
Why the re-rating is real — and what Nokia actually is:
Nokia runs four businesses. Mobile Networks (carrier radio gear), Network Infrastructure (fixed-line, switching and routing, optical components, fiber-to-the-premises), Cloud & Network Services (core software, private enterprise networks), and Technologies — the patent-licensing arm monetizing decades of Bell Labs R&D against handset makers and IoT vendors. About 78,000 employees out of Espoo, Finland, led by CEO Justin Hotard.
The AI angle runs through two products:
1. AI-RAN. Nokia's AI-native radio platform runs on NVIDIA's Aerial RAN Computer. NVIDIA didn't just partner — it bought in: $1B for 166 million new shares at $6.01 last November, about a 3% stake. This month Nokia disclosed that eight operators — A1 Group, Chunghwa, du, e&, Mobily, stc, TPG Telecom, Zain Saudi — moved from evaluation to lab and live field trials, with earlier work at T-Mobile, SoftBank, and NTT DOCOMO continuing. The platform claims 20%+ spectral-efficiency gains. Trials aren't contracts — the next milestone is a paid deployment with disclosed economics — but the funnel is real and multi-continental.
2. Optical. Optical Networks grew revenue 20% year over year in Q2. AI & Cloud order intake hit €2.8B in the quarter — about half expected to convert to revenue within a year — and AI/cloud revenue more than doubled. In Q1, AI & cloud sales were up 49%, already ~8% of total revenue, with €1B of firm orders and 12-to-18-month lead times. This is the picks-and-shovels story: hyperscalers connecting datacenters run coherent optical gear and IP routing, and Nokia is one of the few non-Chinese suppliers at scale. The 800G deployment deal with Telxius across Europe, the US, and Latin America is the proof point.
The read-through — the same "network for AI" thesis, two ways:
$NOK is the re-rating: clean balance sheet, ~$52B market cap, up 67% this year, trading like an AI infrastructure name.
$LUMN is the cautionary version of the same idea. CEO Kate Johnson pitches Lumen as "the trusted network for AI" — fiber for datacenter interconnect — and the strategic-growth segment is now over 60% of enterprise revenue. But the stock sits at $6.38, down ~9% this week, under a ~$20B debt pile with creditors negotiating a restructuring extension into January. Same thesis, opposite capital structure. Watch which one the market rewards.
And $ANET — the datacenter side of the same bandwidth story — is where the fabric dollars land when AI clusters scale. The bandwidth trade has three doors: radios ($NOK), fiber backbones ($LUMN, if it survives its balance sheet), and datacenter fabric ($ANET).
The 6G clock is ticking too: China Mobile and Qualcomm just completed the first U6G-band 6G prototype connection under the latest 3GPP definition, and Nokia sits in NVIDIA's coalition of carriers and vendors committed to building 6G on AI-native platforms. Nokia Defense's MOU with C3IA for UK Ministry of Defence digital transformation adds the sovereign angle.
The setup into October 22 earnings: Q2 was an EPS beat ($0.08 vs $0.06) with a revenue miss ($5.51B vs $5.59B) — the market is weighing order visibility over headline revenue. If AI/cloud intake stays at a €2B+ pace, the $14 average target starts looking conservative.
Close context: the Nasdaq notched its second straight record close (+0.5%) while the S&P 500 went flat near 7,767 and the Dow fell 185 points on bank weakness — Charles Schwab dropped 5.3% as Meta's Muse AI agent spooked the advisory business. Brent fell below $100 ($99.25). The 10-year sits at 4.966%.
Which side of the telecom trade are you on: the AI re-rating ($NOK) or the distressed fiber turnaround ($LUMN)? Reply with your pick and your why.
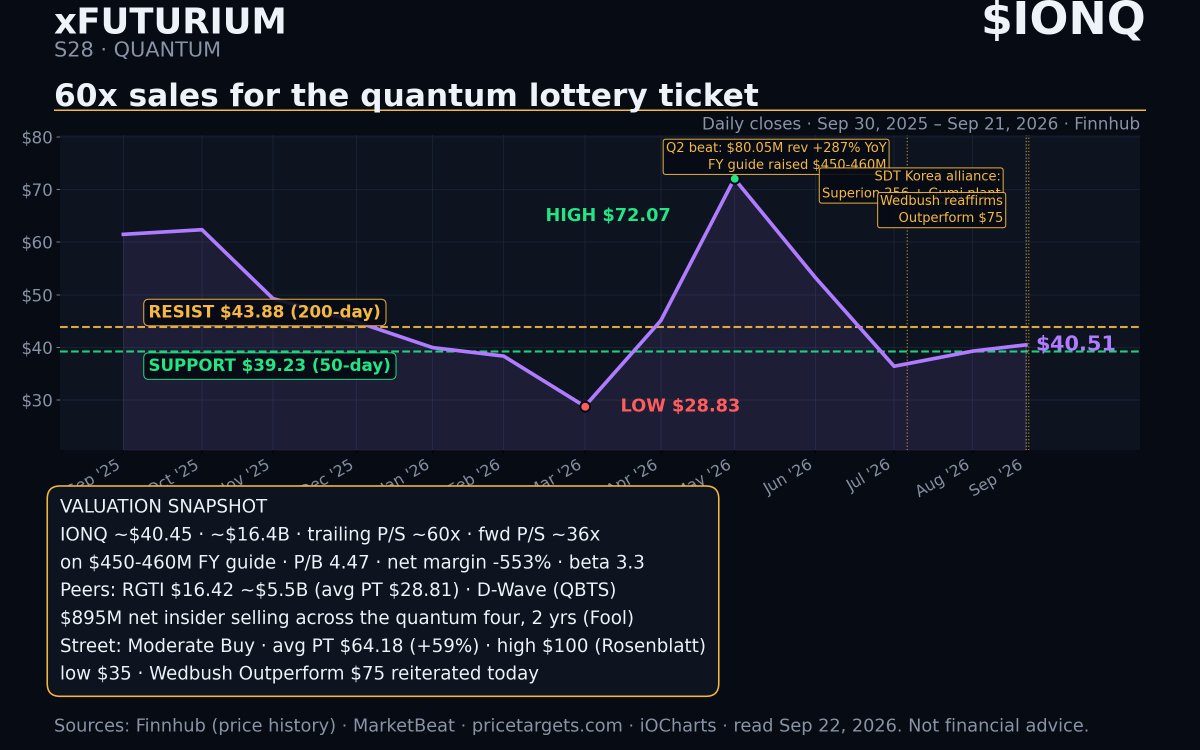
$IONQ is a $16B quantum company trading at ~60x sales — and Wall Street still sees 60% upside from here. Overvalued, undervalued, or fairly valued? I ran the numbers.
THE COMPANY
IonQ builds trapped-ion quantum computers (College Park, Maryland) — ions held in electromagnetic fields instead of superconducting circuits, which gives all-to-all qubit connectivity and higher fidelity. It's the most commercially advanced of the pure-play quantum names.
Revenue is finally real. Q2 (Aug 5): $80.05M vs $66.47M expected, up 286.7% YoY, EPS loss of ($0.33) vs ($0.56) expected — and management raised full-year 2026 guidance to $450–460M. Honest caveat: a big slice of that guidance rides on the acquired SkyWater semiconductor foundry business, not pure quantum. The "quantum revenue" story is smaller than the headline.
The platforms: Forte Enterprise (EPB has one deployed commercially), Tempo (QuantumBasel paid $60M for the next-gen system), and Superion 256 — 256 qubits, demo targeted Q4 2026, commercial delivery early 2027. That milestone is what the entire valuation hinges on.
Quantum networking is the sleeper: $54.5M Air Force Research Lab contract, and yesterday's SDT deal ships IonQ's silicon-vacancy quantum memory module. The company just hired ex-IBM executive Charles Robinson as its first public-sector quantum security chief — a tell on where they think the real money is: government contracts.
THE NEWS
Monday, IonQ signed a multi-year alliance with South Korea's SDT: a Superion 256 system plus the SiV quantum memory module, SDT building a dedicated manufacturing and integration plant in Gumi, South Korea, a hybrid quantum-classical data center, and collaboration with a local cancer center on biomedical research. The stock rose 3.3% Monday to $40.42, then ticked up another 0.5% after hours.
The validation pile keeps growing: IonQ + Synopsys embedded quantum algorithms into Ansys LS-DYNA and ran automotive and jet-engine simulations up to 14.6% faster. IonQ + NVIDIA + Oak Ridge used generative AI to cut quantum-circuit compilation from 11 minutes to 28 seconds. Washington is lining up ~$2B for quantum chips under CHIPS. And TODAY, Wedbush reaffirmed Outperform with a $75 target.
THE MATH
~$40.45. ~$16.4B market cap. Trailing P/S ~60x is steep; forward P/S ~36x on the guidance midpoint is the number that matters. P/E is meaningless (EPS -$1.82 TTM, consensus -$2.11 this year), P/B 4.47, net margin -553%, beta 3.3 — a lottery ticket with revenue, not an investment with earnings.
Technically the stock is wedged: 50-day at $39.23 is support, 200-day at $43.88 is resistance. RSI is back over 50 (bullish), but the chart sits near horizontal resistance. It's down 46% over the past year and 52% below its $84.64 high — the air has already come out.
The skeptic file: $895M in net insider selling across the four pure-play quantum names over two years — $454M of it at IonQ alone — vs barely $2M in insider buying (Motley Fool, today). Executives get paid in stock and pay taxes in stock, so it's not a conviction signal by itself. But it's a real data point, and it caps the multiple the market will pay.
The Street: Moderate Buy, average target $64.18 (+59%), high $100 (Rosenblatt), low $35 — 9 buys, 4 holds, 1 sell. One published framework puts bull at $75, bear at $22.
VERDICT: FAIRLY VALUED.
60x trailing sales is pricing in the Superion 256 delivery and the Q4 demo — execution risk is genuine. But the stock is 52% off its high, the skepticism is priced in, guidance was raised, and consensus still sees +59%. That's the fair price for a binary ticket.
OUTLOOK: sideways-to-higher into Q3 earnings on Nov 11. Base case: the $39–$44 band (50-day support vs 200-day resistance). Bull case: the Superion 256 Q4 demo lands clean and $60–75 (street high) comes into view. Bear case: the demo slips or the guidance turns out to be mostly SkyWater — then the $25.89 52-week low is back in play.
CONNECT THE DOTS: $RGTI, $QBTS and $QUBT ride the same sympathy bid. $SNPS validated the simulation angle. $NVDA co-developed the compilation breakthrough. The CHIPS quantum money favors foundry-adjacent names. And if quantum ever cracks encryption — the "Q-Day" thesis some analysts pencil in for 2028 — then $CRWD and $PANW are the other side of the trade.
The quantum lottery ticket: $IONQ at $40, $RGTI at $16 — or is the whole sector still too early to touch? Reply with your pick and why.
$RKLB just put on ~11% in two days. One bank is effectively running the space book — Cantor Fitzgerald reaffirmed Outperform with a $122 price target Monday, and the stock ripped 8.2% to $69.89. Today it's tacking on another ~3% to ~$72.
But the analyst note isn't the event this week. THURSDAY is.
Sept 24: Iridium shareholders vote on Rocket Lab's $8B acquisition of Iridium. This is the deal that would transform Rocket Lab from a launch company into a full-stack space platform — and management has already raised the cash half: $1.9B of new stock sold over the last month at ~$66.
The dilution math, per the Fool: Iridium shareholders also get 0.24–0.40 RKLB shares per Iridium share at close (expected mid-2027, pending regulatory clearances). All in, the deal adds ~72M shares — ~12% above the Aug-5 share count. Selling stock at $66 beats owing $3.6B that would come due within a year of closing; for a still-lossmaking company, the balance-sheet trade is defensible.
What Rocket Lab is buying: Iridium is forecast at ~$884M in annual revenue, >$135M in GAAP profit and >$313M in positive free cash flow in 2027 — roughly doubling Rocket Lab's revenue and flipping the combined company profitable. That's what Cantor's thesis survives on.
Meanwhile the actual business keeps printing. Saturday was Electron's 96th launch — a StriX satellite for Japan's Synspective, mission #17 of 2026. Q2 revenue was a record $234M (+62% YoY), Q3 guidance is $250–265M, ~$2.4B in cash sat on the balance sheet at quarter-end, and a $397M Space Force contract landed in August. The honest read: the rocket works, the money is real, the backlog is growing.
The other side of the ledger: Neutron. Rocket Lab now says the first-stage tank reaches the pad in Q4 2026 — but no launch date is set, and a 2027 debut is squarely on the table. That's the latest in a string of slips since the 2024 target. Archimedes has 400+ hot-fire tests, and the first commercial booking (Kepler, NET 2028 from Wallops) is signed — but the ~$50–55M-per-mission, 13-ton reusable workhorse is still unflown. And the stock, at ~$42B, trades at >40x annualized revenue, still ~52% below its $151 May high. The honest take: smart financing, but not a cheap stock.
The read-through for the rest of the space sector: the SAME Cantor analyst (Andres Sheppard) doubled down on Intuitive Machines Monday — Overweight, $32 target — and $LUNR popped 12.56% on it: SXM-11 was just handed to SiriusXM, and the $800M Lanteris buy has made IM Sirius's largest satellite supplier. $ASTS is +5.5% today at ~$65 (~$24B). The whole group is still trading the SpaceX-IPO-contagion premium from May; the Blue Origin explosion and NASA's $4.6B LTV snub are why these names are 50%+ off their highs.
Thursday's Iridium vote is the closest thing this sector has to a binary event this week. Which space name are you holding into year-end — $RKLB post-Iridium, $ASTS, $LUNR, or $RDW? Drop it below.
$JOBY just flew 3,199 miles across America with ZERO pilot inputs. $ACHR just became the company Boeing is betting its flying future on. Two completely different bets now — so why is the further-along one down 62% in a year while the other is down 44%?
Let's do the honest breakdown, because the air-taxi race just split in two.
THE WEEK THAT WAS — $JOBY, THE AUTONOMY PLAY
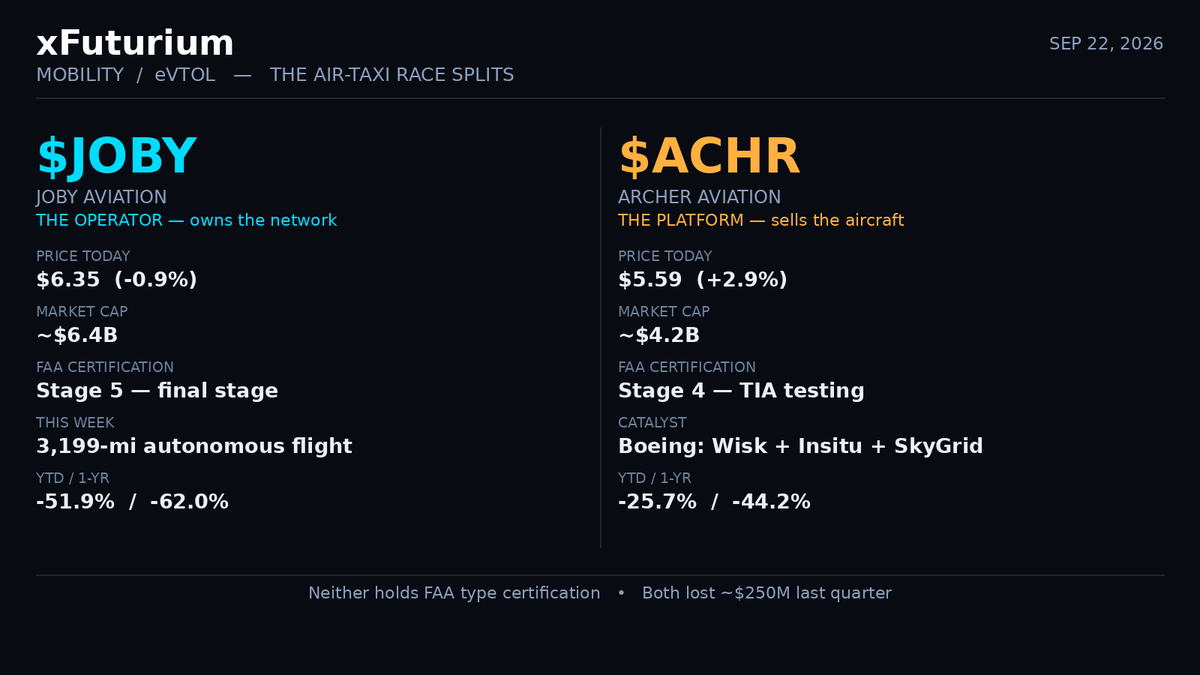
On Thursday, Joby flew a converted Cessna Caravan (its J208 autonomy testbed) 3,199 miles from California to Kitty Hawk, North Carolina — with zero control inputs from the onboard safety pilot. Taxi, takeoff, navigation, landing: all autonomous. It integrated into Phoenix Deer Valley, one of the busiest general-aviation airports in the country, and rerouted around severe weather in real time. Remote supervision came from up to 2,323 miles away.
The autonomy stack has now logged 400+ flights and 800 automated hours. And Joby isn't doing victory laps — it's on tour. This week it starts a week-long series of White House-backed eVTOL Integration Pilot Program flights in Dallas–Fort Worth (it's leasing a 45,000 sq ft facility there for a long-term presence), then sends the autonomous J208 on a month-long US tour: FAA, UPS Worldport, DoD bases, state DOTs.
Read that customer list again. Freight, medical logistics, disaster response, defense — missions that pay BEFORE the FAA certifies a passenger air taxi. The autonomy stack is Joby's second product, and it doesn't need a type certificate to earn.
The stock's reaction tells you everything about this market: $JOBY initially jumped on the news, then reversed negative as traders took profits. Today: $6.35 (-0.9%), ~$6.4B market cap, -51.9% YTD, -62% over the last year. Oh — and CEO JoeBen Bevirt sold 606,667 shares (~$3.76M) Tuesday under a pre-arranged trading plan. He still holds ~89.5M shares, but a separate Form 144 filing signals more insider liquidity coming. Worth watching, not worth panicking over — yet.
THE OTHER BET — $ACHR, THE PLATFORM
Archer stopped being a pure air-taxi story on August 10. That's when Boeing agreed to hand Archer its advanced-air-mobility portfolio — Wisk Aero (autonomous flight), Insitu (military drones), and SkyGrid (airspace management) — for a ~19.75% equity stake plus warrants and a board seat. Expected to close by end of 2026, pending regulatory approval.
What Archer actually bought: Insitu is a profitable defense business doing $200M+ in annual revenue — ISR drones, 3,500+ systems fielded, 35 countries. Wisk brings 16 years of autonomous eVTOL work: six aircraft generations, 1,700+ test flights. SkyGrid brings the digital air-traffic layer. Add the Anduril partnership (Halo and Thunder hybrid platforms for defense), and Archer's CEO isn't exaggerating when he calls it an inflection point: it's now a diversified platform across air taxis, drones, and AI — not a single-product startup.
The numbers today: $5.59 (+2.9%), ~$4.2B market cap, -25.7% YTD, -44.2% over the last year. Q2: $5.0M revenue — up 213% quarter over quarter, mostly Hawthorne Airport ops — against a $263.2M net loss. Cash: ~$1.56B. Quarterly spend runs ~$170–200M, so that $200M/yr Insitu revenue stream (post-close) doesn't erase the burn, but it buys something pre-revenue startups almost never get: time.
THE CERTIFICATION SCOREBOARD
This is still the only moat that matters, so let's be precise. Joby is in the fifth and final stage of FAA type certification — the only eVTOL developer flying a production-conforming aircraft, the machine government test pilots fly "for credit." It already holds the Part 135 air carrier certificate: the operating authority to carry passengers for compensation. Archer closed phase 3 in May and is in phase 4 TIA flight testing — a full gate behind on flown test time.
Neither company holds a type certificate yet. Anyone who tells you otherwise is selling something.
THE MACHINES
Joby's S4: six tilt rotors, pilot + 4 passengers, ~200 mph, 150-mile range. The tilt-rotor layout is faster and more energy-efficient than lift+cruise — and ~22 decibels quieter than a helicopter, which in dense cities isn't an engineering footnote, it's the permit to operate.
Archer's Midnight: 12 propellers (6 tilting), pilot + 4, ~150 mph, ~100-mile range — optimized for 20-mile back-to-back hops with ~10-minute charges. That's the actual air-taxi mission: short hops, fast turns.
THE MONEY QUESTION
Strip out the cash: Joby's operating business is valued near $4.8B, Archer's near $2.8B — roughly a $2B premium for being one gate ahead and owning the network instead of selling the airplane. On this year's sales estimates, Joby trades ~51x, Archer ~278x.
Both lost ~$250M last quarter ($245M Joby, $263.2M Archer) with zero revenue from the product they were built to sell. The market's verdict so far: Joby's lead is real but already in the price — and its operator model is more capital-hungry than Archer's OEM-turned-platform model, so it gets punished harder in a market repricing capital intensity.
But here's the tension the market hasn't resolved: Archer's new model NEEDS Joby to prove the concept. Somebody has to certify the air-taxi mission first, build the vertiport economics, and show passengers will board. Every gate Joby clears de-risks Archer's Midnight. They're competitors the way the railroad and the telegraph were competitors — the infrastructure one builds is the market the other sells into.
THE CATALYST WINDOW
Both companies are targeting first US flights under the White House's eVTOL Integration Pilot Program — and a Presidential executive order directs the DOT and FAA to let mature eVTOL aircraft begin operations in select markets as early as next year, ahead of full FAA certification. Joby's DFW flight series this week is the opening act. First passengers are targeted for later this year across 10 states. That's the window both stocks are really trading on — not 2030.
And the noise to ignore: Tesla's "flying Roadster" headlines shaved 4–5% off both stocks last month. It's a limited-edition stunt car with cold-gas thrusters — not street legal, not an air taxi, not a competitor. File under: Elon volatility, not industry signal.
THE REST OF S26: $UBER (the network Joby plugs into — it bought Uber Elevate in 2020), $BA (Boeing now owns a fifth of Archer — legacy aerospace money flowing downstream), $MBLY and $PONY (the autonomy endgame: self-flying is what makes the unit economics work), $AUR, $APTV, $LEA.
My read: Joby holds the best hand — final certification stage, Part 135 in hand, a revenue bridge from Blade and defense, $2.3B in cash, a six-year exclusive Dubai deal, 2026 revenue guided to $115–125M, and now a real autonomy product. Archer holds the better STRUCTURE — defense revenue incoming, Boeing's balance-sheet halo, four shots on goal instead of one. The market has the pricing backwards and the question right: you're not buying airplanes. You're buying the right to lose money until the FAA says go.
Two bets, one sky. Which one are you holding into 2027 — the operator proving autonomy, or the Boeing-backed platform? Drop your pick and your why below.
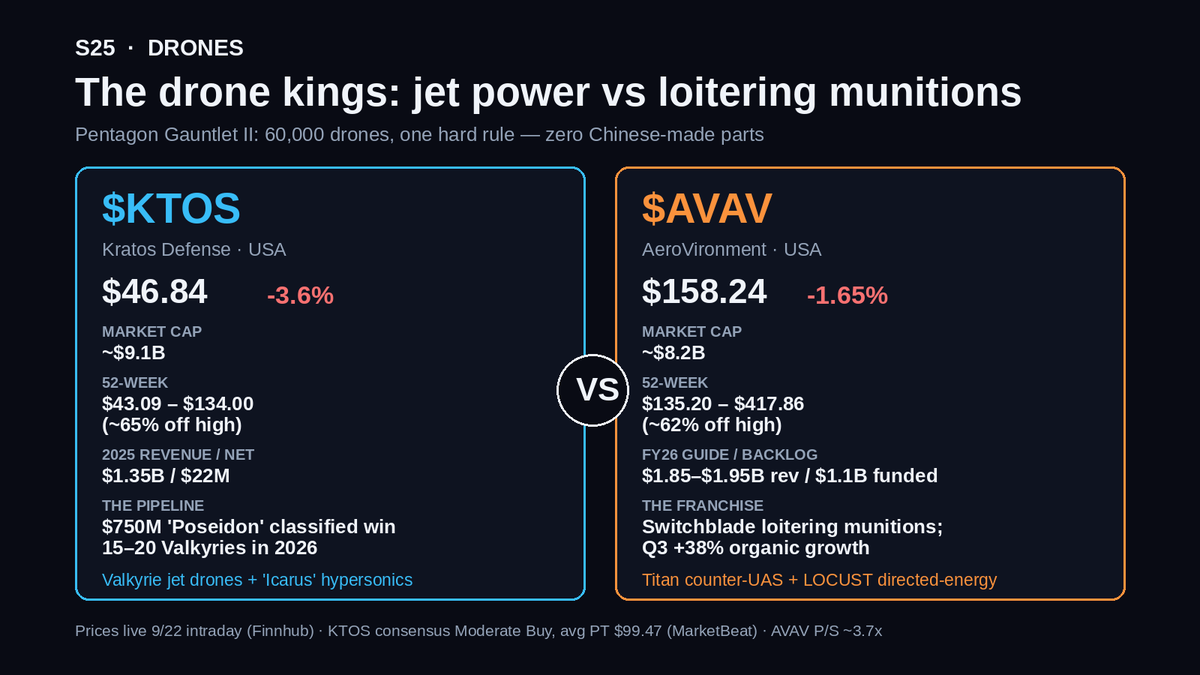
$KTOS vs $AVAV — the two kings of the Pentagon drone trade. Last week the Pentagon picked winners for 60,000 drones. Both stocks are 60%+ off their highs. Here's the honest breakdown.
9) My take: the Pentagon just told you where 60,000 drones are going — with a no-China-parts rule that hands the supply chain to domestic names. AVAV has the proven volume product and the cheaper multiple. KTOS has the wilder upside if Valkyrie becomes a program of record. The drawdowns are the real question: is Gauntlet II the first drip of a genuine order flood, or a headline that dies in appropriations? Drop your pick below.