Space | Energy | Defense | AI | Quantum | Finance |
Posts are for education & discussion, never investment advice.
The market pays me, I share everything freely
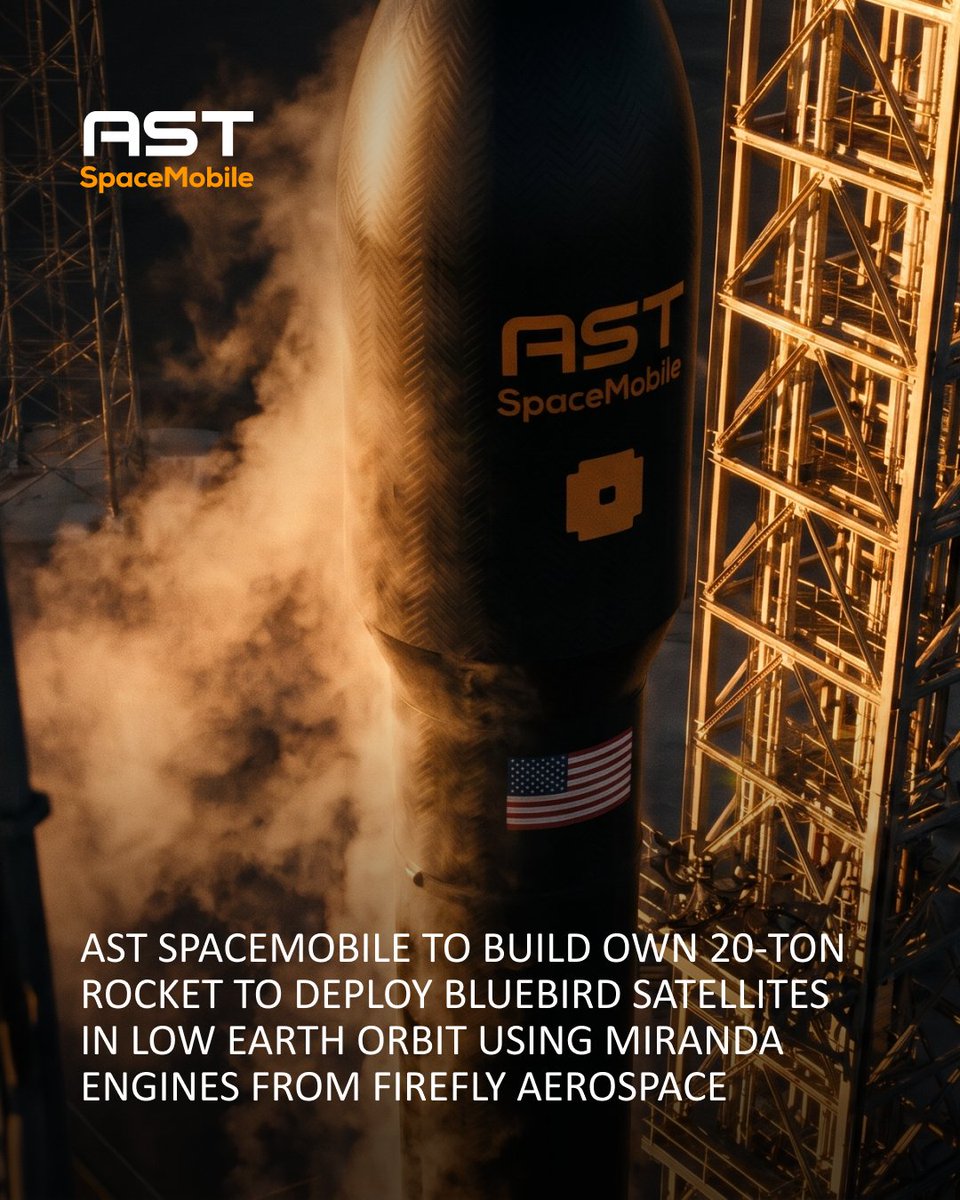
I guess I should have said "they cant completely rely on others". They will certainly be relying on Firefly for arguably the most complex component. But anyone who has reliable launch is going to hoard it mostly for themselves. I dont think anyone was willing to give $ASTS tons of guaranteed launch.
Lots of other companies are hoping to use $FLY in the future including NASA, the Space Force, the Space Development Agency, the National Reconnaissance Office, Northrop, Lockheed Martin, L3Harris and True Anomaly.
Pretty wild. The balls on these guys...
They must think manufacturing, the tech, and getting the sats up for full service is completely sorted out.
On one hand they don't have a choice. The whole vision is at the mercy of launch. It appears they can't rely on others.
If $ASTS ultimately wants a 700+ satellite constellation with an average 7-year lifespan, that would require 100 replacement satellites per year. At 5 sats per launch, that's 20 launches a year, or nearly 2 every month, just to keep the constellation from falling apart. Can you imagine spending years of blood, sweat, and tears building this out and then having it constantly at risk of falling apart?
The Blacklift website names radar and sensing among future markets. For those, US-built and US-launched hardware is likely essential. A lot of the planned multi-billion revenue streams likely need dedicated/reliable launch.
So I don't think they have a choice. You can't do space things at scale without reliable access to space. If they couldn't find a reliable partner then they simply had no choice.
My main concern is timing. Adding enormous risk at this stage is rough. Ideally they would have started service by now and been printing money before embarking on this perilous journey. That's probably what they expected and hoped for, but alas, it didn't pan out.
Plus I'm not a big fan of Firefly. Three successful Alpha launches since 2021 is not confidence-inspiring. Hopefully the engines/rocket they're building with Northrop Grumman pan out next year as the test case.
That late 2028 timeline is also bizarre to throw out there. Why do that with all the recent timeline issues? Why risk credibility further like that?
A lot to think about. I'll need to mull this over and see how it affects my future plans and thesis.
Let's see what they say during their conference call but I had been saying that owning less $ASTS during this period was likely the sanity/soul preserving move. Certainly reasonable to wait until launches get rolling again. The temptation was the severely depressed price, but now it will be interesting to see how the market digests this news while the rest of the sector recovers.
Launch was never a commodity. That argument was always dumb. Launch is an essential necessary evil.
My hope was that between $SPCX, Blue Origin, and $RKLB they would throw enough money around to get reliable launch setup. Turns out that reliable launch is so precious/limited that even lots of money isn't enough. Maybe that is thesis breaking in and of itself for $ASTS. It is certainly core to the vision/thesis of $RKLB.
@BlackScholesMan "100 sats in orbit in 27/28 on existing field of providers". Yea I don't expect this to occur. My hope is $ASTS gets to 45 by end of 2027. Current rate is 0.69 sats a month.
Today's data is incredible. Will probably outdo the Covid crash once the dust settles. ~10 Leopolds, apparently including Leopold himself again.
$NBIS hit $113... a ~$30B market cap (~$24B ex-investments).
All for what?
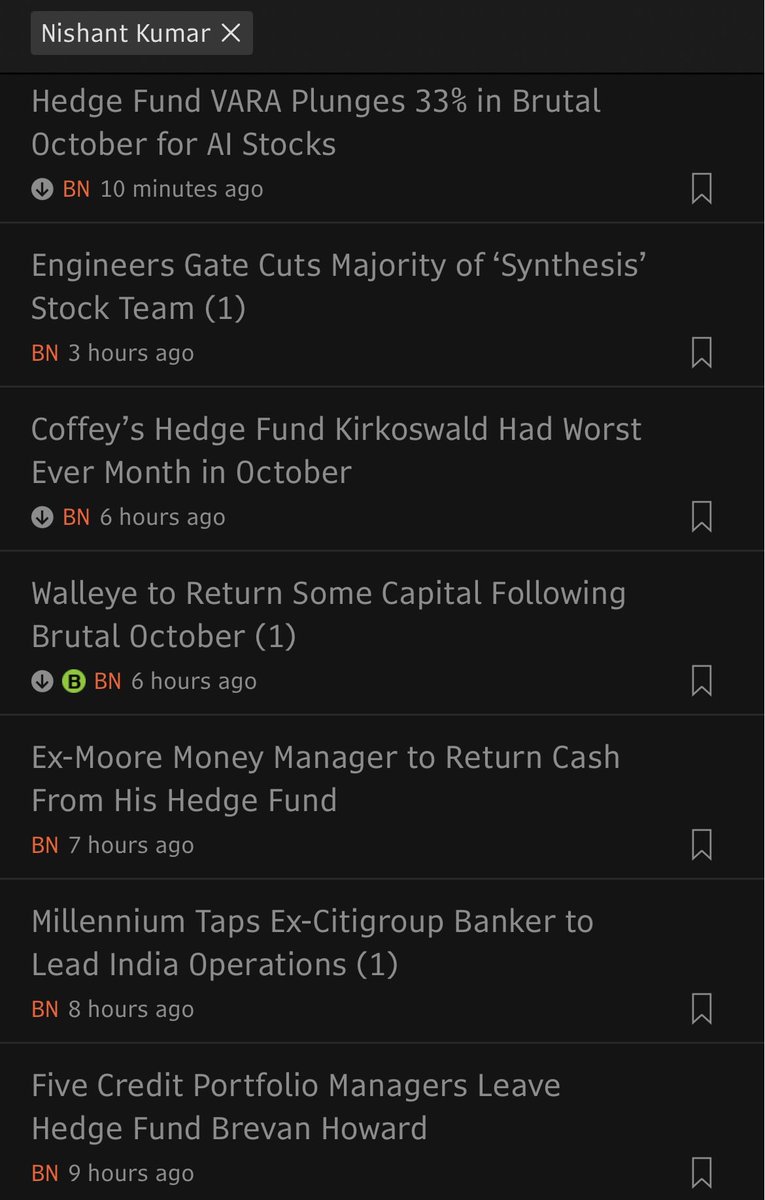
Hedge funds have been a total manic clown show this year.
I'm not trying to be flippant. But we had a historic climactic drop with an incredible amount of forced selling and liquidations. So yes, I'm going to take a shot here. I don't have a crystal ball, but I'd rather be in the habit of selling into euphoria and buying into despair.
Pretty remarkable what's happening. No special guidance from me, and I'm not the best person to listen to given I started buying too early (I guess buying things already down 40-60% was too early 😬). Still adding gradually, including today. Big hit, but emotionally I'm unfazed.
Pretty remarkable what's happening. No special guidance from me, and I'm not the best person to listen to given I started buying too early (I guess buying things already down 40-60% was too early 😬). Still adding gradually, including today. Big hit, but emotionally I'm unfazed.
Likely a combination of:
-He's unlikely to hit his numbers (10-13 GW by end of 2027 vs ~1.4 GW rated in Memphis/Southaven today).
-There's only so much power in Memphis.
-Demand will still outstrip supply. Elon even says he could sell his capacity several times over.
-Many companies & countries won't want to depend on Elon or have all their compute in one place.
-Europe needs local data centers and $NBIS is a natural fit.
-NBIS offers more than just bare compute. They offer things like specialized token efficiency and deployment/development tools.
-NBIS only needs a small slice of the market to pay off from a ~$40B market cap (with a true market cap that is even lower if you stripped out ClickHouse, Toloka, Avride, TripleTen and its other investments.)
etc.
I added a bit more today during the carnage, including $NBIS.
One comment that stuck out to me was $AMZN's CEO mentioning that in the future a big chunk of all compute (20%) may need to be constantly deployed just for cybersecurity. That number is tiny today, and we're already compute constrained. Imagine what happens when every major company/bank desperately needs constant dedicated compute for cyber defense and vigilance.
@JakobL7ap This market is a bit too wild right now for me to go that far out on the risk curve when $NBIS is already pretty beaten up. For $SHAZ the angle of interest for me would be the data sovereignty angle which will be an interesting niche in the future if $SHAZ survives.
This wasn't $NBIS. Their Q2 letter (Aug 12): "To date, we've delivered all capacity tranches to Microsoft under the contract, including two tranches over the past month."
Probably $IREN or Nscale.
That delay caused the $MSFT's capex miss & CY outlook cut (~$175B to $170B).
Microsoft said that "some third-party GPU-as-a-service contracts have been delayed to the second half" of FY27, so calendar quarters Q1 and Q2 2027..
I wonder which "neocloud" contracted to deliver capacity to Microsoft in Q4-26 is running behind schedule..
@L4gcy These are definitely potential options that still need to be executed. The backup financing is likely to come with significant dilution. I do agree though that the setup looks asymmetric.
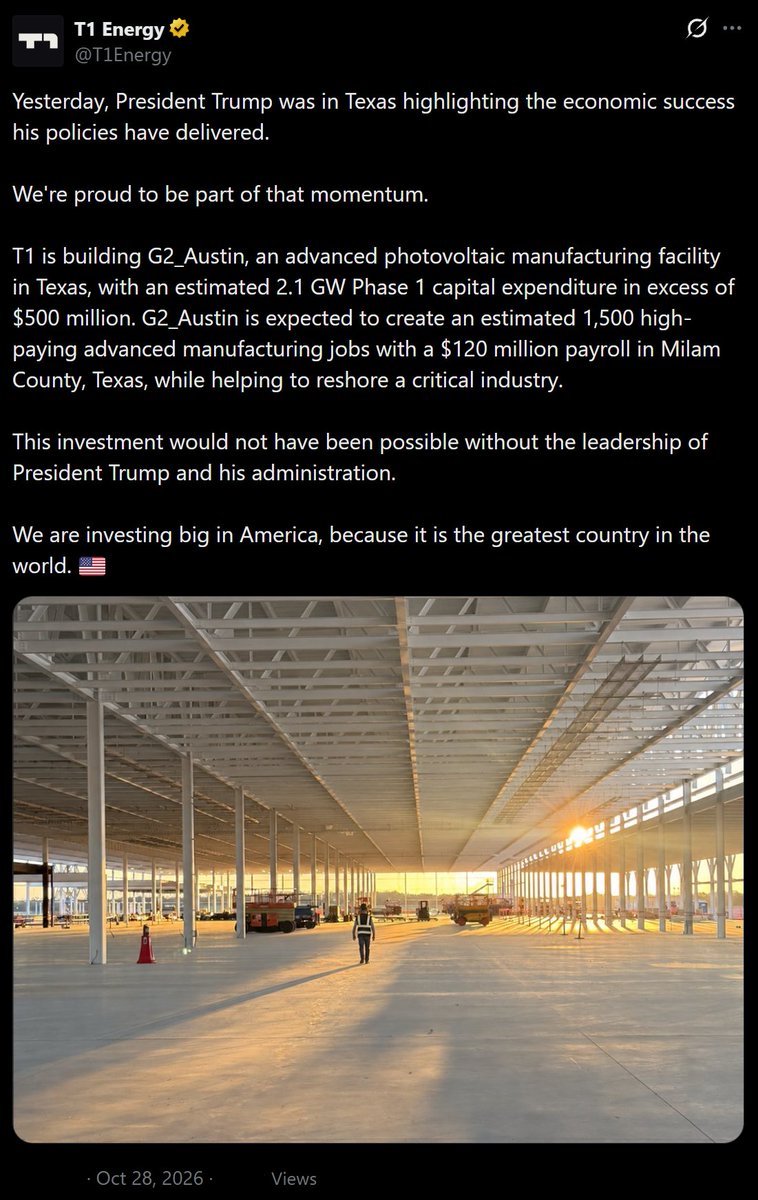
Continued signs of life for $TE.
Not risk-free, but the price got very interesting.
Without funding, $TE likely goes bankrupt & gets sold for parts, or dilutes to zero & reverse splits. Funding has gotten tougher. Downside risk is still significant.
If they get funding...
Took a shot at positioning again in $TE here at ~$2. This is a binary, high-risk bet that leadership isn't going to run two massive solar factories and a first-of-its-kind domestic supply chain into the ground any more than they already have.
Sized accordingly.
$MSFT said much the same, plus the dip in capex spending vs expected was from a delay in a third-party delivery.
This market is just full of gerbil energy.
GOOGLE:
- NO CHANGE TO OUR 2026 CAPEX GUIDE OF $205B
- WE EXPECT TO SIGNIFICANTLY INCREASE CAPEX IN 2027
- Missed on EPS & Revenue, stock is down 10% for the first time since March
$GOOGL