₹1,125 to ₹9. Over 1 lakh shareholders.
Gensol was India's clean-energy success story. Then came debt defaults, SEBI's fund-diversion allegations and BluSmart's collapse.
What went wrong? The warning signs tell a bigger story.
Read 👇
#Gensol#Nifty https://t.co/p08Y5HgqkR
YRKR Markets view
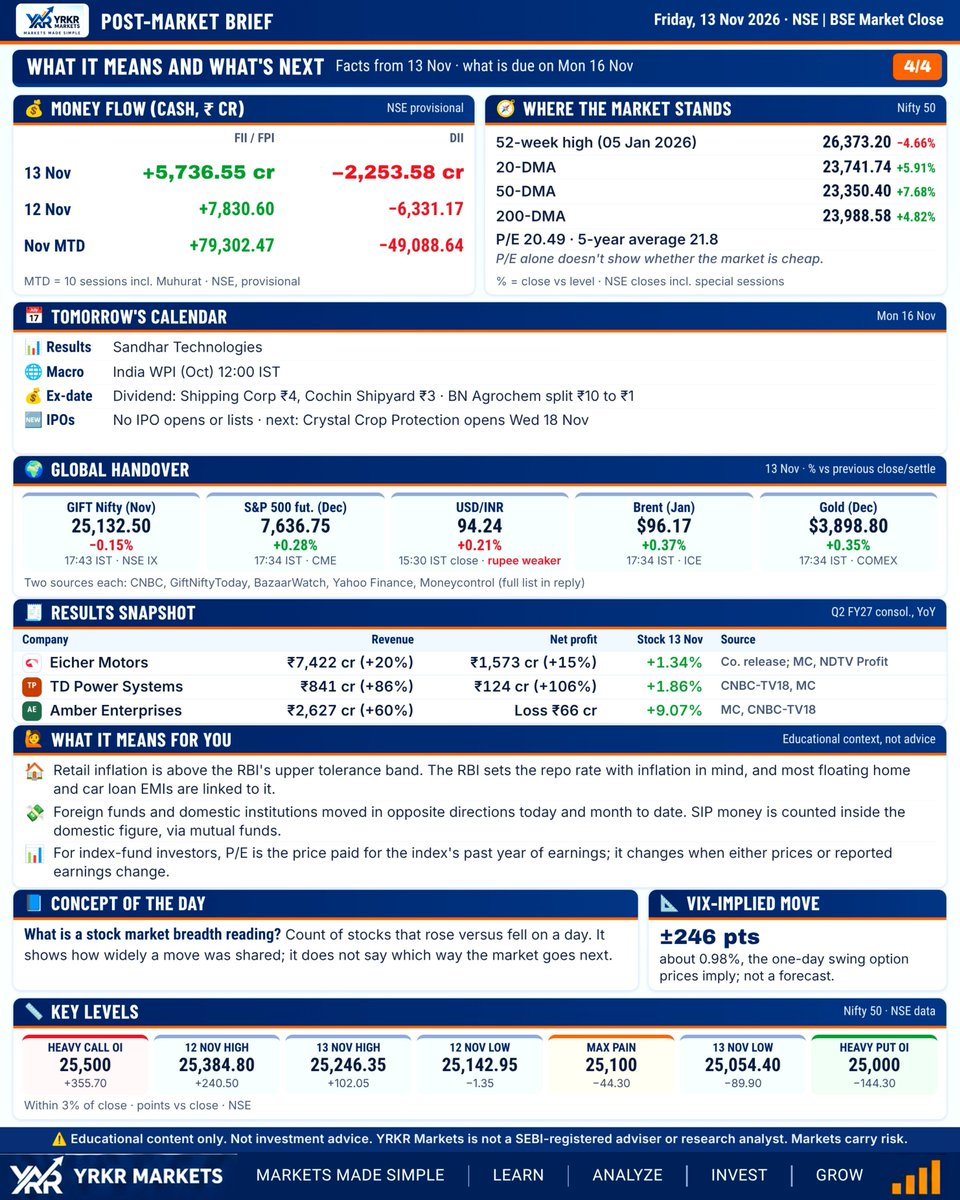
The Nifty 50 fell 0.61% to 25,144.30, with HDFC Bank alone taking off 27.6 points. 38 of 50 Nifty stocks fell, while the Midcap 100 (−0.24%) and Smallcap 100 (−0.26%) fell less. India VIX dropped 6.75% to 15.50. FII net flow was +₹5,736.55 cr and DII −₹2,253.58 cr.
A reading of today's tape, not a call on any stock or sector.
4/4. Slide 4, what it means and what's next: FII and DII money flow, where the Nifty stands against its 52-week high and moving averages, Monday's calendar, the global handover, a results snapshot, what it means for you, the concept of the day 'What is a stock market breadth reading?', the VIX-implied move of ±246 points and key levels.
YRKR Markets view:
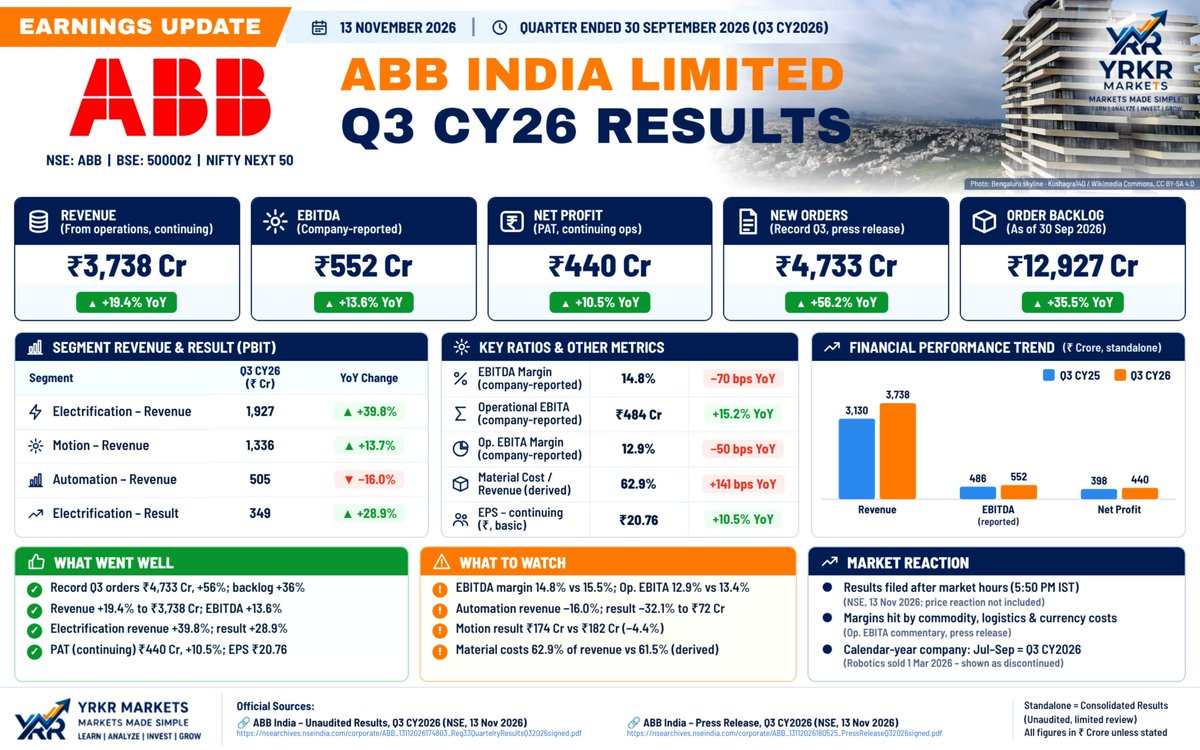
Orders +56% and a ₹12,927 Cr backlog (+36%) give visibility; Electrification revenue +39.8%. But EBITDA margin fell to 14.8% from 15.5% on commodity, logistics and currency costs, and Automation revenue fell 16%.
Simply: demand is strong; watch margins.
People think Huang leaving will sink Nvidia because they treat it like a one-man show. Reality: the moat is the CUDA ecosystem + installed base + chip leadership, not one founder’s personal life. Markets overreact to founder exits every cycle — see Apple post-Jobs. Leadership change ≠ product failure. The real risk is if the new CEO dials back the AI bets, not the resignation itself.
YRKR Markets view:
Revenue and EBITDA both hit records. RE volumes +15.2%, VECV units +28.2%, PAT ₹1,573 Cr, helped by JV profit of ₹186 Cr. Margin slipped to 23.7% from 24.5% on higher D&A and staff costs.
Simply: a strong quarter; track the margin dip, not a red flag yet.
Eicher Motors Q2 FY27 (YoY)
Revenue ₹7,422 Cr (+20.3%)
EBITDA ₹1,760 Cr (+16.4%)
Net profit ₹1,573 Cr (+14.9%)
RE sales 3,76,722 units (+15.2%)
Simply: record sales and EBITDA, but the margin slipped a little.
Record volumes, but a thinner margin — a blip, or a trend? 👇
YRKR Markets view:
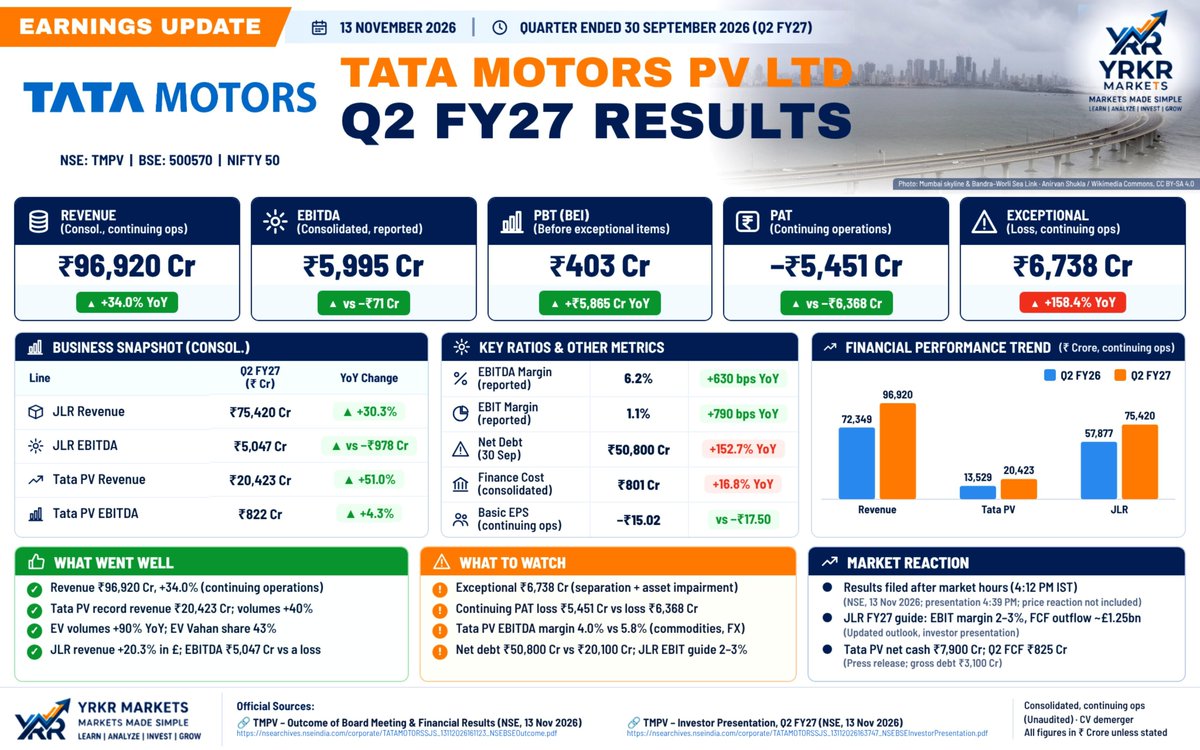
+34% revenue and PBT (bei) ₹403 Cr partly reflect last year’s JLR cyber recovery. Tata PV volumes +40%, EV +90%, PV margin 4.0% vs 5.8%. Watch: exceptional ₹6,738 Cr; net debt ₹50,800 Cr.
Simply: core is healing, but too early to call a turnaround.
YRKR Markets view 👇
The ₹767 Cr hit is exceptional (Canada pulp JV). Core: revenue +25.6%, EBITDA +24.8%, cement volumes +12.9%, Birla Pivot +66%.
Watch: Chemicals EBITDA −10.7%; net debt (ex-FS) ₹45,756 Cr vs ₹38,596 Cr.
One write-off isn't a trend. Track the core.
@vikrantgupta73 Again? One match, one opinion. Where’s the year-round contribution? Dhoni didn’t wait for a bad day to talk about fielding standards. You do.