🚨 “30년간 거짓말이었다”
파우치 고소해서 승소한 미국 보건장관
자료도 없으면서 강제하고, 거부하면 거짓말쟁이 취급했던 30년. 진실은 결국 법정에서 밝혀졌다.
RFK 주니어
"어린이 의무 백신 72개 중 승인 전 위약 대조군 안전성 검사를 거친 게 단 하나도 없습니다."
파우치
"거짓말입니다. 연구 자료가 본부에 있으니 보내드리죠."
RFK 주니어
"자료 내놓으라니까 끝까지 안 주더군요. 그래서 고소했습니다."
정부 측 변호인단 (1년 법정 소송 후)
"사실 관련 연구 자료는 전혀 없었습니다."
First Lady Yuk Young-soo (President Park Chung-hee's wife) was assassinated by a pro-North Korea group JoChongRyeon (조총련) (General Association of Korean Residents in Japan) member. JoChongRryeon has 6 seats in the Supreme People's Assembly in North Korea.
Far left in South Korea released a movie trying to portray that President Park killed his wife--which is contrary to the truth and the facts. Kim Jong-il even apologized to Park Geun-hye (the daughter of Park & Yuk) for the assassination of her mother Yuk Young-soo. But South Korean far left I'd yet again trying to change the narrative of the history.
added some risk - eth, sky, shfl
eth - vitalik reframing from "blockchain" (competing with sol ew) back to "world computer" (n of 1)
sky - longterm revenue business w/ clear value to token
shfl - longterm revenue business w/ clear value to token, also i like togi
gl to us
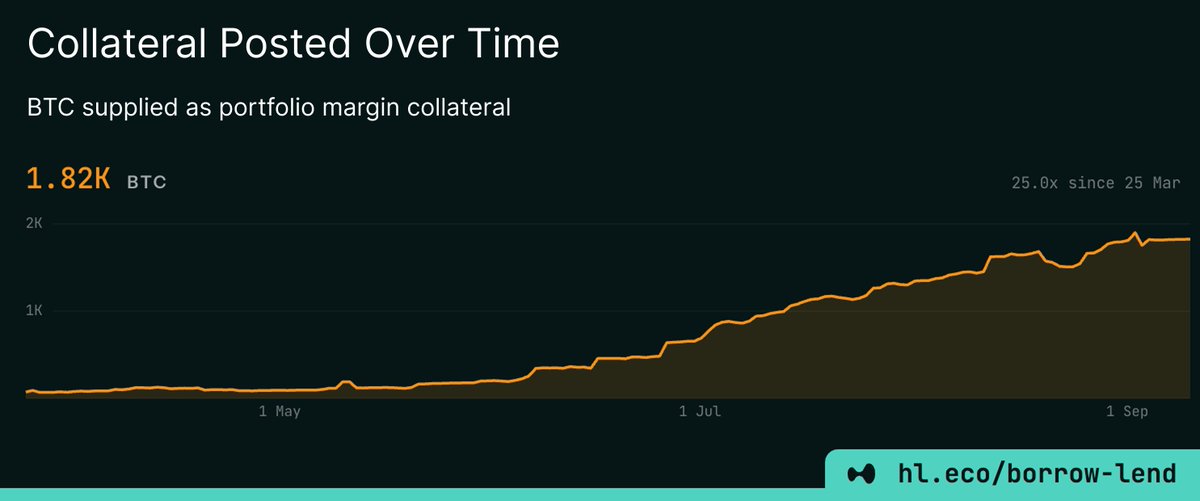
Users can supply BTC as collateral to borrow quote assets (USDC and USDT) on Hyperliquid.
Nearly 31% of deposited BTC, 1.82k BTC ($155M), is supplied as portfolio margin collateral.
1. 하이퍼리퀴드의 시가총액은 여기서 2배 정도를 곱해야 합리적입니다.
미래 토크노믹스와 소각을 고려한 Hyperliquid Startigies의 OTS FDV를 참고하세요.
이를 고려하면 하이퍼리퀴드의 후행 PER은 약 50배이고, 따라서 현재 경쟁사 대비 상대적으로 저평가됐다고 보기는 어렵습니다.
따라서 이제 상대가치 저평가에 기반한 쉬운 차익거래는, 이번 가격 발견으로 멀티플이 리레이팅되며 끝났습니다.
2. 여기서 가격이 올라가려면 장기적으로는 결국 실적이 시장 기대치 대비 반복적으로 가파르게 성장함으로써, 성장주로서의 조건을 입증해야 합니다.
또는 매크로, 유동성, 암호화폐 섹터 고유의 내러티브 광풍 등으로 멀티플이 확장될 수 있으나
로빈후드의 최근 2년 최고점에서의 멀티플은 약 85배였으므로 상방 폭이 크지 않습니다.
3. 클래리티 액트 통과가 가시화되면 일시적으로 100배를 넘길 수도 있겠지만,
로빈후드 사례를 고려할 때 통계적으로 이러한 최고치는 오래 유지되지 못 하며, 최소한 단기적으로는 매도해야 한다는 신호일 겁니다.
실제로 24년 비트코인 ETF 기대감으로 암호화폐 광풍이 불었을 때 비트코인의 가파른 상승은 3개월 정도로 끝났습니다.
4. 이 글은 하이퍼리퀴드가 상승하지 못 한다는 것이 아니며, 저는 여전히 강세론자입니다.
다만 그 논리가 이제는 저평가 가치주에서 성장주로의 논리로 전환됐을 뿐입니다.
시장이 현재 하이퍼리퀴드를 과소평가 중인지 아닌지는 몇 분기 이후 사후에나 드러나겠지만,
저는 시장이 아직도 하이퍼리퀴드의 성장률을 과소평가하는 중이라고 생각합니다.
As a crypto trader for 9 years, the most valuable skill I acquired is executing trades based on facts (the market structure of the chart, flows, where we are in the cycle, etc). It’s common for people to close trades based on emotions instead, e.g. “I’m up/down too much, time to derisk”. Holding the HYPE airdrop is a great example as a case study.
Holding HYPE from $2 to $35 was easy because it was clearly undervalued. Then holding during the bear market had good R/R given the DAT and ETF flows felt underpriced to the point holding something else didn’t feel worthwhile. This ended up being proven true as HYPE was the only coin making new ATHs during the bear market.
You can make the argument that HYPE is no longer undervalued in its present form but continuing to hold now can be warranted given that:
i) There is a tangible long term vision coming together that you can bet on.
ii) We are at the beginning of a bull market and if you have been around the block you’d know that in a bull market tokens don’t trade to what are perceived as rational valuations but rather based on attention and whether the core holders are cultists. And there’s no better signal for long term attention than Trump saying Hyperliquid during a presser.
iii) A coin that is strong in a bear is only going to continue to be strong when the broader market is rallying. This has been proven true thus far with HYPE/BTC trading 1% below it’s ATH.
I am a proponent of taking some chips off the table if you’re happy with the profits but it’s important to keep in mind that this is an action for your own peace of mind, not because the trade is over and there is no more upside to capture.
Most tech giants in the 2000s built their infrastructure and product as one entangled unit. Amazon had the foresight to separate out AWS as an API layer, of which Amazon retail was the first of many users. Today, AWS generates more profit than all of Amazon's other business lines combined.
Hyperliquid is built with the same philosophy. Housing all of finance requires thoughtfully designed, open financial primitives. Each primitive should obey the Unix principle of "Do one thing and do it well." Talented builders then have the foundation to chain these together to create magical applications.
HyperCore borrowing is an example to highlight this philosophy in action.
Most other platforms implement portfolio margin by marking an account's collateral to market value with an LTV haircut, creating borrowed assets without an explicit lender. This system is simpler to implement, but misses a golden opportunity for composability.
Hyperliquid instead begins with a borrow/lend protocol on HyperCore. Every borrowed asset is sourced from a supplier, so risk is isolated within the borrow/lend primitive instead of platform-wide. HyperCore's portfolio margin system is implemented as an orchestration layer that composes borrow/lend, with other primitives such as perps, spot, and outcome trading.
This decomposition has several nice corollaries:
1. Today's announcement of manual borrowing is not a new feature, but simply an extension of the underlying primitive. Borrowers on day one have access to 400M and growing of supplied liquidity.
2. Portfolio margin users earn interest on their idle stablecoin collateral. This is not a new feature, but a natural byproduct of composing trading with lending.
3. System safety is easier to reason about when perp and borrow/lend margining are independent.
In the same way that math theorems almost prove themselves when the right abstractions are defined, composable designs just feel right.