AppLovin: My Investment Thesis
$APP is the advertising channel that CMOs are hiding from their competition - I'm not kidding.
I dive into the following...
- Technological Architecture.
- The Value Proposition.
- AppLovin's MOAT.
- Examples.
- Charts.
- RISK.
These papers are always free. So please subscribe and enjoy!
Substack Link: https://t.co/613J8iOO41
Cheers,
Nick.
JUST IN:
-SoFi CEO Anthony Noto believes that SoFi ($20 billion market cap) will have more deposits than Nubank ($70 billion market cap) in five years.
Wow.
- Guess whos already considered a top-tier user and advanced adopter FedNow? $SoFi 📈
SoFi is already a full send-and-receive participant on FedNow through its Galileo platform
The Fed’s plan to let FedNow handle the U.S. leg of cross-border payments would let SoFi settle those domestic portions in seconds rather than days, potentially lifting transaction volume, deposit stickiness, and Galileo’s value as a sponsor-bank rail for other fintechs.
$APP sentiment is quite interesting.
People are of the belief that this is a dying company, set to report declining revenues consistently quarter after quarter. This is SO far from the truth.
In the recent Edgewater Research report, they make the argument that AppLovin has effectively hit their ceiling.
Specifically - and this is important... The mobile gaming MAX supply ceiling.
To the uneducated reader, this may come across as dramatic. AppLovin has a 73% share monopoly on ALL top-downloaded mobile game mediation. Essentially, AppLovin is the integrated ad-space auctioneer for this overwhelming majority of mobile games.
It comes at NO surprise that they have more-less hit a ceiling here.
The report continued to make the argument that AppLovin's QoQ growth has started to plateau, which indicates this ceiling has neared. This is not overly bearish - not at all. I'll explain why in a second.
But first, there is this sentiment that competitors are going to release superior models and displace AppLovin's monopoly. I think there is a vast technological misunderstanding here. AppLovin has the superior models achieving superior outcomes for both buyer and seller because they have the lions-share of the market - looking at this through a perhaps naive lens you may assume that one could just come and "take" market share with a superior model or product...
But you're missing a critical piece of the puzzle.
These game developer companies literally rely on AppLovin for revenue. There is a dependency here. Their models have become so good, that every dollar spend by a game developer on AppLovin's ecosystem, leads to an dipropionate increase of revenue generated. They accomplish this by real-time model refinement and data ingestion through each SDK install within their MAX mediation network. 1 billion DAUs playing thousands of the top-downloaded games produce a lot of 1P data in real-time. It is this very data that gives AppLovin their edge - and it's this very edge that the game-developers rely on to stay profitable.
The game developers would have to gamble with solvency, just to jump-ship and divert spend/integrations with a competitor. This would be a horrible business decision.
So the compounding outcome is exponential for AppLovin. The developers are locked in because their ability to generate revenue has become an arbitrage of dollars spent on platform. And this relationship only exists if they stay integrated with AppLovin, thus feeding them the data which refines their models that produces the superior outcomes each developer desires.
It's a self-fulfilling flywheel.
Interestingly - the party with the superior dataset will always produce the superior model. It just so happens that AppLovin has the largest market-share, the top-download apps, and real-time data ingestion for the 1 billion DAU audience it has created.
Good luck displacing this juggernaut with an inferior dataset.
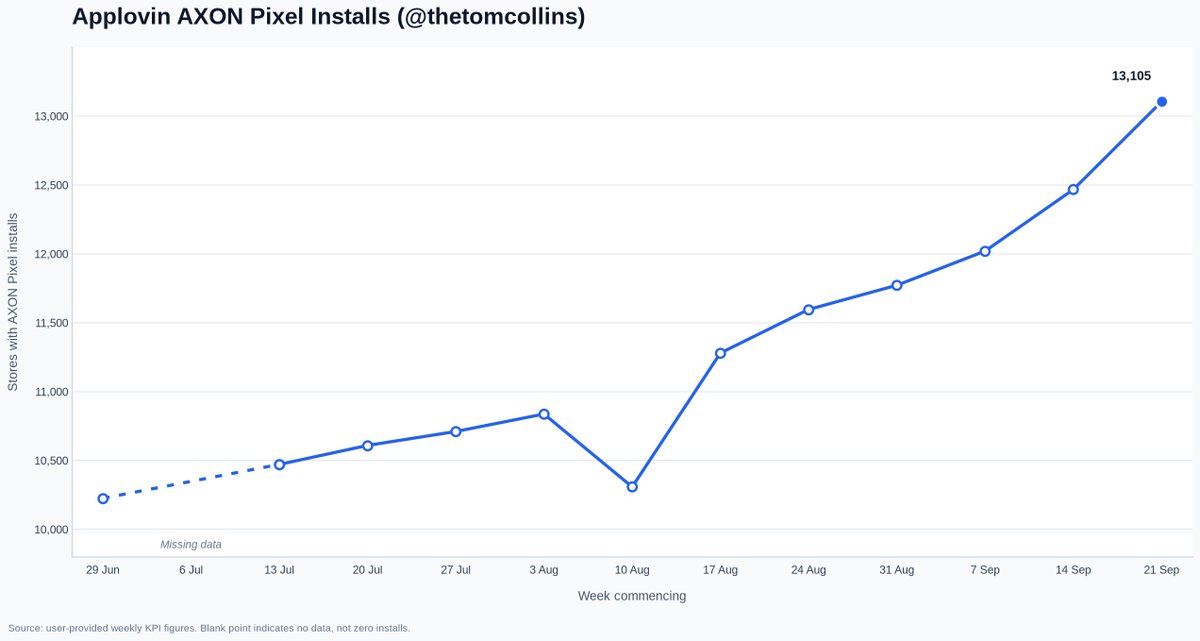
Now, let's circle back to plateauing revenues QoQ. Yes, with 73% market-share eventually your revenue potential here will start to cap-out. Though AppLovin has started to expand self-serve demand by allowing DTC Shopify brands or consumer brands to also buy ad-space on the network - this has been a modest start. Even though we have recently seen an uptick of pixel installs on consumer sites (this is a strong indicator of the amount/velocity of new advertisers ramping).
The true potential unlock for further growth and TAM expansion, is the natural unlock beyond the confined four-walls of mobile-gaming AppLovin finds themselves in. This is called "supply-side expansion".
Adam, the CEO has outlined this himself...
1/2
📢 𝗝𝗨𝗦𝗧 𝗜𝗡: SoFi and Mastercard Launch Stablecoin Settlement Across $25 Billion Card Program - $SOFI $MA
👉 𝗞𝗲𝘆 𝗛𝗶𝗴𝗵𝗹𝗶𝗴𝗵𝘁𝘀:
➤ 𝗦𝗼𝗙𝗶 and 𝗠𝗮𝘀𝘁𝗲𝗿𝗰𝗮𝗿𝗱 launch live stablecoin settlement using 𝗦𝗼𝗙𝗶𝗨𝗦𝗗.
➤ SoFi is migrating its entire $𝟮𝟱 𝗯𝗶𝗹𝗹𝗶𝗼𝗻 card program.
➤ Card transactions are already settling on the 𝗯𝗹𝗼𝗰𝗸𝗰𝗵𝗮𝗶𝗻.
➤ 𝗦𝗼𝗙𝗶𝗨𝗦𝗗 is issued by OCC-regulated 𝗦𝗼𝗙𝗶 𝗕𝗮𝗻𝗸, 𝗡.𝗔.
➤ SoFiUSD is fully redeemable 𝟭:𝟭 for U.S. dollars.
➤ Reserves supporting SoFiUSD consist primarily of 𝗰𝗮𝘀𝗵.
➤ Merchants can access settlement funds instantly without holding 𝘀𝘁𝗮𝗯𝗹𝗲𝗰𝗼𝗶𝗻𝘀.
➤ SoFi is discussing stablecoin settlement with 𝗹𝗮𝗿𝗴𝗲 𝗨.𝗦. 𝗺𝗲𝗿𝗰𝗵𝗮𝗻𝘁𝘀.
➤ Future opportunities include 𝗰𝗿𝗼𝘀𝘀-𝗯𝗼𝗿𝗱𝗲𝗿 𝗽𝗮𝘆𝗺𝗲𝗻𝘁𝘀 and remittances.
👉 𝗪𝗵𝘆 𝗧𝗵𝗶𝘀 𝗠𝗮𝘁𝘁𝗲𝗿𝘀:
➤ Moves bank-issued stablecoins from experimentation into 𝗹𝗶𝘃𝗲 𝗽𝗮𝘆𝗺𝗲𝗻𝘁 settlement.
➤ Potential $𝟮𝟱 𝗯𝗶𝗹𝗹𝗶𝗼𝗻 annualized volume gives deployment significant commercial scale.
➤ Could give merchants 𝗳𝗮𝘀𝘁𝗲𝗿, around-the-clock access to settlement funds.
➤ Connects traditional card infrastructure with 𝗯𝗹𝗼𝗰𝗸𝗰𝗵𝗮𝗶𝗻-𝗯𝗮𝘀𝗲𝗱 settlement rails.
👉 𝗘𝘅𝗽𝗲𝗿𝘁 𝗦𝘁𝗮𝘁𝗲𝗺𝗲𝗻𝘁𝘀:
𝗔𝗻𝘁𝗵𝗼𝗻𝘆 𝗡𝗼𝘁𝗼, CEO of SoFi:
“In six months, SoFi and Mastercard took stablecoin settlement from an idea to a live product that materially improves how money moves for businesses,” said Anthony Noto, CEO of SoFi. “Merchants do not need to hold stablecoins, build new infrastructure or change how they operate. Through SoFi’s Big Business Banking platform, any merchant can receive settlement funds instantly in a SoFi Bank account and withdraw to cash around the clock and at zero cost. That means businesses have faster access to their money via the speed of blockchain, with the safeguards of a bank.”
𝗦𝗵𝗲𝗿𝗿𝗶 𝗛𝗮𝘆𝗺𝗼𝗻𝗱, Global Head of Digital Commercialization, Mastercard:
"Stablecoins become meaningful when they solve real problems that businesses face every day," said Sherri Haymond, Global Head of Digital Commercialization, Mastercard. "With SoFi, we're moving beyond exploration to implementation, bringing regulated stablecoin settlement into a live production environment while preserving the trust, scale and safeguards expected from Mastercard. This is another step toward giving businesses more choice in how money moves."
Thank you to @KrisPatel99@Sam_Badawi and @wealthmatica for discussing Ad-Tech for over an hour last night with me. $APP is super interesting and I have just become bullish on it.
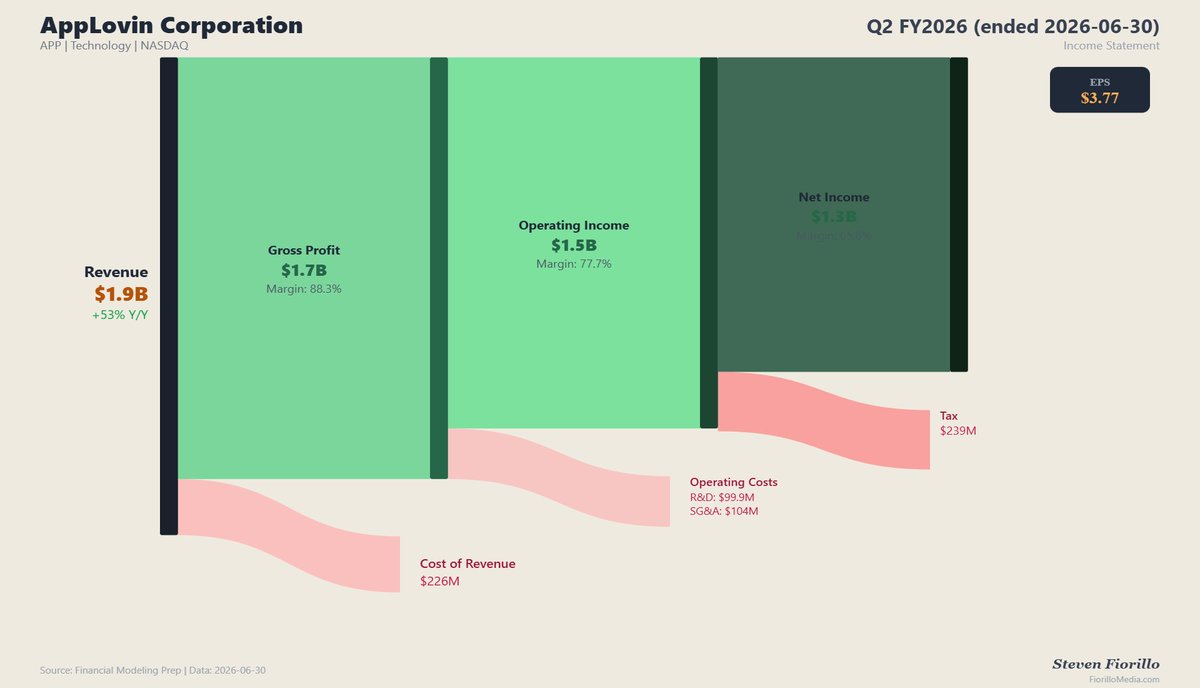
Funny how a company that just grew revenue in Q2 by 53% YoY with a gross margin of 88.3% and an operating margin of 77.7% can be so hated.
What is even funnier is that APP had a 100% FCF margin in Q2 after producing $869 million and $551 million of it went to buybacks.
But hey I guess nothing to see here............
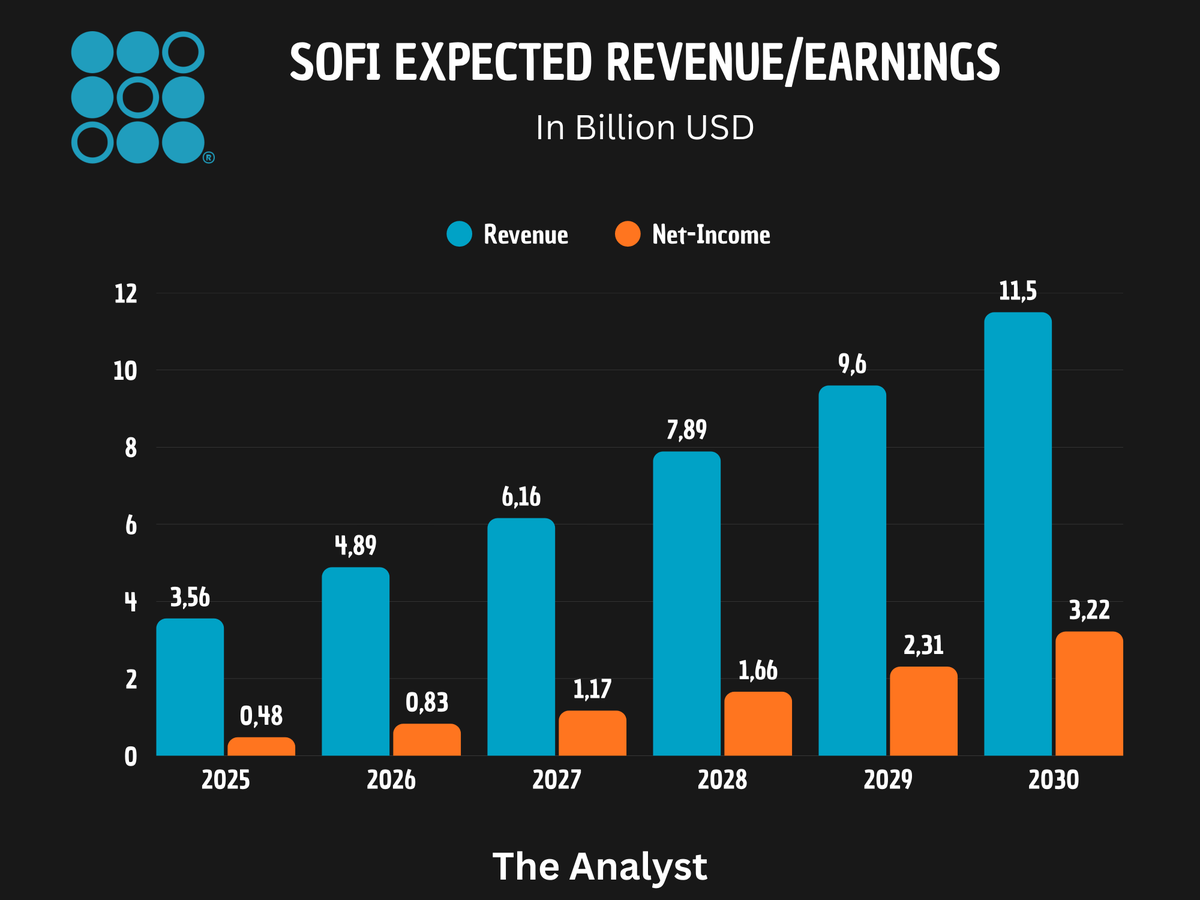
$SOFI projection until 2030.
This really puts things into perspective.
Revenue is expected to more than double, from $4.89B up to $11.5B in 2030.
Earnings on the other hand should QUADRUPLE.
Strong operating leverage is what makes this possible.
Margins will improve further the more revenue grows.
Put a 25x Multiple on this and it's a $80B stock.
And there's still a lot more upside potential, as I think we could see $SOFI easily surpass these numbers, and multiples can easily expand when a stock is in a bullmarket.
Mark my words: $SOFI will be $100 by 2030.
- $SoFi during an interview w Tannor, Noto specifically stated he believes that
“SoFi is technically better off without the clarity act because they are already a nationally chartered bank and that OCC came out in 2025 with an interpretive letter saying banks have permissibility to operate in crypto currency and blockchain”
Clarity not passing, is not a negative for SoFi, but would have been beneficial for the sector as a whole
@gfvf1021@TJTheWheelDeal A bank holding company can't complete an acquisition that would push it over 10% of total U.S. deposits (30% for a single state), unless the target bank is failing. So yes they could…
$SOFI USD stablecoin to be listed on the Kraken exchange, enabling retail investors to use it.
Payward, Kraken's parent company, will also utilize SoFi’s real-time settlement rails. This allows Kraken’s institutional clients to clear and settle U.S. dollar transactions 24 hours a day, 7 days a week.
This partnership is a major proof-of-concept for SoFi's SofiUSD stablecoin. By securing a massive player like Payward/Kraken as a client for its settlement network, SoFi validates its strategy of serving enterprise fintechs. Additionally, distributing SoFiUSD on a major exchange accelerates the adoption of its stablecoin.