Portfolio Manager of the Bullseye American Ingenuity portfolio and author of the weekly Bullseye Brief. Ex-BloombergTV anchor. Love to shoot, ski and cook.
The bond market did the Fed's job for it.
@AJInsight explains how Treasury yields effectively delivered two rate hikes without the Fed lifting a finger.
Now yields are falling. Is inflation finally peaking?
.@AJInsight reacts to Nvidia investigating CEO Jensen Huang over affair with alleged Chinese spy: “He has been the face of AI, but I don't think ultimately this is that big a story for Nvidia. It may prove to be a big story for Jensen Huang. … But Nvidia is the juggernaut.” | @RiggsReport
Each https://t.co/4DtCzd7OmL issue highlights an American Ingenuity Portfolio pick, addresses relevant news/ catalysts/ trades and sparks conversation.
Political gridlock, a bond rally, and a shift in market leadership. Is Wall Street rotating from growth to value? @AJInsight breaks it down with @sws9876.
🔗https://t.co/LdNpRbv4Yt
The Fed holds, but a December hike is on the table. Plus, Microsoft gets rewarded for AI revenue while Google gets punished for spending. What is the market telling us? @AJInsight and @sws9876 discuss.
🔗https://t.co/ICxkf2J5nd
Meta beat revenue but faces a massive legal charge. Tesla beat on adjusted earnings, while IBM beat and raised guidance. Yet all three stocks came under pressure. What’s Wall Street looking for now?@AJInsight and @sws9876 discuss.
🔗https://t.co/mQIoBteLNU
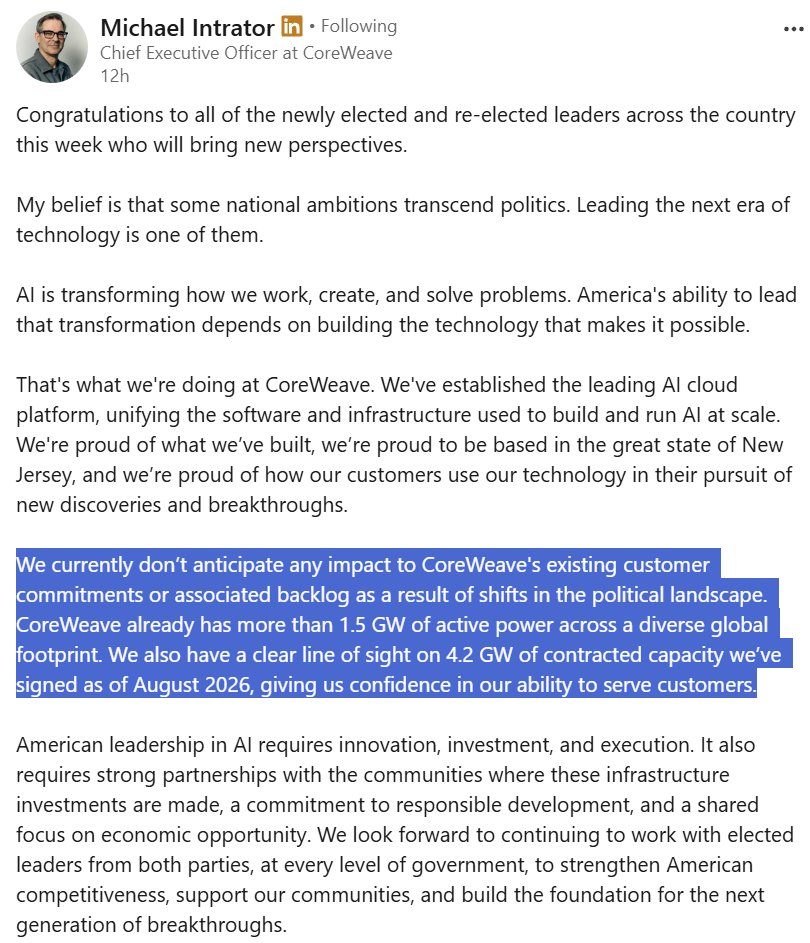
A lot of questions this week on funding, so here's how a GPU typically gets funded at $IREN.
First, the customer signs a multi-year take-or-pay contract and agrees to a prepayment. On our recent 3-year contracts, prepayments have been 45% to 55% of the associated GPU capex.
Second, financing is committed, secured by the contracted GPUs. On the Microsoft contract we secured an A-rated facility at around 6%, which together with prepayments covers 96% of GPU capex. More recently, for a non-investment grade counterparty at Mackenzie, we secured financing at 9% fixed, which together with prepayments covers more than the full cost of the GPUs.
That's the GPU side. The data centers are a separate, long-term asset base, and we own the ones our GPUs run in. Construction has been funded from cash to date, with no debt against these multi-billion dollar assets. As they come online with contracted customers, they can support financing in their own right.
The processes behind the next facilities are continuing, and new paper will cost what the market charges. With GPU paybacks of around two years on our recent 3-year contracts, a wider spread barely moves the economics.
There's more customer demand than we can build for. As we noted at our recent earnings, 2026 is largely sold out, recent 3-year contracts are at more than double the prior year's pricing, and demand for anything we can bring online in 2027 covers it several times over, with prepayments a focus in every negotiation. Conversations on 2028 capacity are already underway.
Meanwhile announced capacity keeps slipping across the industry, which is the point: signing deals isn't the bottleneck in this market, bringing GPUs online is, and that's our focus.
@AJInsight what do you make of HSBC's report on CRWV and their price target of $39? Are they just a bunch of short sellers trying to pump their holdings down?
Each https://t.co/4DtCzd7OmL issue highlights an American Ingenuity Portfolio pick, addresses relevant news/ catalysts/ trades and sparks conversation.