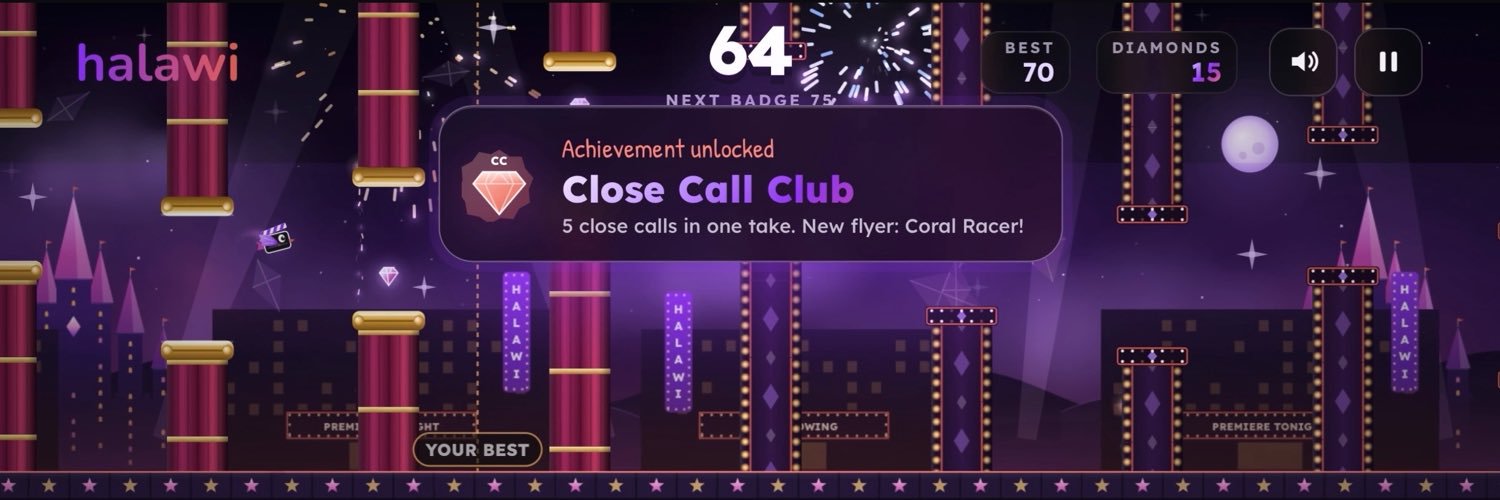
Classic 8-ball gets boring after a while. That’s why we built a Director’s Cut with wild modes pool game at Halawi, curated for film industry professionals. Play for free. No signup.
https://t.co/wr3csrjxtv
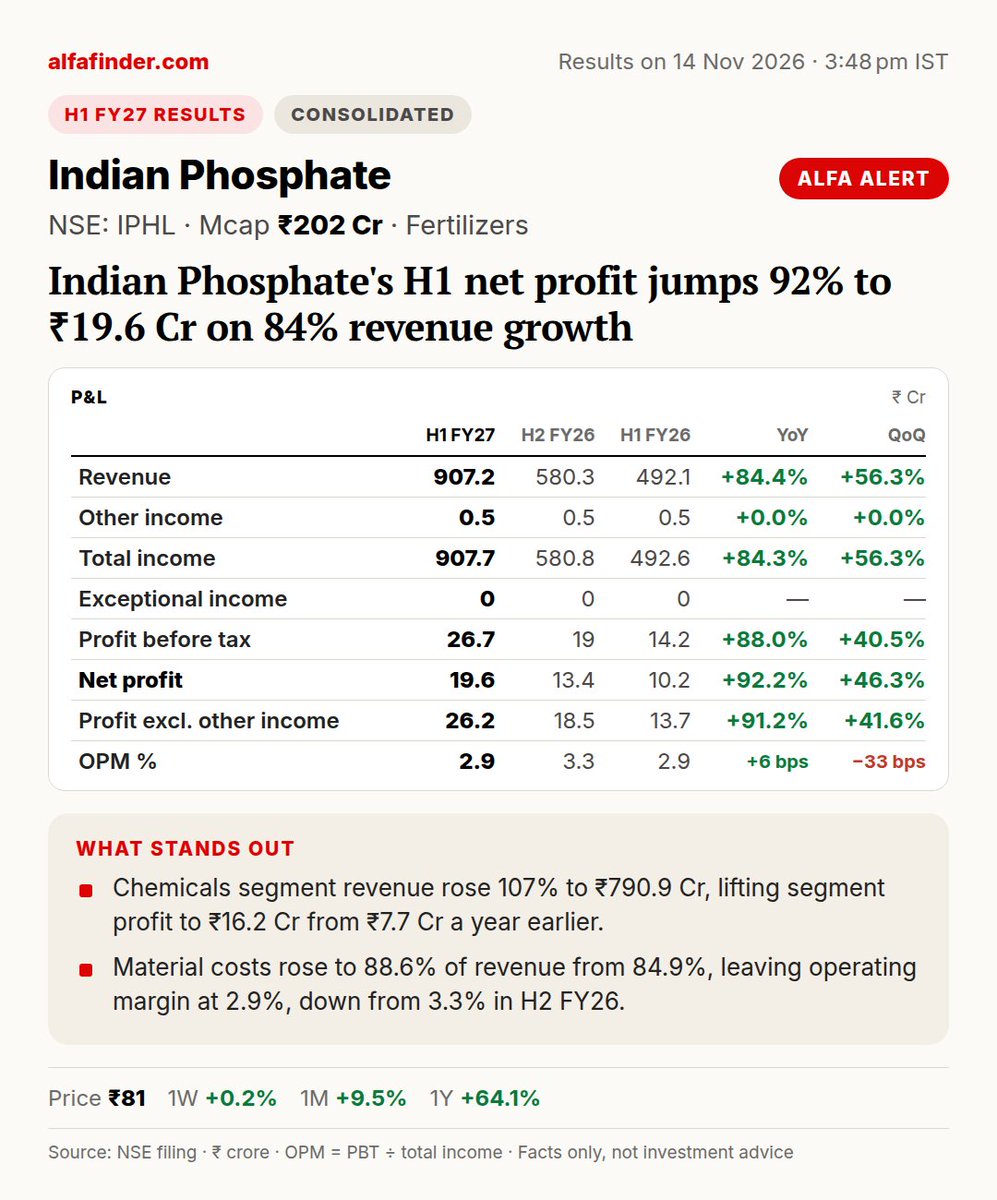
Indian Phosphate | H1 FY27 results
Indian Phosphate's H1 net profit jumps 92% to ₹19.6 Cr on 84% revenue growth
👉 Indian Phosphate's consolidated revenue rose 84% to ₹907.2 Cr in the half year ended 30 September 2026, against ₹492.1 Cr in H1 FY26 and ₹580.3 Cr in H2 FY26. Net profit grew 92% to ₹19.6 Cr from ₹10.2 Cr, and profit before tax rose 88% to ₹26.7 Cr. The table shows no exceptional items in either period.
👉 Chemicals drove most of the increase. Segment revenue rose to ₹790.9 Cr from ₹381.9 Cr in H1 FY26, and segment profit increased to ₹16.2 Cr from ₹7.7 Cr. Fertilizer revenue reached ₹160.9 Cr from ₹110.0 Cr, and the segment earned ₹9.6 Cr against a ₹0.8 Cr loss in H2 FY26. Unallocated items reduced consolidated revenue by ₹44.7 Cr.
👉 Material costs absorbed more of each rupee of sales. Cost of materials consumed rose to ₹803.6 Cr from ₹417.7 Cr, or 88.6% of revenue against 84.9% a year earlier. Operating margin was 2.9%, broadly flat year on year but down from 3.3% in H2 FY26. Finance costs rose 37% to ₹47.5 Cr, and depreciation rose to ₹28.8 Cr from ₹19.8 Cr.
👉 Operating cash flow turned negative. The company used ₹38.7 Cr in operations in H1 FY27 against a cash inflow of ₹10.6 Cr for FY26, as trade receivables rose to ₹221.8 Cr from ₹121.4 Cr and inventories to ₹114.3 Cr from ₹46.6 Cr since March 2026. Total borrowings rose to ₹132.2 Cr from ₹69.2 Cr, and cash and cash equivalents closed at ₹9.5 Cr. Capital expenditure was ₹9.2 Cr.
👉 Growth catalyst: Commercial production began at the new LABSA plant in Cuddalore on 29 June 2026, funded by IPO proceeds, while management is pursuing forward integration into magnesium sulphate and expanding its specialty chemicals portfolio.
👉 Road blocker: Operating cash flow was negative ₹38.7 Cr as receivables and inventories absorbed cash, and the 2.9% operating margin remains thin.
Public NSE filing · Not investment advice
#IPHL #H1FY27 #StockMarket #Earnings #H1withAlfafinder
@pakriyasat@Sanchita8M@SkyNews Lahore is the epicenter of world trrorsim. mf. we worship women. Someone who fck sisters and goats should keep quiet on serious matters.
@pakriyasat@Sanchita8M@SkyNews Lahore is the epicenter of world trrorsim. mf. we worship women. Someone who fck sisters and goats should keep quiet on serious matters.
@KiwiSbg9@detremura Very generous cat. I’m certain 99% of the cats wouldn’t have bothered to pay with a leaf. They simply own the whole place, why pay the hooman?
Indian Phosphate | H1 FY27 results
Indian Phosphate's H1 net profit jumps 92% to ₹19.6 Cr on 84% revenue growth
👉 Indian Phosphate's consolidated revenue rose 84% to ₹907.2 Cr in the half year ended 30 September 2026, against ₹492.1 Cr in H1 FY26 and ₹580.3 Cr in H2 FY26. Net profit grew 92% to ₹19.6 Cr from ₹10.2 Cr, and profit before tax rose 88% to ₹26.7 Cr. The table shows no exceptional items in either period.
👉 Chemicals drove most of the increase. Segment revenue rose to ₹790.9 Cr from ₹381.9 Cr in H1 FY26, and segment profit increased to ₹16.2 Cr from ₹7.7 Cr. Fertilizer revenue reached ₹160.9 Cr from ₹110.0 Cr, and the segment earned ₹9.6 Cr against a ₹0.8 Cr loss in H2 FY26. Unallocated items reduced consolidated revenue by ₹44.7 Cr.
👉 Material costs absorbed more of each rupee of sales. Cost of materials consumed rose to ₹803.6 Cr from ₹417.7 Cr, or 88.6% of revenue against 84.9% a year earlier. Operating margin was 2.9%, broadly flat year on year but down from 3.3% in H2 FY26. Finance costs rose 37% to ₹47.5 Cr, and depreciation rose to ₹28.8 Cr from ₹19.8 Cr.
👉 Operating cash flow turned negative. The company used ₹38.7 Cr in operations in H1 FY27 against a cash inflow of ₹10.6 Cr for FY26, as trade receivables rose to ₹221.8 Cr from ₹121.4 Cr and inventories to ₹114.3 Cr from ₹46.6 Cr since March 2026. Total borrowings rose to ₹132.2 Cr from ₹69.2 Cr, and cash and cash equivalents closed at ₹9.5 Cr. Capital expenditure was ₹9.2 Cr.
👉 Growth catalyst: Commercial production began at the new LABSA plant in Cuddalore on 29 June 2026, funded by IPO proceeds, while management is pursuing forward integration into magnesium sulphate and expanding its specialty chemicals portfolio.
👉 Road blocker: Operating cash flow was negative ₹38.7 Cr as receivables and inventories absorbed cash, and the 2.9% operating margin remains thin.
Public NSE filing · Not investment advice
#IPHL #H1FY27 #StockMarket #Earnings #H1withAlfafinder
@railcomplaint So many illegal people (without any valid tickets) have occupied the train 20485/JSM SBIB SF EXP. Do something immediately or else i will never waste money buying irctc ticket ever again. 😠 what the hell is your TC doing? Sack him if he’s unable to do job.