Hindsight is infallible. Real edge is knowing luck from skill and pressing high-conviction bets. Clinical-stage biotech and equity research. Not advice.
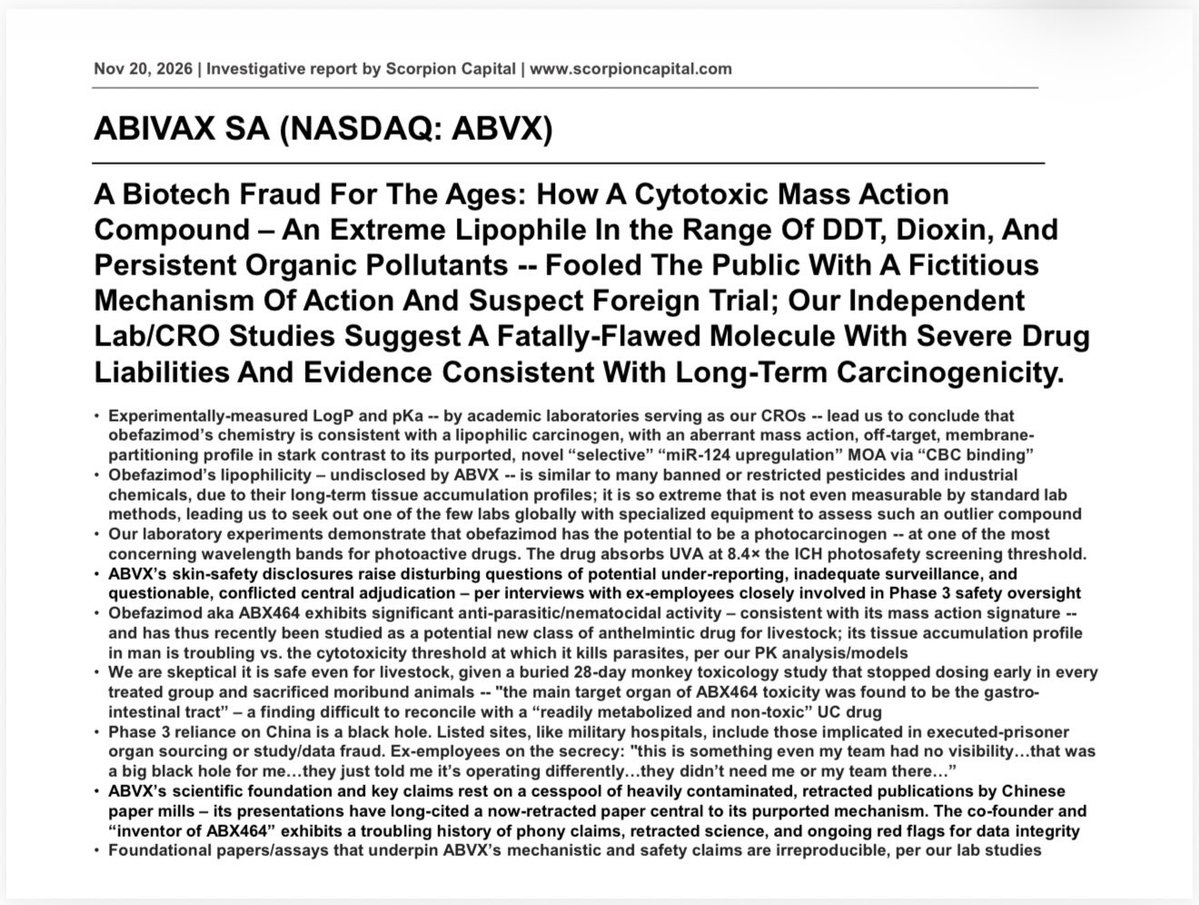
NEW: We are short $ABVX Abivax SA - a biotech fraud for the ages. Report now live on our site, along with four scientific abstracts based upon our laboratory experiments. An 11-month investigation, our most intensive research to date.
Scorpion Capital really spent "11 months" writing 297 pages just to get speed-run over a weekend by a guy named Adam, a guy named Adam, and a guy named Adam.
At this point utm_source=https://t.co/J7kXTiGXGn is their strongest peer-reviewed source on $ABVX.
Important to remember, these are sicker patients than Paradigm so this is setting up for higher probability successful primary and secondary endpoints. Also this is 20% of the size of paradigm DurAvr arm so it’s not a tiny n, obviously. $avr
Quick break from my regular posts to share some real alpha. I’m a massive olive oil enthusiast, & this Greek EVOO is easily the best bottle I’ve ever tasted. If your EVOO does not give you a sharp peppery burn at the back of your throat, you are buying overpriced cooking grease.
you can’t make this up 🤣 @ScorpionFund forgot to update his AI slop in the footnotes of this slide in the $ABVX short report (highlighted below) before publishing. Lost all his credibility in one day
@shhall32 Because US IBD is a concentrated specialty GI market, $ABVX does not need a massive primary-care sales force to compete. To me, GIA sets the valuation floor, and M&A is pure upside if the label lands clean or mid-2027 Crohn's data hits.
Appreciate that, Adam. I mostly just dig into the names I own, and reading your breakdowns every day is a big part of how I learned to spot the noise in biotech. Means a lot getting the nod from the real authority on this app $ABVX 👊🏻
Listen. I'm Adam enough to admit when I've been out-Adam'd.
If you're looking for scientific rebukes of some of the finer technical points in the Scorpion $ABVX report, read through this thread. Fortunately for all of us, essentially all of the points are so easily disproven that each refutation only requires a single line of text.
This dude bodies Scorpion here. Absolute Adam.
@shhall32 The irony in biotech is that a credible standalone launch is the only way you ever command full value in M&A. Around a ~$7B market cap, Big Pharma wants NDA acceptance or Crohn's data before writing a double-digit billion check.
Fair take, Andre, and I respect separating the noise from the real clinical questions. That said, the two concerns raised around the North America subgroup look much less alarming once you check the endpoint math and look at the broader Western population in ABTECT. $ABVX 1/
$ABVX
last tweet on the subject
Scorpion has a lot of questionable analysis of the MOA and TRAE. Most of that have been answered by the data so far.
But the subgroup analysis of the US pts is concerning (page 292)
There so many red flags in this table that would make the approval unpredictable. For example lack of correlation bn Endoscopic improvement and clinical remission in North America pbo
No need to agree 100% with Scorpion, they just have an agenda, but they have some valid points
The FDA will certainly run regional sensitivity checks on the NDA. With Western Europe clearly hitting centrally read endoscopy and histology on 50 mg and North America directionally aligned on remission and safety, this looks like standard small-N subgroup variance…