My latest piece: From fringe experiment to civilization enabler—#Lithium batteries now power fleets, homes, grids, & the energy transition itself. This isn’t just disruption—it’s infrastructure. The post-combustion era has begun. ⚡ #EnergyTransition#LFP
https://t.co/qga1pvoSrF
$AVZ provides shareholders with the following update:
ICC Tribunal Decision Against Cominière to Liquidate an Accrued Penalty of €39M and Response to Media Speculation
Full announcement here👉https://t.co/pWz1XSPrQY
#AVZ#ManonoLilthiumandTinProject#DRC
President Trump has a strong focus on critical minerals for nearly a decade now.
China’s dominance of the rare earth industry was of key political focus back in 2017.
This dragged other critical minerals into the discussion especially cobalt, graphite, nickel and lithium (in that order)
Lithium was a similar strong focus for @elonmusk since the early 2010s as well. Tesla close to buying a lithium mine on more than one occasion … and now has opened a refinery in Texas.
This all evolved into Biden’s American Jobs Act which became Inflation Reduction Act… but it began with Trump 1.0
Senator @lisamurkowski and @marcorubio were key proponents and catalysts for this thematic.
A reminder of key actions:
1.Executive Order 13817 (December 20, 2017): “A Federal Strategy To Ensure Secure and Reliable Supplies of Critical Minerals”
2.Executive Order 13953 (September 30, 2020): “Addressing the Threat to the Domestic Supply Chain From Reliance on Critical Minerals From Foreign Adversaries and Supporting the Domestic Mining and Processing Industries”
3. And now the 3rd executive order… the day one Unleashing Americas Energy on January 20, 2025
Back in 2017, it was more a political than industrial necessity as the US did not have the midstream component manufacturing that are the immediate customers of these critical minerals and chemicals.
Now the US is in play with these industries - especially lithium ion batteries.
Two good @benchmarkmin reads:
➡️ How Biden Admin raced to protect clean energy loans
https://t.co/SysfMdDJYI
➡️ What do Trump’s executive orders mean for critical minerals
https://t.co/anp4nWnt8b
➡️ Mine and @MBazilian’s 5 Ways to Act on Critical Minerals
https://t.co/Uoyp3Cftat
🔥NEW: Lithium-ion Bull 100th Anniversary Issue - It's a Long Way to the Top🔥
Click here for Issue 100👉 https://t.co/zRL6dmmUpF
A 🧵
1/17 "If you write it, you know it…"
What have I’ve learned over the past 5, 10, 15 years to inform a view for 2025 and beyond?
Does Trump 2.0 and his entourage of self-made billionaire entrepreneurs justify "Morning in America" optimism that is still bullish #lithium?
Could $TSLA’s sharp post election rise be a leading indicator for lithium as it was ahead of Battery Day in 2020?
It’s a Long Way to the Top (If You Wanna Rock and Roll) with most lithium equities down 50-90% from all-time highs. But will we at least be Back in Black by 2025/26?
Click through this thread for some highlights of my extensively researched reflection on the state of play in lithium land as we enter a new world in Washington AC/DC.
This time, we are the horses: The #disruption of labor by #HumanoidRobots. 👤 🤖 〰️ 🚘 🐴
Our first longread in this series is now available via the @rethink_x blog.
https://t.co/fuAZWFyKQF
Why falling prices, growing price parity between EVs and traditional vehicles, and skyrocketing demand could mean now is the time to invest in lithium. https://t.co/U2MScHIvS4
No coffee today as I spat it out reading Goldman Sachs' lithium supply table which popped up in my twitter feed.
What i find most intriguing about this table is that it states the majority of lithium supply will come from China itself, in particular internal lepidolite and brine.
In my opinion, this is unrealistic and the numbers don't quite seem logical. Lets break down the lepidolite numbers:
They are predicting that 462,000t of LCE will be produced internally from Chinese lepidolite in the year 2030.
Using a previous post of mine (i'll put the link in the comments below), for a lepidolite ore of grade 0.55%, you need approximately 14 tonnes of lepidolite to get SC6 equivalent. Roughly 6 tonnes of SC6 is needed for 1 tonne of LCE.
You need around about 14 * 6 = 84 tonnes of lepidolite ore grading 0.55% to get 1 tonne of LCE... 🤯
84 * 462,000t LCE = 38,808,000 tonnes of ore grading 0.55% to meet 2030 yearly output prediction alone. That's 6 years away...
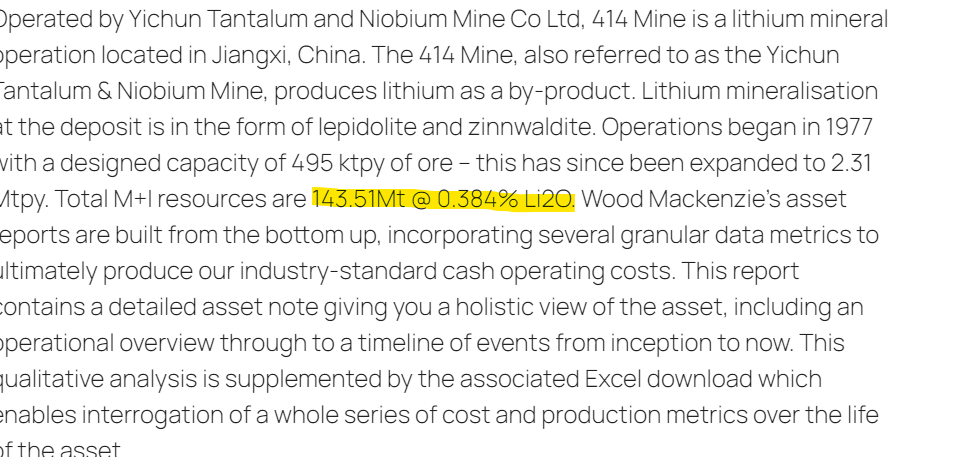
The largest documented lepidolite mine within China is the "414 Mine". Approximately has 130Mt @ 0.38% li2O. That's roughly equivalent to a #GL1 Manna deposit in terms of contained lithium. Plug the above 0.38% into the previous calc and you're almost processing half of China's biggest documented lepidolite deposit yearly... Defies logic for me.
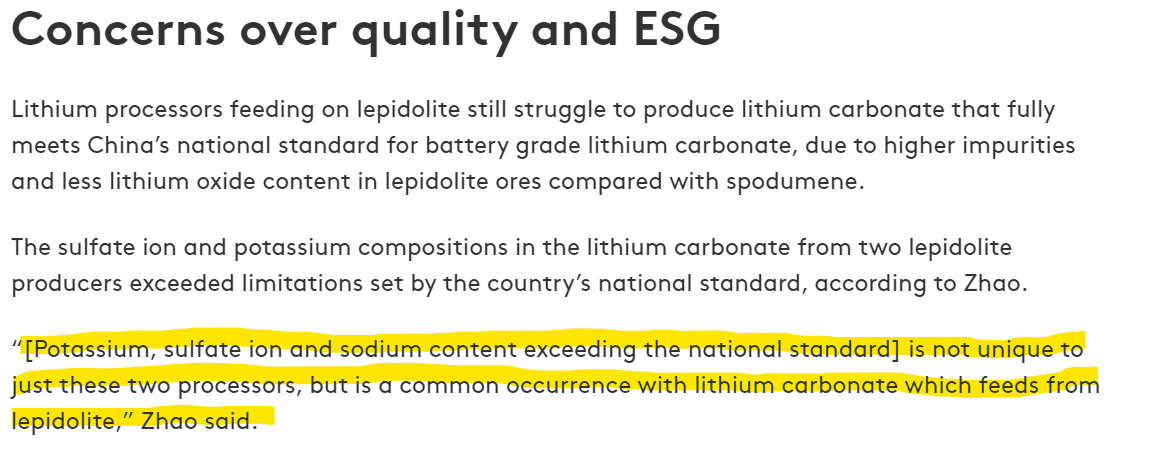
Also, the above is just talking about pure tonnage. The waste products (which i've touched on in previous posts) from the deleterious elements (iron, fluorine, potassium, etc.) within lepidolite will be astronomical. There are already reports of converters sending ore back and tailing storages blowing out in size. How is it going to look when you are processing 38Mt+ of low grade lepidolite ore a year?
Lepidolite contains more deleterious elements than spodumene, is generally lower grade, is slower and more difficult to process, especially in the leaching stage. I'm sticking to my view that the lepidolite deposits and stockpiles get exhausted soon and that the processing of lepidolite is a short term attempt by China to squash the market. IMO there is no chance lepidolite will ever be cheaper than spodumene to process and it isn't a realistic solution to meet future lithium demand. Cheers for reading.