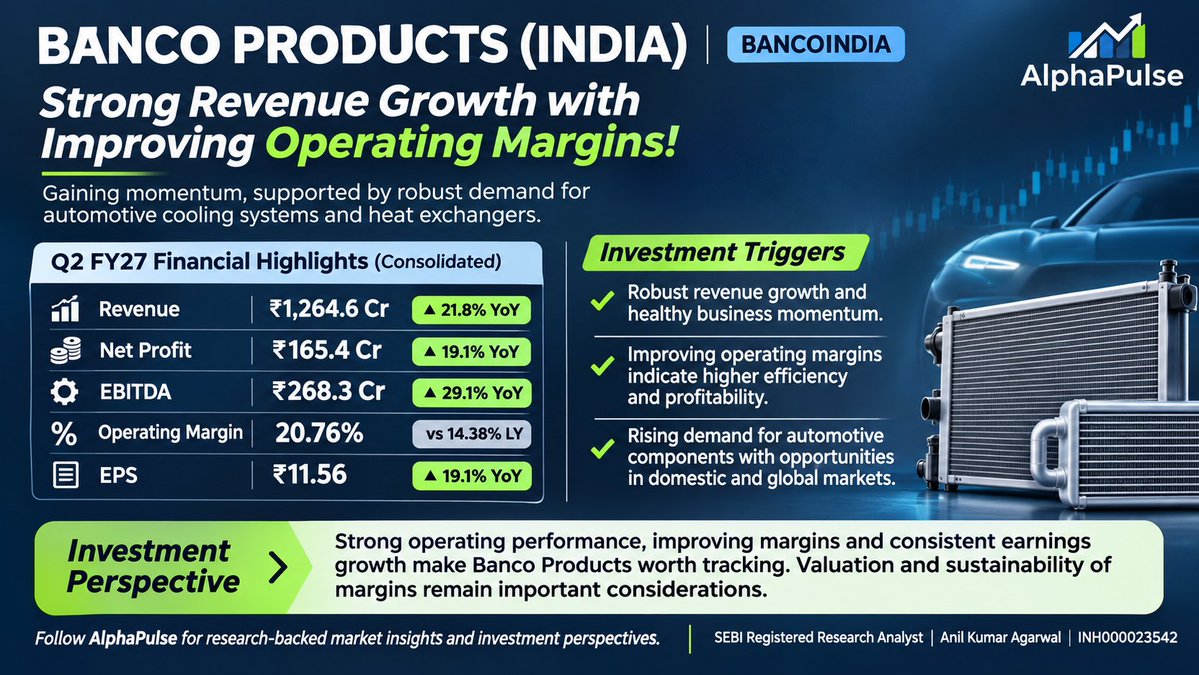
BANCO PRODUCTS (INDIA) | BANCOINDIA
Strong revenue growth with improving operating margins!
Banco Products is gaining momentum, supported by robust demand for automotive cooling systems and heat exchangers.
Q2 FY27 Financial Highlights (Consolidated):
Revenue: ₹1,264.6 Cr, up 21.8% YoY
Net Profit: ₹165.4 Cr, up 19.1% YoY
EBITDA: ₹268.3 Cr, up 29.1% YoY
Operating Margin: 20.76%, against 14.38% last year
EPS: ₹11.56, up 19.1% YoY
Investment Triggers:
Strong revenue growth reflecting healthy business momentum.
Improving operating margins indicate better operating efficiency and profitability.
Growing demand for automotive components, supported by opportunities in domestic and global markets.
Investment Perspective: Strong operating performance, improving margins and consistent earnings growth make Banco Products worth tracking. Valuation and sustainability of margins remain important considerations.
Follow AlphaPulse for research-backed market insights and investment perspectives.
SEBI Registered Research Analyst | Anil Kumar Agarwal | INH000023542
Waiting for the market to correct before investing? 📉
The perfect entry point may never come! Focus on a disciplined investment strategy, informed decisions and long-term financial goals.
Smart investing is about patience, knowledge and consistency. 📊
Start early. Invest wisely. Stay informed.
Follow AlphaPulse for research-driven investment insights.
#AlphaPulse #SmartInvesting #StockMarketIndia #InvestmentStrategy
Investments in the securities market are subject to market risks. Read all related documents carefully before investing.
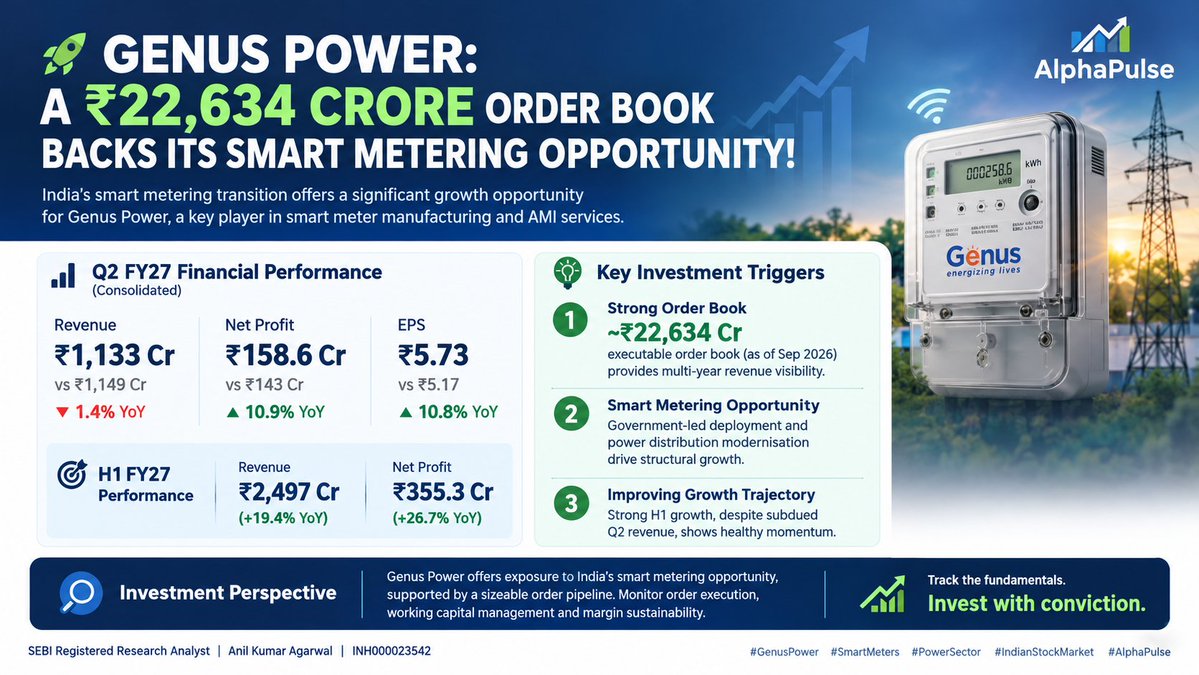
🚀 GENUS POWER: A ₹22,634 CRORE ORDER BOOK BACKS ITS SMART METERING OPPORTUNITY!
India's smart metering transition offers a significant growth opportunity for Genus Power, a key player in smart meter manufacturing and Advanced Metering Infrastructure (AMI) services.
📊 Q2 FY27 Financial Performance (Consolidated)
Revenue: ₹1,133 Cr vs ₹1,149 Cr (-1.4% YoY)
Net Profit: ₹158.6 Cr vs ₹143 Cr (+10.9% YoY)
EPS: ₹5.73 vs ₹5.17 (+10.8% YoY)
H1 FY27 Performance:
Revenue grew 19.4% YoY to ₹2,497 Cr.
Net Profit increased 26.7% YoY to ₹355.3 Cr.
💡 Key Investment Triggers
1️⃣ Strong Order Book: Executable order book of approximately ₹22,634 Cr as of September 2026, providing substantial multi-year revenue visibility.
2️⃣ Smart Metering Opportunity: Government-led smart meter deployment and power distribution modernisation provide a structural growth opportunity.
3️⃣ Improving Growth Trajectory: Strong H1 revenue and profit growth indicate healthy business momentum, despite relatively subdued Q2 revenue.
🔎 Investment Perspective: Genus Power offers exposure to India's smart metering opportunity, supported by a sizeable order pipeline. The pace of order execution, working capital management and margin sustainability remain key monitorables.
📈 Track the fundamentals. Invest with conviction.
SEBI Registered Research Analyst | Anil Kumar Agarwal | INH000023542
#GenusPower #SmartMeters #PowerSector #IndianStockMarket #AlphaPulse
⛏️ HINDUSTAN ZINC: RECORD PROFITS, STRONG MARGINS & SILVER-LED GROWTH!
Hindustan Zinc (NSE: HINDZINC) delivered an exceptional Q2 FY27, supported by higher metal prices, record production and improved cost efficiency.
📊 Q2 FY27 FINANCIAL PERFORMANCE (YoY)
Revenue: ₹15,093 Cr | +77%
EBITDA: ₹9,285 Cr | +108%
Net Profit: ₹6,412 Cr | +142%
EBITDA Margin: 62% vs. 52%
EPS: ₹15.20 | +142%
🚀 KEY INVESTMENT TRIGGERS
1️⃣ Silver Growth: Silver production increased 20% to 173 tonnes, while silver revenue surged 141% to ₹4,111 Cr, strengthening earnings diversification.
2️⃣ Cost Competitiveness: Zinc production cost declined 29% YoY to $703/tonne, supporting industry-leading margins and profitability.
3️⃣ Production & Diversification: Record mined metal production of 271 KT and refined metal production of 264 KT, alongside entry into rare earth minerals, provide additional growth opportunities.
💡 ALPHAPULSE VIEW
Hindustan Zinc's strong earnings growth, operational efficiency, cash generation and exposure to zinc, lead and silver position it well to benefit from favourable metal-market conditions. However, commodity price volatility, regulatory developments and high earnings cyclicality remain important risks to monitor.
📈 Quality fundamentals. Strong cash generation. Multiple growth drivers.
Follow AlphaPulse for research-driven investment insights.
SEBI Registered Research Analyst | Anil Kumar Agarwal | INH000023542
💎 IGI: Riding the Growth of the Global Diamond Certification Industry
International Gemmological Institute (IGI) delivered a strong Q2 FY27 performance, supported by robust demand for diamond and jewellery certification services.
📊 Q2 FY27 Financial Performance (YoY):
Revenue: ₹398 crore | +31%
EBITDA: ₹244.5 crore | +39%
EBITDA Margin: 61.4% | Up 340 bps
Net Profit: ₹185.8 crore | +43%
Certification Reports: 4.35 million | +26%
🚀 Key Investment Triggers:
Lab-Grown Diamonds: Certification revenue from LGD loose stones grew 37%, while LGD jewellery surged 47%, reflecting rising adoption.
Strong Competitive Position: IGI's global certification network, established brand and industry expertise provide competitive advantages.
Diversified Growth: Opportunities across natural diamonds, lab-grown diamonds, jewellery and coloured gemstones, supported by international expansion.
Investment Perspective: Strong revenue growth, expanding margins and healthy profitability highlight IGI's scalable business model. Its ability to capitalise on the evolving global diamond and jewellery industry makes it an interesting company to track, subject to valuation and business risks.
What is your view on IGI's growth prospects? Share your thoughts!
SEBI Registered Research Analyst | Anil Kumar Agarwal | INH000023542
Should you invest in an IPO just for the hype? 📈
Look beyond subscription numbers and listing gains. Evaluate fundamentals, valuation & long-term growth before investing.
Research over hype. Invest wisely!
SEBI Registered Research Analyst | Anil Kumar Agarwal
Reg. No.: INH000023542
#AlphaPulse #IPO #SmartInvesting
🚀 PNB: STRONG PROFIT GROWTH, IMPROVING ASSET QUALITY & RISING CREDIT DEMAND!
Punjab National Bank is showing improving fundamentals, supported by healthy loan growth, higher profitability and continued improvement in asset quality.
📊 FINANCIAL PROOF – Q2 FY27
Net Profit: ₹5,532 Cr, up 12.8% YoY.
Net Interest Income: ₹11,601 Cr, up 10.8% YoY.
Global Advances: ₹13.41 lakh Cr, up 14.7% YoY.
Global Business: ₹31.18 lakh Cr, up 11.9% YoY.
Gross NPA: Improved to 2.55% from 3.45% a year ago.
Net NPA: Declined to 0.25% from 0.36%.
Global NIM: Improved to 2.58% from 2.50% in the previous quarter.
🎯 KEY INVESTMENT TRIGGERS
Accelerating Credit Growth: Strong growth in advances, particularly retail and MSME lending, provides opportunities for business expansion.
Improving Asset Quality: Declining NPAs and a healthy 97.32% provision coverage ratio strengthen the bank's risk profile.
Sustainable Profitability: Double-digit NII and profit growth, supported by improving margins, indicate strengthening earnings momentum.
📈 INVESTMENT OUTLOOK
PNB's improving balance sheet, healthy credit growth and better asset quality position it to benefit from India's expanding credit demand. Continued monitoring of margins, credit costs and deposit growth remains important.
What is your view on PNB's growth prospects?
SEBI Registered Research Analyst | Anil Kumar Agarwal | INH000023542
Source: PNB Q2 FY27 Results and Investor Presentation, quarter ended September 30, 2026. Figures are YoY unless otherwise stated. Investment involves market risks.
🏗️ Welspun Corp: Riding the Global Infrastructure & Energy Opportunity
Strong execution meets growing demand! Welspun Corp (WELCORP) reported 30% YoY EBITDA growth in H1 FY27, with ROCE at 22.7% and a record global order book of approximately ₹50,000 crore.
📊 Why we added it:
• Strong global presence and manufacturing capabilities
• Growing demand for steel pipes across energy and infrastructure
• Capacity expansion in the US and entry into Jordan
• Improved financial position and strong revenue visibility
🔍 We remain focused on execution, profitability and valuation discipline as the company pursues its growth opportunities.
Welspun Corp joins the portfolio as part of our research-driven investment strategy.
SEBI Registered Research Analyst | Anil Kumar Agarwal | INH000023542
A strong portfolio is built on research, discipline and smart asset allocation. 📊
Understand your goals, assess your risk appetite and diversify wisely. Invest with a strategy, not just tips.
Make informed investment decisions with AlphaPulse.
Anil Kumar Agarwal | SEBI Registered Research Analyst
Registration No.: INH000023542
#AlphaPulse #SmartInvesting #PortfolioManagement #WealthCreation
📉 Bear Markets Teach What Bull Markets Cannot!
Shankar Sharma highlights three timeless investing lessons:
1️⃣ Recognise the bear market: Protect capital before chasing returns.
2️⃣ Wait for confirmation: A market recovery doesn't automatically signal a new bull run.
3️⃣ Think differently: Balance bearish and bullish views across market segments instead of following one broad market view.
🎯 The key takeaway: Discipline, flexibility and capital preservation build long-term investing success.
👉 Read, reflect and invest wisely.
SEBI Registered Research Analyst | Anil Kumar Agarwal | INH000023542
FRESH ISSUE vs OFS IN AN IPO 📊
Where does your IPO money actually go?
A Fresh Issue brings funds to the company, while an OFS allows existing shareholders to sell their shares and receive the proceeds.
Understand the difference before you invest. Make informed decisions, not hype-driven ones!
Follow @AlphaPulse for more market insights.
#IPO #FreshIssue #OFS #StockMarket #Investing #AlphaPulse
📊 Bosch Q2: Strong Growth, But Margins Under Pressure!
Revenue surged 28.2% to ₹7,655 crore, while net profit rose 18.6% to ₹839 crore.
🔍 Key Highlights:
EBITDA up 23.2% to ₹1,037 crore.
EBITDA margin declined to 13.5% from 14%.
Profit includes a ₹130 crore one-time gain.
3:1 bonus issue and 1:5 stock split approved.
📈 Track sustainable growth, margins and earnings quality beyond headline numbers.
👉 Read the results before making investment decisions.
SEBI Registered Research Analyst | Anil Kumar Agarwal | INH000023542
👀 Stocks to Watch Today – November 6
📊 Bharti Airtel, Titan, ONGC, Bharti Hexacom, Astral and others are in focus.
🔍 Track key announcements, corporate developments and trading cues before making investment decisions.
👉 Read the full list: https://t.co/oHOML5DewM
SEBI Registered Research Analyst | Anil Kumar Agarwal | INH000023542
🛢️ Oil Prices Plunge Over 9%: Is an Iran Peace Deal in Sight?
WTI crude fell below $88 per barrel after Democrats won control of both chambers of the US Congress, raising hopes of de-escalation in the Iran conflict.
📊 What investors should watch: US-Iran negotiations, global oil supply and geopolitical risks.
Could lower crude prices ease inflation and benefit oil-importing economies like India?
👉 Track developments and their impact on markets.
SEBI Registered Research Analyst | Anil Kumar Agarwal | INH000023542
🔋 India’s Battery Boom: A New Opportunity for Chemical Companies?
India’s growing battery ecosystem is creating opportunities for chemical manufacturers, with two companies expanding into battery materials.
📊 What matters? Track capacity expansion, order visibility, execution and sustainable margins.
Can growth translate into profitable businesses?
👉 Read the full analysis: https://t.co/RYsrCZnn6t
SEBI Registered Research Analyst | Anil Kumar Agarwal | INH000023542
SEBI Registered Research Analyst | Anil Kumar Agarwal | Registration No.: INH000023542
🇮🇳 INDIA’S IPO BOOM: ARE INVESTORS LOOKING BEYOND THE HYPE?
A promising IPO doesn’t always mean a promising investment.
Beyond the hype and headlines, investors should assess business fundamentals, financial performance, cash flows, valuations and growth prospects before applying for an IPO.
📊 Because successful investing isn't about getting in early — it's about understanding the business, its valuation and its risks.
Follow AlphaPulse for insights that help you look beyond the market noise.
Disclaimer: This content is for educational purposes only and should not be considered investment advice.
#AlphaPulse #IPO #IndianStockMarket #Investing #StockMarketIndia #FinancialLiteracy #InvestorAwareness
SEBI Registered Research Analyst | Anil Kumar Agarwal | Registration No.: INH000023542
🇮🇳 India’s IPO boom is attracting investors, but are they looking beyond the hype?
📊 Valuations, fundamentals & long-term growth matter more than headlines. Invest informed, not impulsively.
#IPO #IndianStockMarket #Investing #AlphaPulse