अचानक हार्ट अटैक आने पर 7 रुपये की ये सबसें सस्ती किट अपने जेब, पर्स, घर, दुकान, और कार्यालय की अपनी दराज में हमेशां अपने पास रखें, क्योंकि ये देखने में आ रहा है कि आजकल अचानक और पहली बार आ रहे हार्ट अटेक में लोगों को अस्पताल पहुंचने तक का समय भी नहीं मिलता,और जान चली जाती है !👇
A Big Appreciation post for CA Chintan patel sir !!
Sir has created a comprehensive webpage to assist Chartered Accountants with essential Tax Audit Resources. A one-stop destination for all the tools you need for Tax Audit Reporting and Compliance.
The webpage includes valuable resources like:
1.Draft Observations / Comments for Tax Audit Report (TAR)
2.Draft Reporting for ICDS
https://t.co/teGKxFYr3C Representation Letter (MRL) –
4.Draft Notes on Accounts, including Accounting Policies
5.Draft Comments for Sec. 43B(h) MSEs
6.And many other crucial tools!
Draft Observations / Comments for Tax Audit Report (TAR) is finest compiliation ever you will find .
As always , his Fantastic efforts for helping CA community at large
GO AND VISIT https://t.co/f7Aos0Ao0j
🚨 Indexation Restoration Alert - Part II
Working of Capital Gain Exemptions in New Scenario
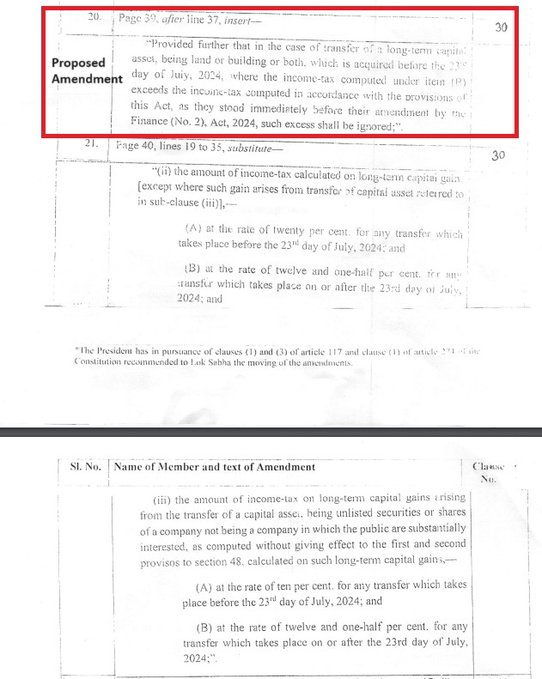
Indexation Benefit provided to only Resident Ind./HUF for Land/Building acquired before 23/07/2024 only for Tax Calculation Purpose, which means:-
1) Capital Gain to be mandatorily calculated as per new provision only i.e. without indexation which implies that for exemption u/s 54/54EC & 54F higher amount needs to be invested
Example!!
Sale of Land on 1st Aug 24 - 4 Cr
Purchase in 2001 - 1 Cr
Indexed Cost - 3.48 Cr
Capital Gain - 3Cr
Tax Calculation
New Prov. - 3Cr @ 12.5% - 37.50 Lacs
Old Prov. - 52 Lacs[4Cr-3.48Cr]@ 20%-10.40 lacs
As per Amendment in Finance Bills tax in excess of old provisions shall be ignored hence Tax Payable shall be 10.40 Lacs
📌BUT FOR AVAILING EXEMPTION OF ENTIRE CG U/S 54 , AMOUNT OF CG i.e. 3Cr needs to be Re-invested (and not just 52 Lacs)
💥If only 1 Cr is invested :-
Then 2 Cr (i.e. CG - Investment) shall be taxable as Capital Gain.
Now tax on 2Cr @ 12.5% - 25 Lacs
But shall be restricted to 10.40 Lacs (Old Provision)
Here we can see that Investment of 1Cr is not providing any Tax benefit via Sec 54
💥If 2Cr is invested, then also no benefit!!
💥If 2.5 Cr is invested:-
Then 50 Lacs shall be taxable as CG
Tax - [email protected]% = 6.25 Lacs
📌 Exemption u/s 54EC will also work in same manner
📌Now Exemption u/s 54F:-
💥If net consideration of 4 Cr is invested, then entire capital gain Exempt
💥If 2 Cr is Invested out of Net Consideration 4 Cr:-
Exempt Capital Gain = 3Cr *2Cr/4Cr = 1.5 Cr
Taxable CG = 1.5 Cr
Tax on 1.5 Cr = 1.5 Cr @ 12.5% = 18.75 Lacs
But the same shall be restricted to 10.40 Lacs (old Prov.)
Hence we can see No Tax benefit even on investing 2 Cr
𝗖𝗹𝗮𝗶𝗺 𝘆𝗼𝘂𝗿 𝗧𝗗𝗦 R𝗲𝗳𝘂𝗻𝗱 𝗯𝘆 𝗳𝗶𝗹𝗶𝗻𝗴 𝗙𝗼𝗿𝗺 𝟳𝟭
✅ As a general practice in filing of Income Tax Return (ITR), an assessee reports its income which was earned by it during the previous year and claims credit of TDS deducted on such income.
🚨However, for all these years there is some flaw in this process of claiming the credit of TDS. 𝐓𝐡𝐞 𝐟𝐥𝐚𝐰 𝐢𝐬 𝐰𝐡𝐞𝐫𝐞 𝐚𝐧 𝐚𝐬𝐬𝐞𝐬𝐬𝐞𝐞 𝐡𝐚𝐬 𝐫𝐞𝐩𝐨𝐫𝐭𝐞𝐝 𝐢𝐭𝐬 𝐢𝐧𝐜𝐨𝐦𝐞 𝐨𝐧 𝐚𝐜𝐜𝐫𝐮𝐚𝐥 𝐛𝐚𝐬𝐢𝐬 𝐢𝐧 𝐨𝐧𝐞 𝐲𝐞𝐚𝐫, 𝐡𝐨𝐰𝐞𝐯𝐞𝐫 𝐓𝐃𝐒 𝐡𝐚𝐬 𝐛𝐞𝐞𝐧 𝐝𝐞𝐝𝐮𝐜𝐭𝐞𝐝 𝐢𝐧 𝐬𝐮𝐛𝐬𝐞𝐪𝐮𝐞𝐧𝐭 𝐲𝐞𝐚𝐫 𝐨𝐫 𝐰𝐡𝐞𝐧 𝐧𝐨 𝐓𝐃𝐒 𝐡𝐚𝐬 𝐛𝐞𝐞𝐧 𝐝𝐞𝐝𝐮𝐜𝐭𝐞𝐝 𝐭𝐢𝐥𝐥 𝐭𝐡𝐞 𝐟𝐢𝐥𝐢𝐧𝐠 𝐨𝐟 𝐈𝐓𝐑 𝐨𝐟 𝐝𝐞𝐝𝐮𝐜𝐭𝐞𝐞 and same has been deducted and deposited belatedly or TDS return was being revised by the deductor subsequent to the filing of ITR by deductee, etc.; there comes a mismatch in TDS credit claimed in the ITR and TDS reflected in 26AS due to which assessee has to face a lot of problems.
✅ Earlier, as a solution to the above problem, assessee was supposed to revise its ITR (if due date was not surpassed) or to file an offline rectification application with the jurisdictional assessing officer (AO) to claim the refund of the excess TDS which was not reflecting in 26AS at the time of filing of ITR but reflecting after it due to various possible reasons
✅ The CBDT vide Notification dated 30.08.2023 has inserted e New Rule 134 -
𝐞𝐧𝐚𝐛𝐥𝐢𝐧𝐠 𝐭𝐚𝐱𝐩𝐚𝐲𝐞𝐫𝐬 𝐭𝐨 𝐟𝐢𝐥𝐞 Form 𝟕𝟏 𝐭𝐨 𝐞𝐧𝐚𝐛𝐥𝐞 𝐭𝐡𝐞 𝐚𝐬𝐬𝐞𝐬𝐬𝐞𝐞 𝐭𝐨 𝐦𝐚𝐤𝐞 𝐚𝐧 𝐚𝐩𝐩𝐥𝐢𝐜𝐚𝐭𝐢𝐨𝐧 𝐟𝐨𝐫 𝐫𝐞𝐜𝐭𝐢𝐟𝐲𝐢𝐧𝐠 𝐭𝐡𝐞 𝐚𝐬𝐬𝐞𝐬𝐬𝐦𝐞𝐧𝐭 𝐨𝐫 𝐢𝐧𝐭𝐢𝐦𝐚𝐭𝐢𝐨𝐧 𝐨𝐫𝐝𝐞𝐫 𝐚𝐧𝐝 𝐟𝐨𝐫 𝐚𝐥𝐥𝐨𝐰𝐢𝐧𝐠 𝐭𝐡𝐞 𝐓𝐃𝐒 𝐜𝐫𝐞𝐝𝐢𝐭.
✅ This application has to be made within a period of two years from the end of the financial year in which TDS has been deducted.
✅ Remember, the filing of Form 71 is exclusively online on the income tax portal.
Navigating tax laws can be tricky, so seeking assistance from a professional might be a wise choice!
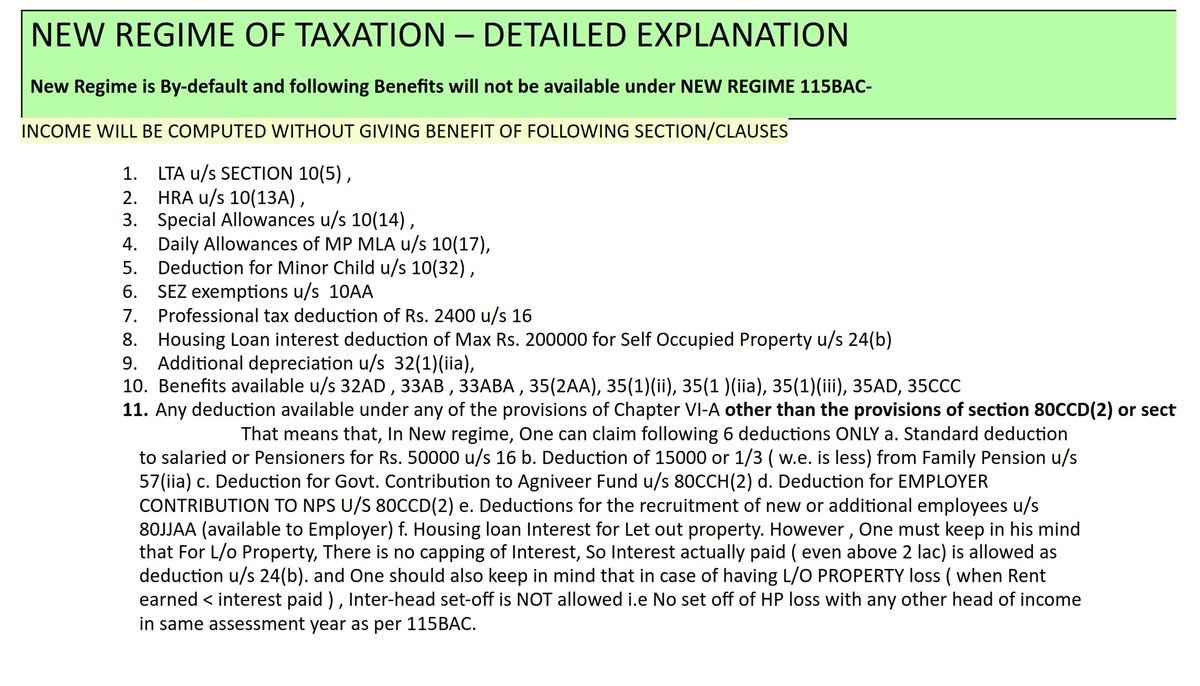
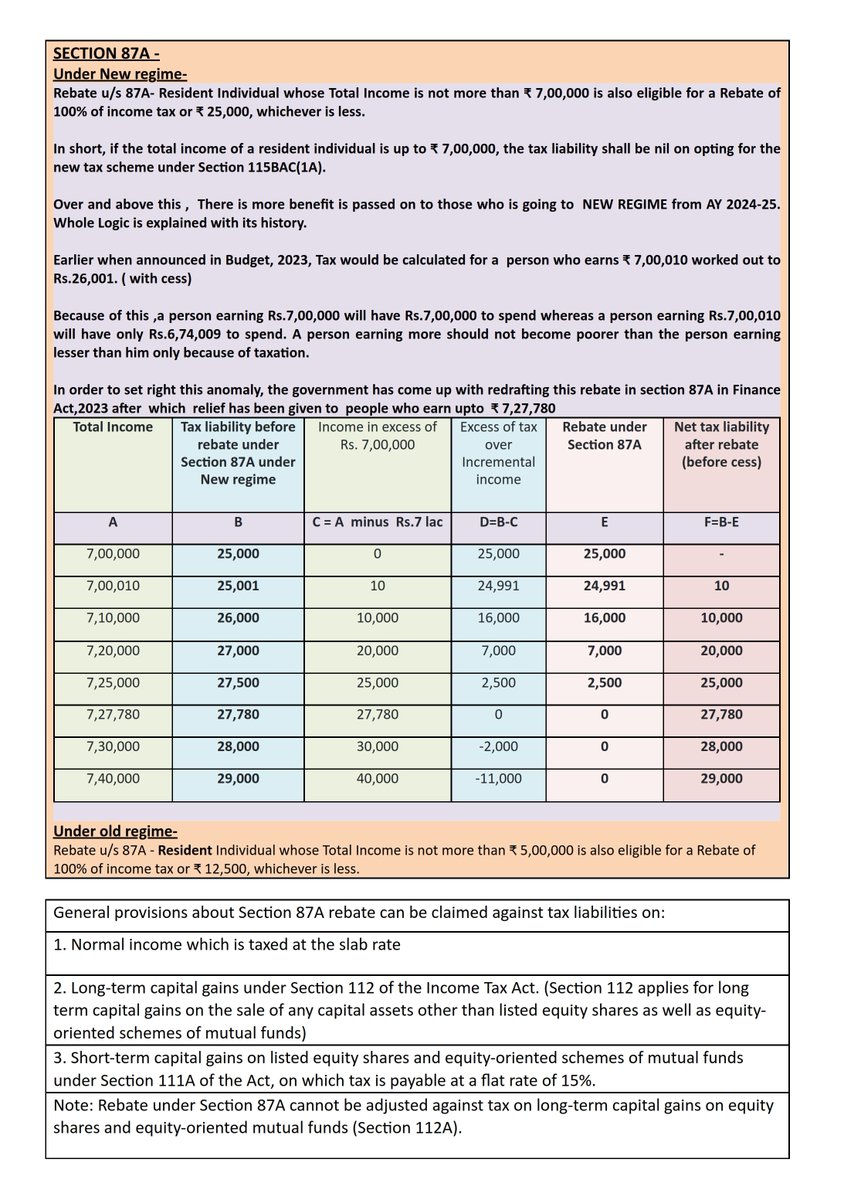
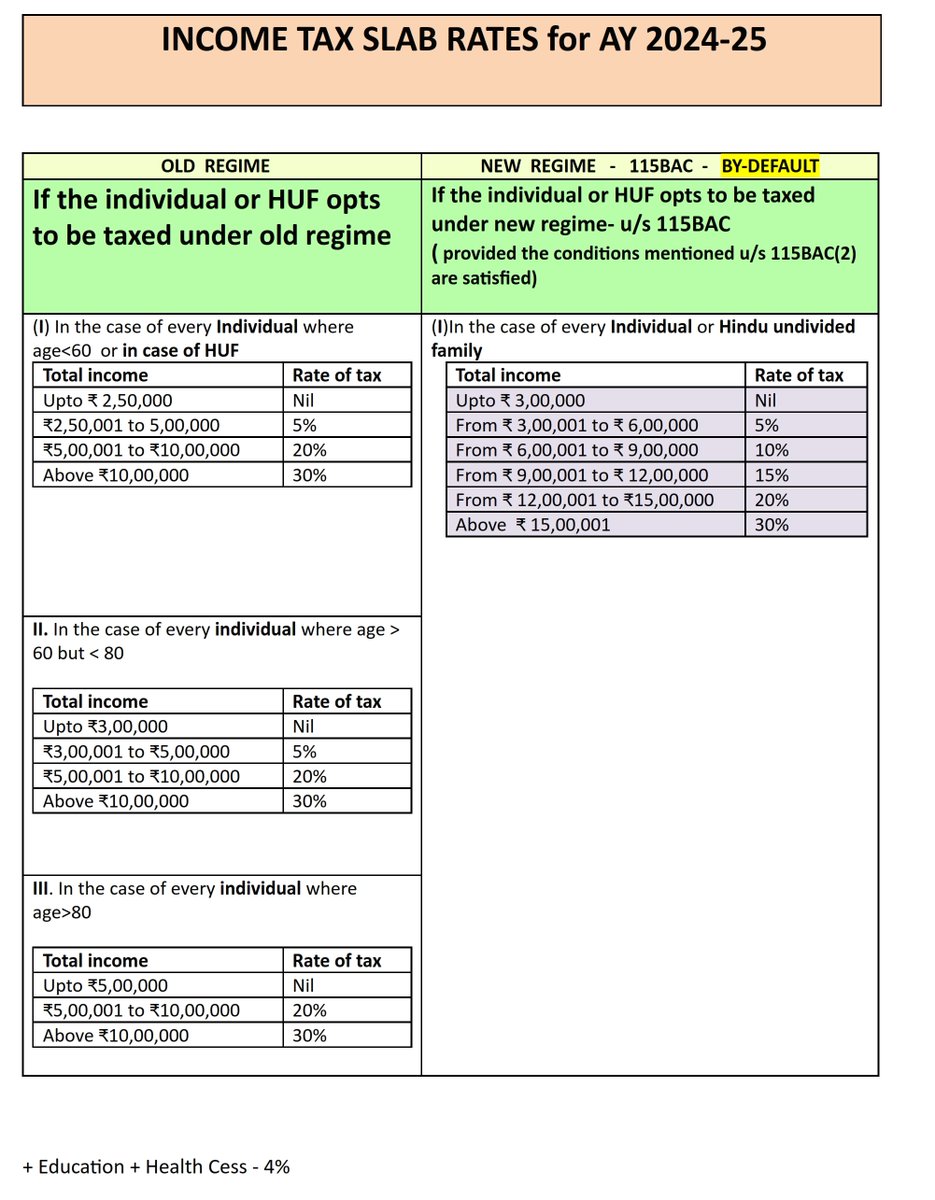
Everything about New regime for AY 2024-25 is answered
Slide -1- TAX slabs for New vs Old for AY 2024-25
Slide-2- 87A rebate for New regime
Slide -3 - New regime - List of Deductions not allowed as compare to Old
Slide-4- NEW vs Old comparison for diff. income level
Lots of people are asking ( Specially those in Job ) for year ending which is near, So here is all questions answered
PS- You can subscribe to https://t.co/ofQZRuCzVZ for whole Income tax summarise version as INCOME TAX READY RECKONER 2.0 E-BOOK