Are you republicans really sticking it out through this shit? I thought this guy was not going to start a middle eastern war and was going to have cheaper gas than Sleepy Joe? What happened?
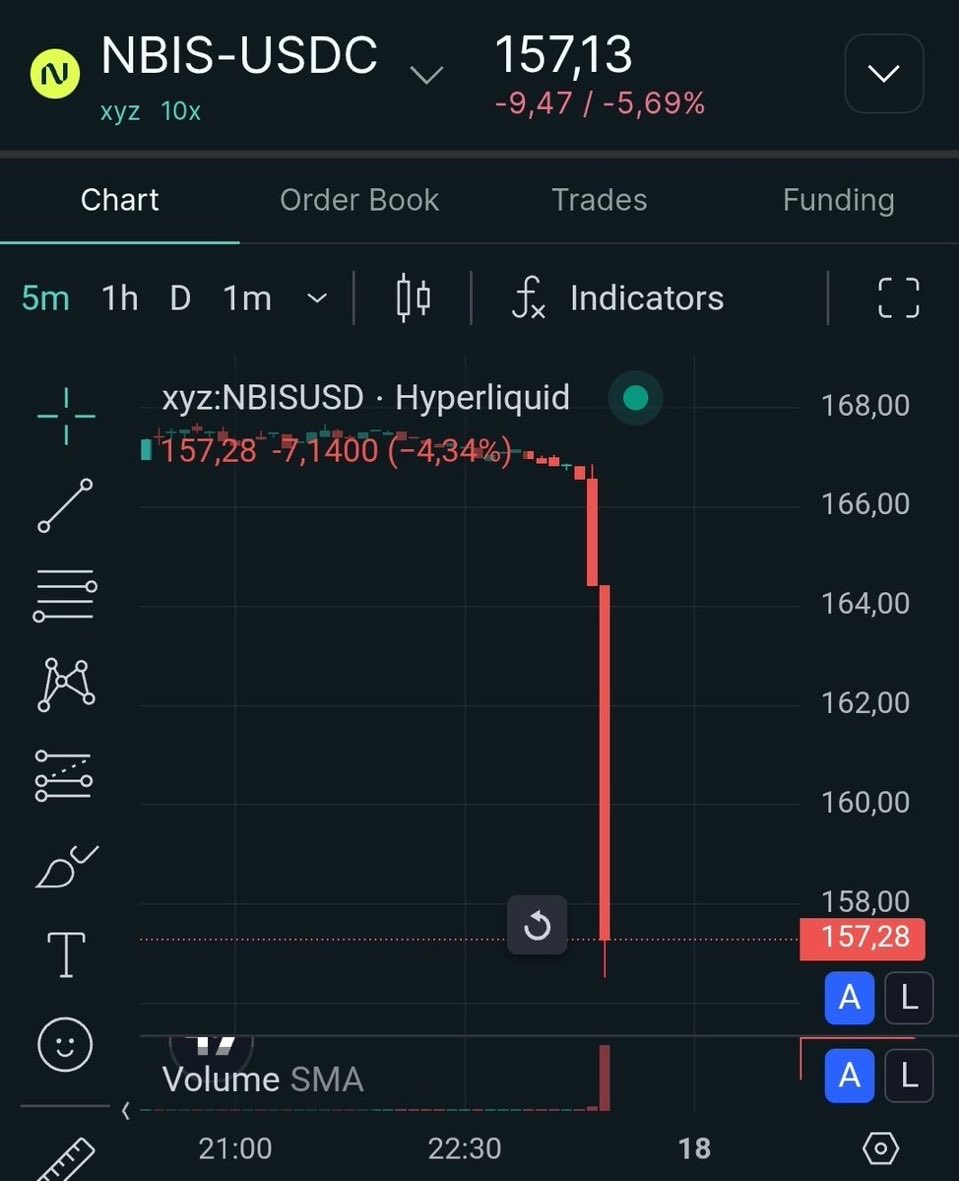
$NBIS Taking a step back after the drawdown
What I always do for my investments when they experience such a dramatic fall every time is take a step back and look at everything again over the weekend with a cool head, so as not to mix emotions and facts.
1) Thesis
First of all, I attach the updated thesis that I published at the end of September, and I think this is what you should go back to first, as it makes you remember all the verticals that the company is currently progressing on, and it shows you why I believed in the company in the first place (and still believe obviously)!
I believe that nothing has changed since September 2026, and many would argue that things even improved.
2) CapEx/Debt debate
A lot of things were said during this week regarding CoreWeave financials and their implications for the whole neocloud sector. I think it is fundamentally wrong to compare CoreWeave with Nebius and IREN, for example, because each company has a different strategy. In my opinion, the biggest problem for CoreWeave compared to these two is the fact that they sold out their whole 2027 capacity, and overall their deal profile is long-term contracts with terms that do not reflect the current prices. Combine this with their annual interest and potential difficulties to raise additional capital, and you have a problem.
I absolutely disagree with statements that if Nebius were to succeed, CoreWeave must succeed as well. However, that’s not what I really care about today, as I want to discuss Nebius as my biggest position. (Good luck to CoreWeave, as it would definitely be better if they managed to get out of this negative perception!)
So what is the current situation for Nebius?
If we assume the high end of the 2026 CapEx guidance - $25B and look at the gap between what Nebius already spent on CapEx and what is left to spend (we don’t really know what happened since June 30, so we have to work with that):
- CapEx spent in H1 2026 - $8.13B
- CapEx required to meet guidance - $25B
- 2026 Remaining CapEx (as of June 30) - $16.87B
What is the cash situation?
- Unrestricted cash on June 30 - $8.04B
- July secured debt facility - $0.775B
- August convertible financing - $5.75B
This gives us approximately $14.5B in cash and financing resources, which creates roughly a $2.3B gap to cover the remaining CapEx.
We also have to assume that Nebius wants to still finish the year with some unrestricted cash, so let’s assume the $8B similar to its June 30 position.
This means that Nebius needs ~$10.3B of additional net cash inflow during H2, and let’s discuss where they could get this money before people start with the FUD that we will get diluted or Nebius will take on an additional $10B of debt (trust me, they will eventually, you have to account for that).
2.1) Customer prepayments
Management expects more than $9B of upfront customer funding in 2026, but don’t forget that is for the entire year. If we look at the H1 cash-flow statement, we can see a $4.4B positive change in deferred revenue, so we don’t know for sure, but we can expect several billion dollars of additional customer funding arriving during H2, which helps significantly with this gap.
2.2) Operating cash generation
H1 operating cash flow was $109M, and I believe that we can expect at least $400M of operating cash flow in the rest of 2026. Nothing significant, but still almost half a billion dollars.
2.3) Additional asset-backed financing
People completely forget that this is actually the most important and plausible source of capital. Management said that more than $40B of additional customer commitments could support a similar financing structure to the $775M secured facility in July, where Nebius borrowed against deployed GPU infrastructure and contracted cash flows from investment-grade customers.
Overall, to maintain that $8B cash buffer, I believe Nebius still needs to find approximately $5-$6B of further financing excluding operating cash flow and customer prepayments, which we will know more after Q3 earnings (second week of November most likely).
Remember, $5-$6B of additional cash if they want to keep that financing buffer, but if they think that now is not the right time to seek capital, they are covered for 2026 despite what many tried to tell you during this week. So again, everyone panicking before double-checking the facts...
3) Mismatch between my expectations and the street’s consensus
Probably something that makes me most bullish still, and I keep going back to this number is the extremely slow progression curve that the street is expecting. To be fair, I am not surprised that the consensus right now is that Nebius is not a great investment if they expect them to announce $16B in ARR by the end of 2027.
I don’t know what the exact consensus on the active capacity at that time is, but with that estimate, I would be bearish as well, as the economics wouldn’t make much sense at that point, and this is where I believe the big re-rating will happen - Q3 earnings.
I believe many saw the post from @SMASIMHO, where he showed the least bullish base case you can ever see (on purpose), but I will repeat it, so you don’t have to switch between posts:
- 2026 ARR guidance is currently $7-$9B, and I will confidently say that we can assume the midpoint of $8B
- Already confirmed capacity for 2027 is 800MW, and that will most certainly be around 1GW, and in my valuation model, I currently assume 1,700MW of active power by the end of 2027
You can probably understand by now that $16B in ARR is complete nonsense because that would imply -> $9.4M/MW, which is below the bare-metal deals around $11-$12M/MW
I’ll just use my estimates of 1,700MW of active power and blended revenue per MW of $21.1M. First of all, I am already quite bullish in my base case, but we only see GPU prices increasing, and until I see actual cracks in the data, I won’t be lowering my expectations. For those who read my valuation model, I am way above $30B in exit 2027 ARR, but even if we assume my bear case of $25.8B, it would still be 61% higher than what the street is expecting - 61%
My next point would be whether the deals are actually profitable and how much FCF is actually generated, but I am preparing a longer article on this topic because many people apparently can’t do math on X (spoiler: a lot of FCF for Nebius).
So yeah, I am still calm and collected going into the next week and I would summarize it like this:
- No signs of demand slowing from Nebius
- Deals make sense economically
- Sentiment shifted, which is normal
- Thesis is still intact
- Pumped for Q3 results
Thanks for your attention!
And it gets even crazier. 🤯
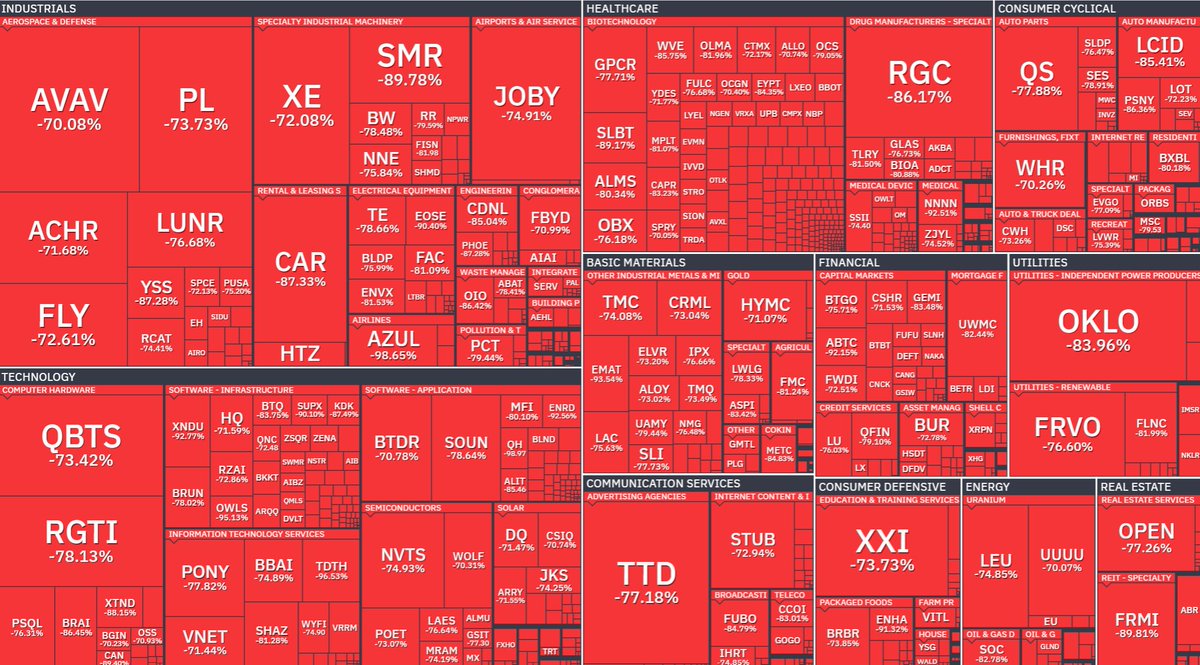
1,400 stocks are down 70%+ from their 52-week highs.
Let that sink in.
If you’re down 70%, you need roughly a 233% gain just to get back to breakeven.
@ShaneStoffer It’s been a brutal market especially lately it feels like. Moves reverse constantly, no sense of direction and long painful consolidations and then the move happens all at once in the span of 2 weeks. Sucks
@AjBorow *“Demand appears infinite”* 💉💦
*Nebius first access to Nvidia’s agentic powerhouse Groq 3 LPX* 💉 💦
*Q3 earnings will blow 2027 guidance out of the water* 💉💦
*Nebius will announces massive sovereign AI deal with the Middle East using Palantir’s partnership* 💉💦
@LuckyStuey What do you not get about MNOs not wanting to partner with SpaceX, a competitor? Give me one industry where there was a single company that won the entire market? Also, Europe and many countries have stated they will not work with SpaceX. You are one stubborn bear…
@eccometal And $nbis is finally touching below its 200 MA. Every time we’ve hit this has lead to a significant rally. That plus the setup of being a month out to earnings (used to be my favorite $NVDA setup) makes for a great risk-reward IMO. NFA (even though it is)
The market (SPY) bottomed pinned near a very important level at the lows today. Every time we’ve hit this level we have bounced significantly. Today we swept it and began recovering - beginnings of a failed breakdown. Semis and neoclouds have taken a relentless beating lately and…
The market is like swimming in the ocean and seeing a great white shark - if you see it coming, it’s not actually there to hurt you.
It’s when you don’t even know what happened and it surprises you from nowhere that is the real danger. 🦈
@AdamMancini4 My X is filled with talk of Black Monday… I feel like we’ve seen this tape before and people are always surprised. Markets like a shark - if you see it coming, it’s probably not actually attacking you! The worst is when it hits you from below and you’re blindsided. 🦈