The listing price is not the same as the acquisition price, nor is it necessarily the final sale price. It cannot be used as a measure to determine where the company makes or loses money. That column simply tracks the cumulative price change over time relative to the original listing price.
In some cases, a combination of large price reductions and long holding periods may provide a rough indication, but even then it's difficult to draw reliable conclusions. Products such as CNML also help mitigate part of that risk, making it even harder to assess profitability based solely on listing price movements.
@budd545304@MMTLP4ME88 Maybe in the future, Opendoor will charge furniture vendors a commission when buyers purchase the furniture and home showcased in the virtual staging.
I think makes sense this type of partner.
@budd545304@MMTLP4ME88 On some Zillow listings, they’re already using a toggle that lets users switch between different furniture styles. It’s only a matter of time before Opendoor adds it to its website, just as it previously did with 3D Tours.
https://t.co/a94IGG8v26
I think the 3P product is precisely about that. Uber attracts drivers because it brings them customers, Amazon attracts delivery partners because it brings them customers, and Steam attracts developers because it brings them customers. The idea is the same because they are all platforms: that Opendoor attracts agents because it brings them customers, even though acquiring those customers is a task that requires significant effort.
we recently shipped a big change to how you get started selling your home with Opendoor.
~35% less time to get to your estimated value means
~40% more people reach their estimated value and
~15% more people finish their home walkthrough
left (old), right (new)
Great work $OPEN Army. Few points about the space today:
1) Grateful that Kaz accepted the invitation and joined us for a Q&A.
2) Huge thanks to everyone who attended the space and helped with the shares count tally. You’re the best!
3) Apologies to whoever sent a request to come up as speakers in the first 30 mins of the space, and it was not accepted. The plan was to focus only on Q&A with Kaz while we had him and only accept speaker request from current Opendoor board members. I sent an apology to Mike. That was my bad not to see him in the audience early in the space. Otherwise, I would have invited him to come up to the stage.
4) Acknowledging who asked question was the part that we didn’t want to skip and we wanted to give credit. We received good feedback, and we do it differently next time to have more time to focus on actual questions.
5) That was our first time speaking to a public company CEO, and we can only do better next time.
6) Remaining questions will be sent to Kaz to review, and hopefully he would address as many as possible. We’d like him to focus on what matters most; building a generational company
7) We have monthly spaces; the last weekend of each month (usually Sunday) and daily spaces to chat about Opendoor.
8) We have group chat where we discuss Opendoor. Please reach out if you can’t find the link. It’s been shared under the space I believe.
2) Last but not the least, I’m long $OPEN. And none of this you hear here or in any of our spaces is financial advice. You must do your own due diligence before investing.
Typically CM is higher during the spring because newly acquired homes tend to spend less time in inventory before being sold. It's the liquidation of the older inventory tail that ultimately weighs on CM in Q3 and Q4. I don't believe the issue is that Opendoor is overpaying for homes, but rather that the pool of buyers remains constrained by elevated mortgage rates.
I think products such as 3P, CNML, Own, and the company's other newer offerings are valuable because they help protect the business in an unfavorable macroeconomic environment by reducing the burden of carrying inventory. However, in a more favorable macro environment, I would expect the core iBuying model to perform better.
A few points I'd like to highlight regarding the past few days:
- I think Opendoor chose not to provide direct Contribution Margin (CM) guidance for Q4 because it is more difficult to forecast than revenue. Over the last quarters, CM has come in below management’s guidance. For Q3, the forecast was 4.0-4.5%, yet the company reported 3.3%. A similar situation occurred in Q1, management indicated it would be the strongest CM since Q2 2024, which implied a range of roughly 4.7-6.0%, but it ultimately came in at 4.4%.
That said, the company's AVG CM for the year currently stands at 4.5%, which is not bad. Even if Q4 brings that figure down and the annual average ends up closer to 3%, it would still be in line with 2025 levels while supporting a larger inventory base. The tighter the CM, the more inventory volume you need to transact.
- I believe last Friday's sharp selloff was driven by a combination of factors. In the risk section of the 10-Q, the company stated that it cannot guarantee it will not be classified as a "large institutional investor." Based on the legislation written in July, it arguably should not fall under that definition. However, the ambiguity introduced by the Treasury's draft guidance published in October has left the situation unclear, and the company itself acknowledged that it is closely monitoring how the rules are ultimately finalized.
I think retail investors are generally more comfortable with language such as "no assurance" than institutional investors and funds, even when the most likely outcome remains favorable for the company.
On top of that, stock-based compensation (SBC) continues to be a frequent point of criticism among both algorithms and investors discussing the company. Looking at the financials from the outside, it's easy to see why many people focus on the annual net loss figure, which is heavily impacted by SBC expenses. That is not to say the company is not currently losing money, but rather that the accounting presentation makes those losses appear significantly larger than the underlying economic reality.
- It's also worth remembering that the company has only been in rebuilding mode for about a year. That's a very short period of time to evaluate execution. I wouldn't even classify the major declines in the stock price as evidence of poor execution. The entire real estate sector has been under pressure due to macroeconomic conditions. This is a structural issue affecting the industry as a whole, not something unique to Opendoor.
I think the most important takeaway from these latest earnings isn't the numbers themselves, but what has happened over the last few months. The ability to roll out new software and iterate on it so quickly is incredibly valuable. Not every product they launch will be perfect or even successful, but having the capability to test ideas rapidly because they can build and deploy them in such a short amount of time is tremendously underrated.
I haven't watched the full earnings call yet, but I'll finish it this weekend. The numbers are consistent with what Kaz said was going to happen. The pricing concessions have resulted in lower revenue. My tracker estimated approximately 2,543 homes sold at an average price close to $385K, while the final reported average, based on 2,728 homes sold, came in closer to $370K. This could happen again in Q4, which is why I believe management was more conservative with its Q4 guidance.
For now, the tracker points to a potential floor of $1.15B in revenue, but actual revenue has consistently come in above that floor due to revenue sources beyond home sales alone, as well as homes that were not detected by the tracker.
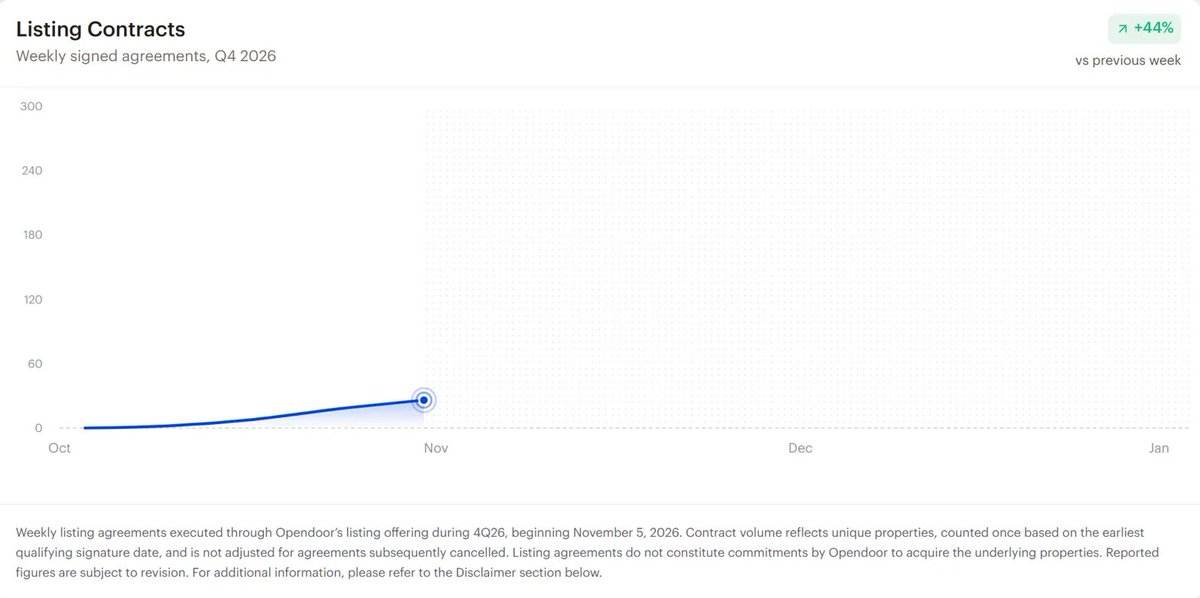
In Accountable, they have added the listing contracts they have secured, where Opendoor does not purchase the property but simply lists it for sale. It's important to keep in mind that if one of these properties sells, the revenue will not include the full value of the home. Because of that, the tracker will need to be updated to avoid misinterpreting revenue figures. The volume is still relatively low, so the impact should not be significant for now. However, as volume grows and these properties become increasingly mixed with homes that are actually carried on Opendoor's balance sheet, discrepancies are likely to emerge.
Today, we’re introducing the Aven Home Purchase Line. Go from open-house to owning a home in 7 days.
Buying a home with a mortgage used to mean finding the right place, then waiting weeks for financing to catch up - this process is broken.
At Aven, we’ve spent a lot of time thinking about how to build new financial products and make them an order of magnitude better for consumers. The mortgage has been one of the hardest and clunkiest products for decades, so we created a new way to buy a home.
We’ve already helped someone become a first-time homebuyer in Tucson in 67 hours. Thanks to @morganb , @nejatian , @BradBonney ,and our friends at @Opendoor for helping make this possible!
Read more in Forbes: https://t.co/ABUGvNnj1E
Aven Financial, Inc. NMLS #2042345. Accounts are made by Coastal Community Bank, Member FDIC. NMLS #462289. Equal Housing Lender.
I've also added a dedicated button below each chart, making it easier to capture and share screenshots on X and other social media platforms.
Like this 👇👇, if you're looking for the data behind a specific date on a chart, simply click/tap on the data point and it will remain pinned to copy/share.
Completed a mobile redesign of the tracker and added a new chart that shows how active listing age buckets have evolved over the past two months.
With Q3 earnings now just one week away, I believe the recent trends in the tracker suggest Q4 guidance will exceed $1.2B, potentially reaching around 3,200 homes sold.
As Opendoor continues to roll out new products, it is gradually moving away from the traditional CM/rotation relationship. Obviously, rotation remains one of its core characteristics, but a tracker could mistakenly assume that a home listed for more than 120 days is losing money when that may no longer be the case.
All of these products reduce the percentage of interest Opendoor pays on each property, and in some cases, such as the 3P model, I assume they may eliminate it entirely. Over the past two months, they've been moving very quickly to launch new products.
A few days ago, we launched our first iteration of our 3P product: List with Opendoor. Some folks noticed and posted screenshots of it here on X.
It is early days, but I'm very happy with its progress.
@operdoor2@Davo0820@HHGF99 A percentage of those homes aren't actually relistings. Sometimes they're simply updates, renovations, or sales that were completed at a later date. However, over time, everything tends to stabilize.
Many have tried to read the tea leaves this way.
Arizona tax records and recording will show you the purchase price, not the net.
For example - my wife and I bought our home for ~$720K in March. Topline price and that’s what records w/ county.
What it doesn’t show: (cont..)
I believe Q3 will come in between $1.04B and $1.08B due to the decline in CM during August. However, in my tracker I've decided to keep the adjusted estimate at $1.13B, because the delisted sale price != to the final negotiated sale price.
I prefer to use the delisted sale price, as it is more closely aligned with public data than with private data.