Payments built for businesses that need more flexibility.
High-Risk • Ecommerce • Recurring • Multi-Currency
Merchant accounts, gateways & integrations.
Payment processing built for growing and complex businesses.
High-Risk • Ecommerce • Recurring • Multi-Currency
Merchant accounts, gateways & integrations.
Looking for a better setup?
https://t.co/6GtuKoTOsn
Before Black Friday, buy from your own store on a real phone and make the payment fail on purpose.
Declined card. Timeout. Back button. Double tap.
Does your customer get a clear message, a retry, and the same cart? Or a dead end?
#BFCM#Ecommerce
Payouts paused for review in Q4? Have the file ready first: owner ID, business registration, proof of address, supplier invoices, tracking records, and a note on what changed. Make names and addresses match everywhere. #BFCM#PaymentProcessing
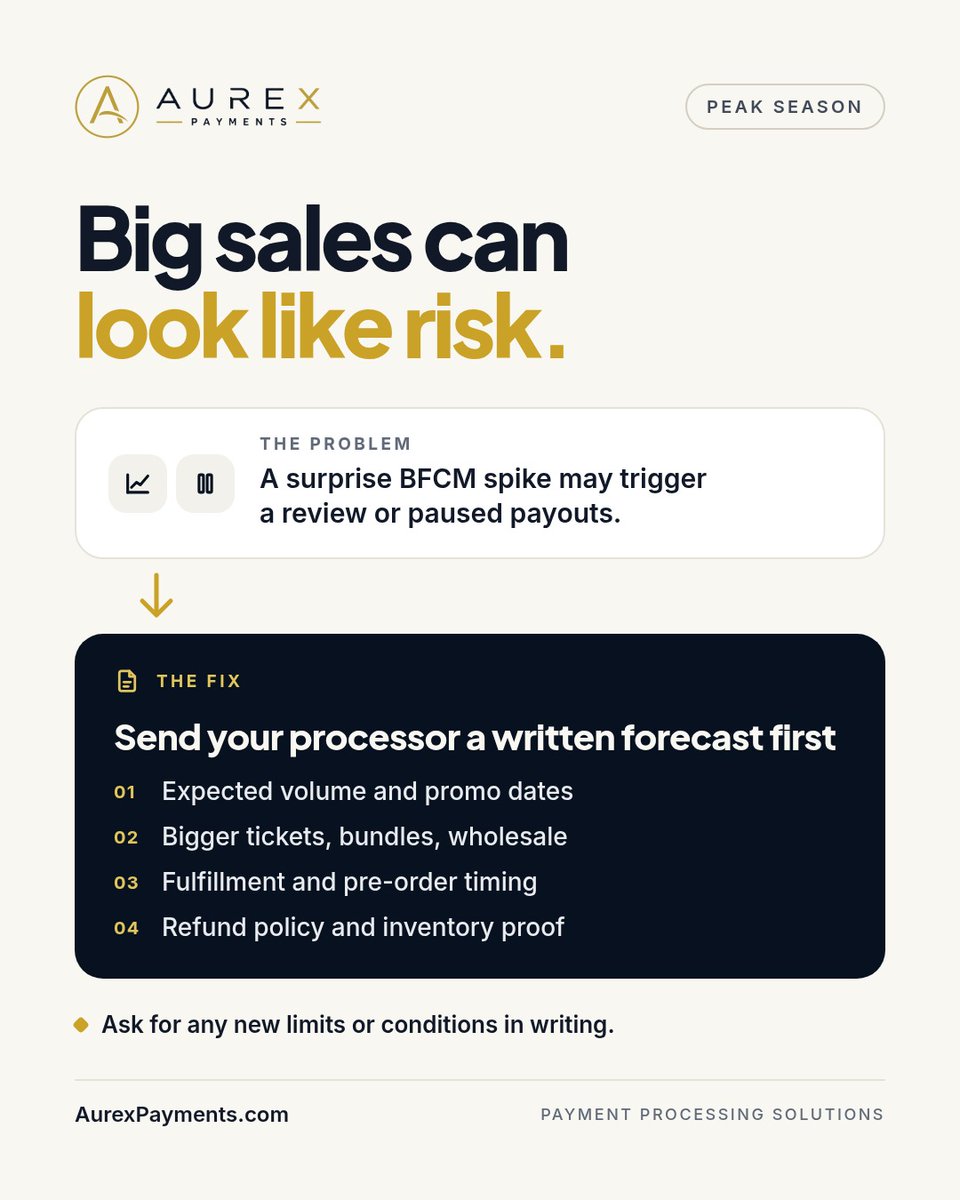
A record BFCM weekend can look like a risk event to your processor. Before the rush, send a written forecast: volume, promo dates, ticket size, fulfillment timing, refund policy. Then get any new limits in writing. #BFCM#PaymentProcessing
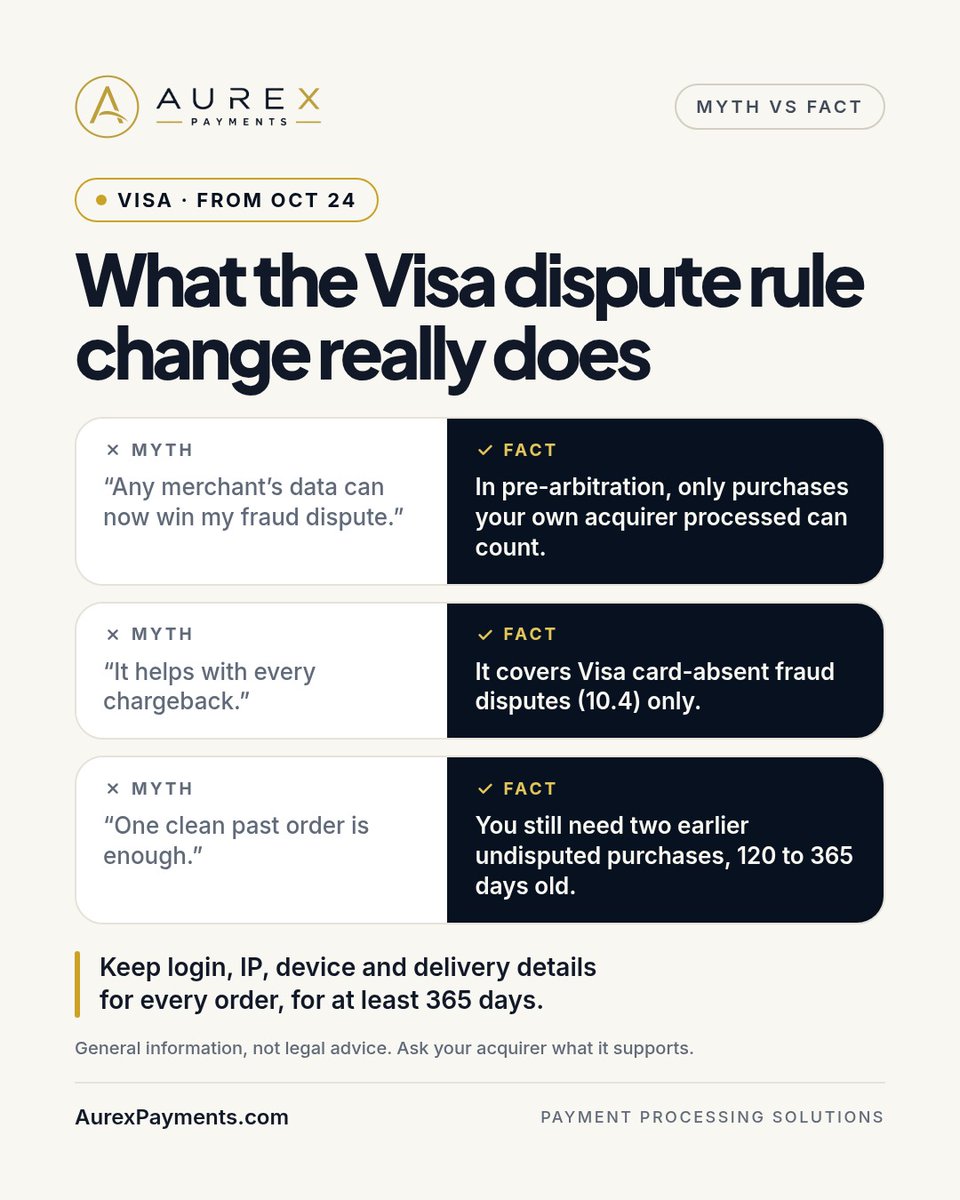
Visa's CE 3.0 widens Oct 24: earlier purchases at other merchants can count in 10.4 fraud disputes. Still fraud-only, still 2 undisputed purchases (120–365 days), and in pre-arb your acquirer can only use data it processed. Keep IP, device and login data. #Chargebacks
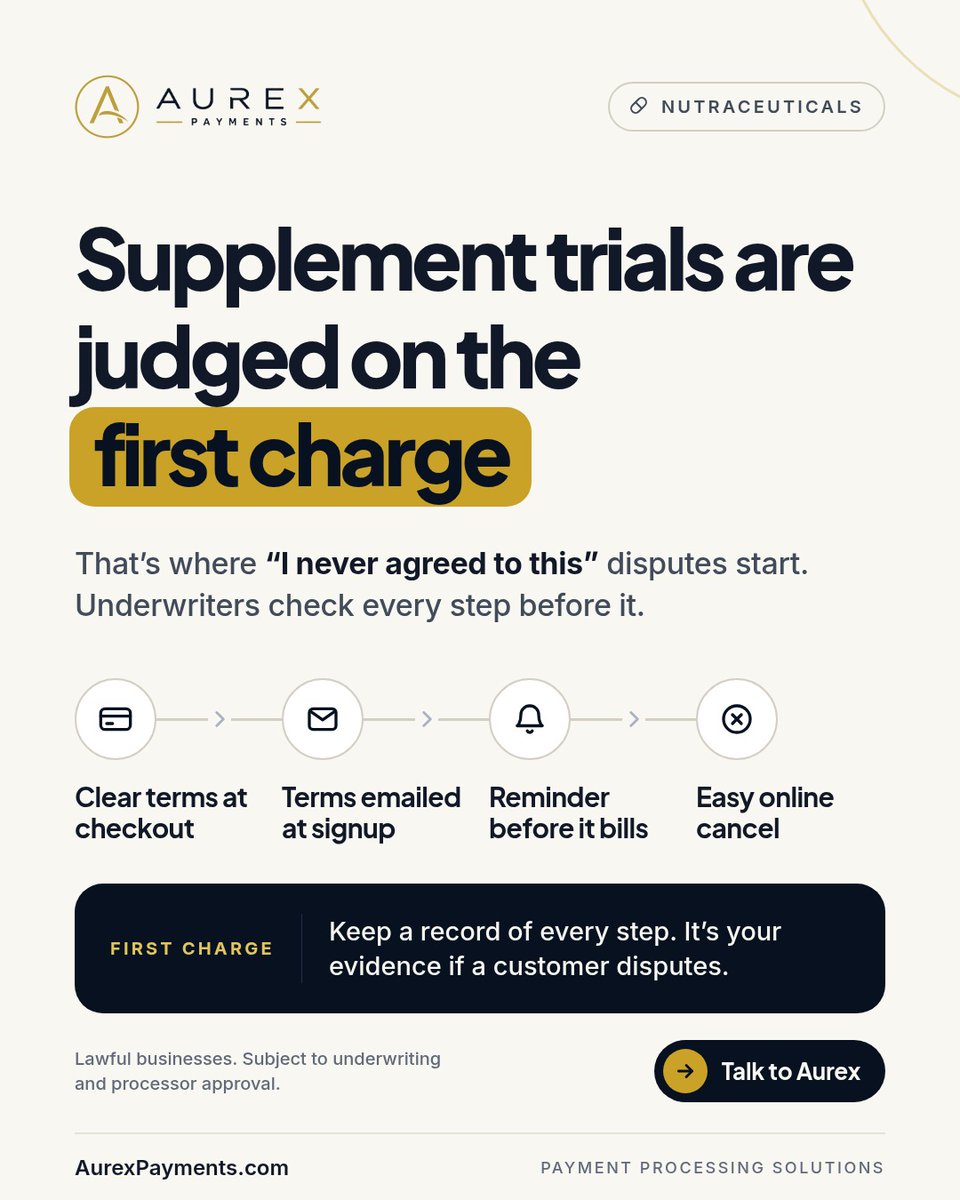
Supplement trials are judged on the first charge. Before a Black Friday trial or auto-ship offer: clear terms at checkout, terms emailed at signup, a reminder with a cancel link before it bills (Visa: 7+ days), easy online cancel. Keep records. #Nutraceuticals#Chargebacks
Tiny declines at 3 a.m. aren't noise. Card testing shows up as many cards from one device, $0 or tiny auths, and repeat CVV fails. Before Black Friday: CAPTCHA on checkout, velocity limits, CVV/AVS on, and a decline-spike alert. #FraudPrevention#Ecommerce
From Oct 23, Mastercard renewals and other merchant-initiated charges need the TLID from the customer's original transaction.
Migrated your card vault or run renewals on a backup MID? Ask your provider if it has the TLID for every stored card.
https://t.co/6GtuKoTOsn
Visa adds decline code 57 ("transaction not permitted to cardholder") to its never-retry list on Oct 25. Retrying it can trigger network fees. If you run recurring billing, check that your dunning logic stops on 57 and ask who pays reattempt fees. #RecurringBilling
Processors are being pushed to screen harder. September's FTC processor orders bar misleading applications and "load balancing" (splitting volume to hide chargeback rates).
Best move: an accurate file, every account disclosed, a verifiable address.
#MerchantAccounts#KYB
A cold backup MID that spikes on Black Friday can look like risk to underwriting.
Warm it with live volume now. Tell both processors your BFCM plan in writing. Test failover before Nov 27.
https://t.co/6GtuKoTOsn
Chargeback alerts generally only cover disputes started after you enroll, and setup can take days or weeks.
If Black Friday matters to you, start now: pick your alert programs, name who answers them (often a 24–72h window), and set a refund rule.
#Chargebacks#BFCM
If your statement name ≠ the brand at checkout, buyers dispute it — and it often codes as fraud.
Match storefront, DBA, and live descriptor. Test a real card. Align pending vs settled.
#BillingDescriptors#Chargebacks
A new reserve letter after a volume spike is usually a risk review on a live MID — not a freeze.
Read rolling vs capped vs held funds. Reply with shipping + descriptor proof. Warm a disclosed backup path while batches settle.
Subject to underwriting. https://t.co/6GtuKoTOsn
A new reserve letter after a volume spike is usually a risk review on a live MID — not a freeze.
Read rolling vs capped vs held funds. Reply with shipping + descriptor proof. Warm a disclosed backup path while batches settle.
Subject to underwriting. https://t.co/6GtuKoTgCP
Oct 15: MATCH Pro inquiries add a merchant risk score + site/network signals. A listing is info for underwriters, not an auto-ban. Get reason code + add date in writing. https://t.co/6GtuKoTgCP
Oct 15: MATCH Pro inquiries add a merchant risk score + site/network signals. A listing is info for underwriters, not an auto-ban. Get reason code + add date in writing. https://t.co/6GtuKoTOsn
Gateway chargeback % ≠ Visa VAMP ratio.
VAMP uses qualifying fraud + disputes vs settled CNP Visa sales. Excessive Merchant (US/CA/EU/AP): 1.5% since Apr 1 2026, with count rules.
Ask your acquirer for the Visa numerator — not only the dashboard.
https://t.co/6GtuKoTgCP
Visa's Compelling Evidence 3.0 rule for "I didn't authorize this" disputes changes Oct 24. It only helps if you already saved the proof: IP, device, login ID, and delivery address on earlier orders, kept about 13 months. Check your checkout before holiday volume hits.
Underwriters increasingly scan your website, not just your application: does your MCC match what you sell, are your policies visible, did you add products they don't know about?
Approval isn't the last review. Keep your site, MCC and products aligned.
https://t.co/6GtuKoTgCP
Processor notice says fees are changing "due to card brand updates"? Before you accept it: compare your effective rate to last month, match each new line item to a published Visa/Mastercard change, and get pass-through vs. markup in writing. https://t.co/6GtuKoTOsn