Bitcoin around $82,380, up 0.9%. Brent flat at $104.26. US 10-year edged up to 5.24%.
Next week: big bank earnings from Tuesday (JPM, Wells, Goldman, Citi), and whether this AI bounce holds with the 10-year still above 5.2%.
Nasdaq closes +0.6% to 27,366 and the S&P +0.6% to 7,812 after Thursday's OpenAI revenue scare. Tech buyers came back once the $50bn figure was digested. Still a fragile bounce. $QQQ
Trump said Russia will ship over 300,000 tons immediately, 500,000 in November, 1 million right after that, then up to another 3 million depending on their refineries. OFAC is issuing a temporary general license for Russian diesel into the global market, per Treasury. CBS and AP both have it.
Market angle: midterms play on fuel costs, and a U-turn on years of Russia energy pressure. Watch diesel cracks, heating oil and energy names.
BREAKING: Trump says Putin agreed to dump Russian diesel onto global markets, and Treasury just waived the sanctions to let it through. Diesel's been crushing truckers at over $6 a gallon. $USO
UKMTO logged it at about 6:00am ET / 3:00am PT, 13 nautical miles west of Al Jazeera in the UAE, citing multiple reports. Projectile strike, fire since extinguished. Crew status, damage and any environmental hit still unknown, authorities investigating.
Separately, the IRGC Navy says it hit the LPG carrier NV Sunshine (Natwit) after it tried an unauthorised route south of Hormuz, with a major fire in the engine room and propulsion. They blamed US forces for stoking the maritime tension.
Market angle: this one is outside the strait itself, so the risk zone is spreading into the wider Gulf. Watch Brent, tanker rates and energy names.
BREAKING: UKMTO says a vessel was hit by a projectile off the UAE coast and the fire is out. Iran's IRGC claims it struck LPG carrier NV Sunshine on an "illegal" Hormuz route. Gulf shipping risk spreads again. $USO
@YodaStockInvest@ModeFinancial I think it’s about more than just the growth though. The narrative around the saas stocks had made them fundamentally undervalued and as the market starts to realise that the stock will have to be rerated so there is plenty of upside
Rest of today:
10:30am ET / 7:30am PT EIA crude inventories
11am ET / 8am PT NY Fed consumer inflation expectations
1pm ET / 10am PT 10-year note auction
2pm ET / 11am PT FOMC minutes from the September hike
3pm ET / 12pm PT consumer credit for August, about 15bn expected vs 18.1bn in July
After the close, Levi Strauss and Applied Digital report, with Applied Digital the one to watch for AI data centre demand.
Fed minutes at 2pm ET / 11am PT are the whole day. This is the meeting where they HIKED, so it's all about how many still want more. Before that a 10-year auction at 1pm ET / 10am PT with yields near 5.3%. Hawkish minutes plus a sloppy auction and these records get tested. $SPY
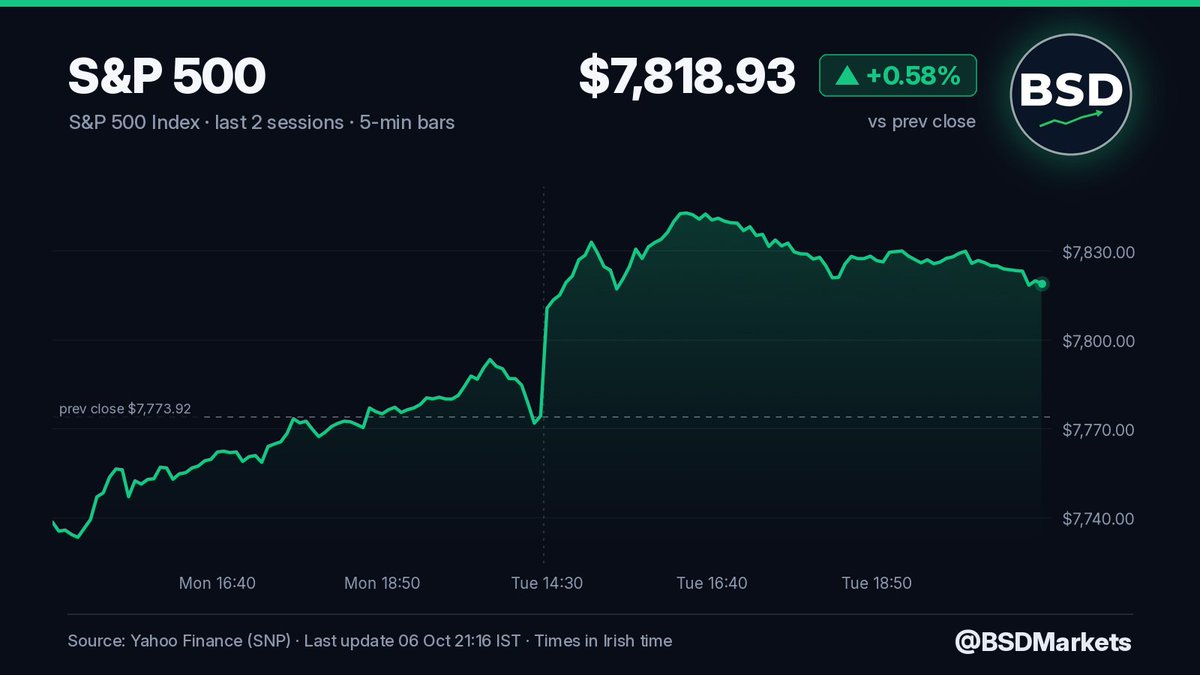
S&P 500 closes at a RECORD 7,819, up 0.6%, and the Nasdaq made it two records in a row. Bond selloff finally took a breather, 10-year back to 5.27% after Monday's highest since 2002. This rally only works if yields stay calm, and that's a big if. $SPY
The authority didn't say who was behind it, and its statement only covers Jazan and Najran. Overnight the Houthis claimed strikes on Riyadh's international airport, an Aramco refinery and other Saudi sites, AFP reports, with loud explosions heard in Riyadh. Saudi Arabia's Foreign Ministry has condemned Houthi attacks on civilians, economic facilities and religious sites, and Al Jazeera reports Turkey and Pakistan have agreed a rapid military deployment to the kingdom under the Mecca defence pact.
Market angle: oil's calm for now, but any confirmed hit on Saudi energy is a different game entirely. Watch Brent, any word from Aramco and Red Sea shipping.
BREAKING: Saudi Arabia's civil aviation authority says Jazan and Najran airports were hit in attacks on Monday night, with three people injured and material damage. Brent's barely flinched so far, which tells you how much Gulf risk is already priced in. $USO
Rest of today, Irish time:
9:30am UK construction PMI
10am Eurozone retail sales
1:30pm US trade balance for August, consensus about -$102bn vs -$88.6bn last time
2:05pm Fed's Williams
3:45pm Fed's Bowman
6pm US 3-year note auction
6:15pm Fed's Schmid
9:30pm API crude inventories
Earnings: Lamb Weston and RPM before the US open, Constellation Brands after the close. FOMC minutes land tomorrow.
S&P futures up a touch again but bonds are the real story. US 10-year still above 5.3% while the Nasdaq sits at records, that can't last FOREVER. Trade data at 1:30pm, then the Fed's Williams at 2:05pm and Bowman at 3:45pm. Any hawkish noise and tech feels it. $SPY
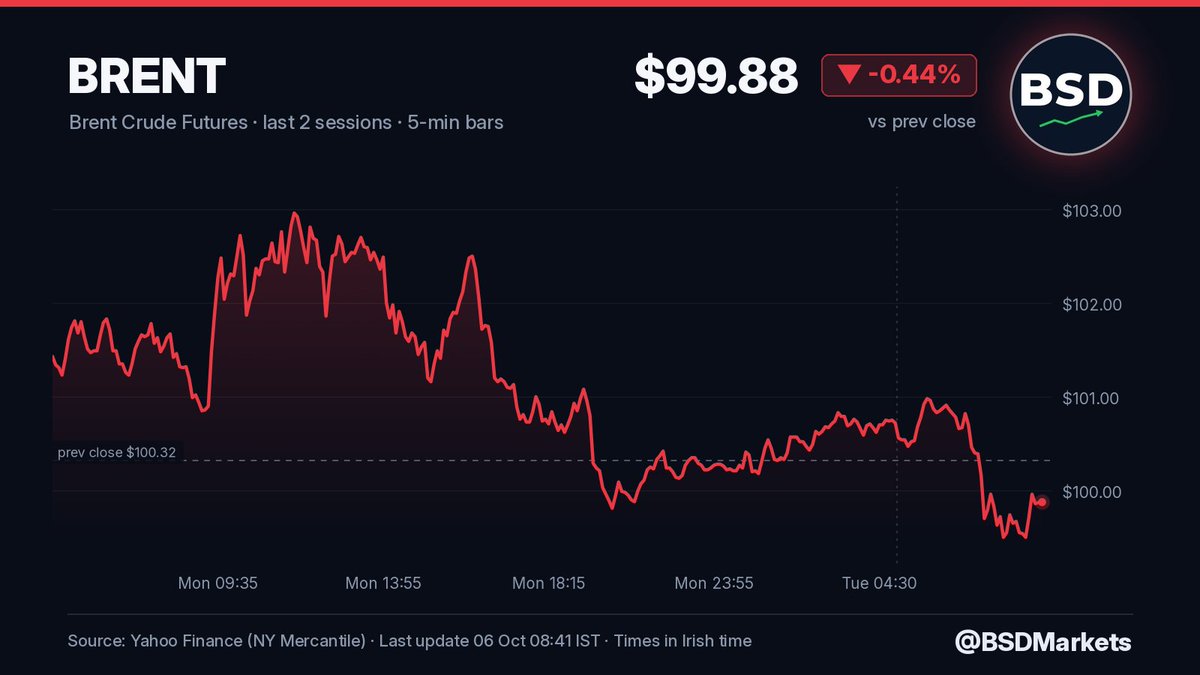
S&P 500 +0.7% to 7,774 and the Dow +0.2% to 51,268. US 10-year at 5.31%, up 3bp. Brent eased 2% to $100.25. Bitcoin around $85,750, down 0.8%.
Tomorrow: whether yields keep grinding higher, Brent holding $100 with the Gulf headlines still coming, and if tech can keep dragging a market where most stocks are lagging.
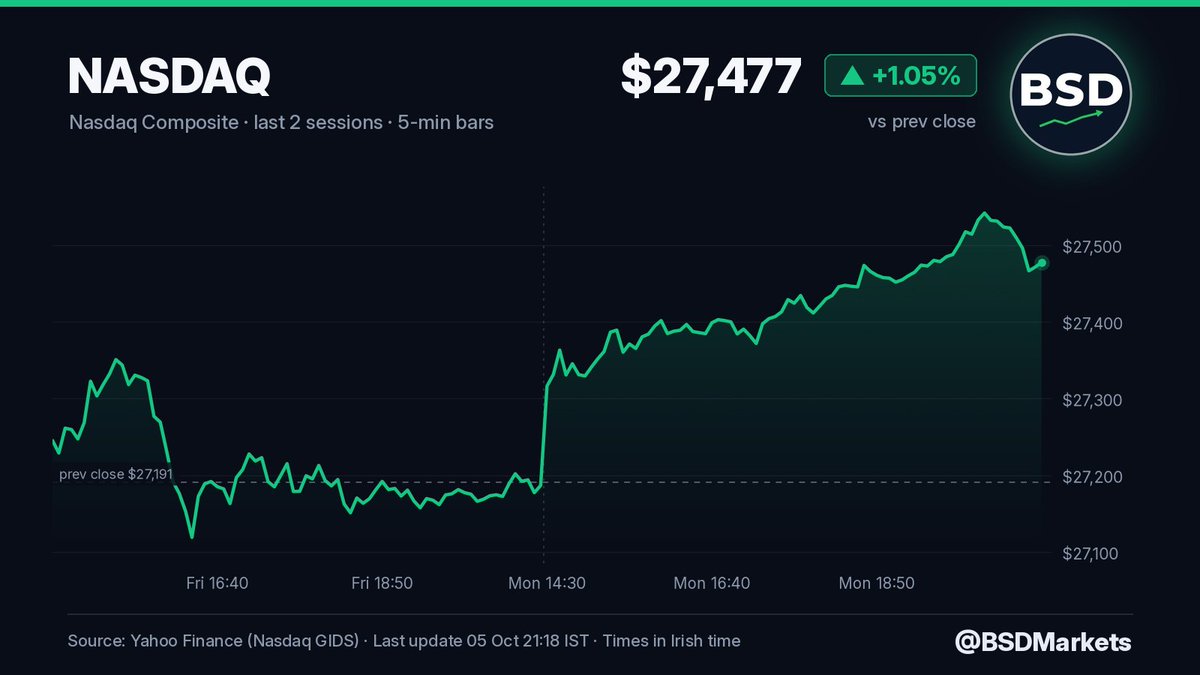
Nasdaq closes at a fresh record, up 1.1% to 27,477, with Nvidia, Meta and Microsoft doing the lifting. US 10-year pushed above 5.3% and nobody cared. Breadth is rubbish though, big tech is carrying the WHOLE market. $QQQ
@KobeissiLetter “History points to further weakness in market breadth” to then say that December and January are two of the strongest months for market breadth which is literally 2 months away. Good news if anything 🤷♂️