Market insights are shared here on X. Detailed trading plans, entry & exit strategies, and risk management updates are shared daily in my free WhatsApp group. Get it for free👇
https://t.co/V0rgUbuCvF
🎯There will be some excellent positioning opportunities in today's market. Anyone interested in participating can reach out to me directly via WhatsApp.
The initial estimated return is around 20%, although this is only a preliminary projection, not a guaranteed outcome.
Please stay connected and keep an eye on updates. If market conditions change, we'll adjust our strategy accordingly. When the market remains relatively stable, our trades have often delivered results that exceed our initial expectations.
Stay alert, stay informed, and be ready to seize the opportunity.
🎯Congratulations to everyone who joined our $CLRO setup last week!
We entered around $1.80, and the stock surged to an intraday high of $4.60 yesterday. After closing at $1.90, it rallied again in pre-market trading today, reaching as high as $4.30 — far beyond our second target!
From our entry near $1.80 to the pre-market high of $4.30, that represents a potential gain of approximately 139%. Even yesterday’s high of $4.60 marked a remarkable move of approximately 156% from our entry.
This is exactly why identifying opportunities early and staying focused on the market’s momentum matters. Congratulations to all our community members who followed the $CLRO setup! 🔥📈
Opportunities are meant to be seized. I’ll always share trading strategies with my community and on WhatsApp first, so feel free to reach out to me directly. There are still opportunities ahead before year-end. Let’s make the most of them and build wealth together!
U.S. Market Outlook | November 16–20
I’m going into this week with a bullish bias.
Last week, the Nasdaq gained around 3.5%, outperforming the broader market. More importantly, investors are starting to look beyond the recent selling pressure and refocus on where the next wave of growth will come from.
I believe the AI trade still has plenty of room to run. The market may be rotating, but that doesn't mean the opportunity is gone. It means capital is becoming more selective — and that's exactly where we need to pay attention.
Key catalysts this week:
• Tuesday – $NVDA earnings: The biggest event of the week. Investors will be looking for confirmation that AI chip demand remains strong and that hyperscalers are still committed to expanding data-center infrastructure.
• Tuesday – U.S. retail sales: A key read on consumer spending and the broader economic outlook.
• Wednesday – FOMC minutes: Investors will look for clues on the Fed's policy direction and the rate outlook.
• Wednesday – $PANW earnings: Cybersecurity remains an important area to watch as companies continue investing in digital infrastructure and AI security.
• Thursday – $WMT earnings: A useful gauge of consumer strength heading into the holiday shopping season.
Where I’m focusing this week:
AI semiconductors: $NVDA, $AVGO, $AMD, $MU
Networking & infrastructure: $ANET, $MRVL, $VRT
Optical connectivity: $AAOI, $COHR, $LITE
Cybersecurity: $PANW, $CRWD
My view is straightforward: I don't think this is the time to sit on the sidelines waiting for every uncertainty to disappear.
Strong companies don't always offer perfect entry points. When the market gives us a favorable setup, we need to recognize it and act with a clear plan.
I’m watching for opportunities to build positions this week, not just waiting for the next headline.
The key is knowing what to buy, where to enter, and when to take profits. More on today's opportunities in my next post.
Compute pricing is becoming as much about contract duration as the chips themselves with 5-year deals across $IREN and $CRWV around $20–25 per watt-year versus $40–50 for short-term capacity and new $SPCX contracts above $50. That spread creates an interesting opportunity for $NBIS whose 2026 base sits near $12 while newer short-term deals exceed $40 leaving room for realized pricing to rise as its contract mix shifts toward higher rates. You can see the same dynamic within SpaceX where $ANT initial agreement priced near $30 while $GOOGL is paying $53–79 including H100s at more than 3x the rental index suggesting contract timing and guaranteed access are becoming just as important as the GPU itself.
Renaissance Technologies Makes a Remarkable AI Chip Rotation with Its Investments in $MU $AMD $NVDA
Renaissance Technologies' latest SEC filing reveals a striking shift in semiconductor exposure. The quantitative investment firm increased its Micron common-stock position more than 7X during the third quarter, making MU its largest disclosed holding at approximately $1.62 billion. Meanwhile, Renaissance reduced its Nvidia shareholding by 99.7% and increased its AMD position by roughly 140%. These are substantial changes, although the November 12 filing reflects September 30 holdings. It doesn't establish what the firm owns today or why those trades occurred. The underlying investment economics are worth examining. Nvidia, AMD and custom AI-chip developers compete for accelerator spending, but each creates demand for advanced memory. Micron can potentially benefit from the expansion of several competing computing architectures rather than relying on one GPU vendor's market share. That diversification doesn't eliminate memory's cyclical risks or dependence on sustained AI investment. For MU shareholders, the more durable investment thesis is that competition among AI accelerator suppliers can expand the market for high-performance memory, provided Micron maintains pricing power as industry capacity grows.
$CRWV is seeking a $4B loan backed by $META
contracts at ~7.5% which is well below 16% yield on its unsecured bonds. That’s higher than the 5.9% it secured in March but it also shows why having investment-grade customers locked into long-term contracts is so valuable when financing next wave of AI capacity.
Today's market briefing is still underway. Once it's finished, I'll be sharing our trading plan for next week. Feel free to contact me directly on WhatsApp to get the details.💫
For those who haven't joined our community yet, you can reach me through the pinned post. After a brief conversation to confirm you're a real person and not a bot, I'll send you an invitation to join.
I'm receiving quite a lot of messages, so please bear with me if my reply isn't immediate. I'll get back to everyone as soon as I see their message.
🚨🇺🇸 Trump Weighs In on the Microsoft Outlook Outage — and Throws His Support Behind Elon Musk's X Mail
"Look at what's happening with Microsoft. It's a complete disaster. A company this big can't even keep its email service running properly. Businesses are losing productivity, critical communications are disrupted, and people are left waiting for a service they depend on every single day.
And let's be honest, this goes beyond inconvenience. When major companies and government agencies rely on these systems, reliability becomes a matter of national security.
I would tell Elon, who's a tremendous builder and knows how to get things done: Maybe it's time to launch X Mail.
We need something faster, more reliable, and built for the future. Microsoft has dominated this space for years, but that doesn't mean it should own it forever.
Competition is good. And maybe this is exactly the opportunity X has been waiting for."
#Microsoft #ElonMusk #XMail #TechNews #BigTech
🚨🇺🇸 Elon Musk Takes Aim at Microsoft After Outlook Outage
A full-day Outlook outage is more than just an inconvenience. It's a serious wake-up call.
For a company as massive as Microsoft, email isn't some minor feature. It's essential infrastructure that millions of businesses rely on every single day.
When a core service goes down, productivity stops, trust takes a hit, and customers start looking for alternatives.
Microsoft has spent years building its enterprise ecosystem, but reliability is what keeps customers loyal.
And if Elon Musk sees an opportunity here, don't be surprised if the idea of X Mail starts getting attention.
In tech, disruption doesn't always begin with a better product. Sometimes, it starts when the market gets tired of the old one.
Absolutely. And the latest earnings report makes the case even stronger. Cerebras reported 70% year-over-year growth in Core revenue for Q3 2026, while Core cloud revenue surged 272%. It also raised its full-year revenue outlook to $940M–$960M. To me, the most important part is that inference demand is translating into real revenue growth.
I’m holding $CBRS because I believe in the growth potential of the AI inference market over the next several years.
As AI models become increasingly complex and AI agents and real-time applications continue to expand, demand for computing speed, inference efficiency, and infrastructure capacity will continue to rise.
Cerebras’ differentiated technology, cloud services business, customer partnerships, and data center expansion provide a strong foundation for its future growth.
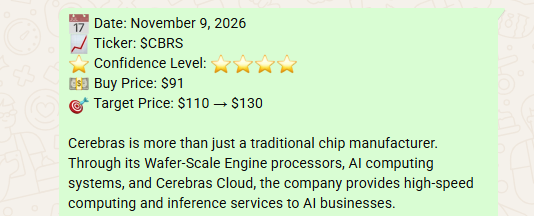
🎯Congratulations to everyone who got into $CBRS around $91!
As I mentioned in yesterday's analysis, Cerebras is a high-risk, high-reward AI play. It has strong growth potential, but volatility comes with the territory.
So far, the stock has climbed to nearly $117 in pre-market trading, breaking through our first target of $110 and now moving toward the second target.
If you're holding $CBRS, keep an eye on community updates and make sure you don't miss any trading strategy notifications. Protecting your profits and managing risk are just as important as reaching our targets!
I’m holding $CBRS because I believe in the growth potential of the AI inference market over the next several years.
As AI models become increasingly complex and AI agents and real-time applications continue to expand, demand for computing speed, inference efficiency, and infrastructure capacity will continue to rise.
Cerebras’ differentiated technology, cloud services business, customer partnerships, and data center expansion provide a strong foundation for its future growth.
🚨🇺🇸 Elon Musk Takes Aim at Microsoft After Outlook Outage
A full-day Outlook outage is more than just an inconvenience. It's a serious wake-up call.
For a company as massive as Microsoft, email isn't some minor feature. It's essential infrastructure that millions of businesses rely on every single day.
When a core service goes down, productivity stops, trust takes a hit, and customers start looking for alternatives.
Microsoft has spent years building its enterprise ecosystem, but reliability is what keeps customers loyal.
And if Elon Musk sees an opportunity here, don't be surprised if the idea of X Mail starts getting attention.
In tech, disruption doesn't always begin with a better product. Sometimes, it starts when the market gets tired of the old one.
$NVDA — Major News: Jensen Huang is stepping down after 33 years at the helm of Nvidia.
According to reports, Nvidia has announced that Jensen Huang is stepping down, effective immediately, from his roles as CEO, President, and member of the Board of Directors.
Chief Financial Officer (CFO) Colette Kress will serve as interim CEO. The company has already initiated a search for a new leader.
The earnings call, originally scheduled for November 17, will proceed as planned—marking the first major test for the interim CEO.
Jensen Huang founded Nvidia in 1993 and led the company for 33 years. It is reported that approximately 60 executives reported directly to him, and the company had no clear succession plan in place.
Nvidia’s stock has reportedly fallen by more than 10% in pre-market trading, with the company’s market capitalization shrinking by approximately $600 billion this week.
The upcoming earnings call has taken on added significance. Investors will be watching closely to see how the interim leadership handles earnings guidance and navigates this leadership transition.
What do you think—is Nvidia still worth its current valuation without Jensen Huang?
U.S. Earnings Watch | November 12
Today's earnings calendar puts the spotlight on AI infrastructure, semiconductors, networking, defense technology, and space.
Here are the names I'm watching and what I expect the market to focus on.
Pre-Market Earnings
$NBIS — Nebius Group
• Focus: AI infrastructure demand, new computing contracts, data center expansion, and capital expenditure.
• My view: Bullish long-term outlook, but expectations are already high. Strong revenue growth and an upbeat outlook could support the stock. Rising capex and financing costs remain key risks.
$ONDS — Ondas
• Focus: Defense contracts, drone technology, order backlog, and revenue conversion.
• My view: Strong order growth could attract attention, but investors need to see actual revenue delivery and improving cash flow.
$LUNR — Intuitive Machines
• Focus: NASA contracts, mission progress, backlog, and future revenue visibility.
• My view: Positive contract developments could provide upside. However, the stock remains highly volatile, and strong expectations may already be priced in.
$BN — Brookfield
• Focus: Assets under management, fundraising, fee-related earnings, and infrastructure investments.
• My view: A solid report could reinforce confidence in its long-term infrastructure strategy, although it is less directly tied to today's AI trade.
$DDL — Dingdong
• Focus: Revenue growth, gross margins, operating efficiency, and cash flow.
• My view: Margin improvement matters more than sales growth alone. Investors want to see whether the business can grow profitably.
After-Market Earnings
$AMAT — Applied Materials
• Focus: Semiconductor equipment demand, advanced manufacturing, gross margins, and forward guidance.
• My view: AI chip demand remains a long-term tailwind. Strong guidance could support the semiconductor equipment sector, but watch for profit-taking if expectations are already elevated.
$CSCO — Cisco
• Focus: AI networking demand, data center orders, switching equipment, and revenue guidance.
• My view: AI infrastructure spending is expanding beyond GPUs into networking. Strong AI-related orders could strengthen Cisco's growth story.
$CBRS — Cerebras Systems
• Focus: AI chip commercialization, revenue growth, gross margins, and order execution.
• My view: High-risk, high-reward. Strong revenue and margin performance could support a valuation recovery, while weak profitability could trigger significant volatility.
$NU — Nu Holdings
• Focus: Customer growth, deposits, loan quality, net interest income, and credit risk.
• My view: Continued customer and earnings growth would be positive, but investors should pay close attention to credit quality.
My Earnings Predictions: 5 Stocks to Watch
$NBIS — Bullish, but expect volatility.
AI infrastructure demand remains a powerful growth driver. If revenue growth stays strong and management maintains an ambitious expansion outlook, NBIS could see further upside. However, elevated capital spending and financing needs remain key risks.
$AMAT — Cautiously bullish.
The AI semiconductor investment cycle remains supportive. Strong revenue and forward guidance could lift sentiment across semiconductor equipment stocks. But with expectations already high, even a solid earnings beat may trigger a sell-the-news reaction.
$CSCO — Bullish if AI networking delivers.
AI spending is expanding beyond GPUs into high-speed networking and data center infrastructure. Strong AI-related orders and an upbeat outlook could give Cisco another growth catalyst. Weak guidance, however, could limit the upside.
$CBRS — High risk, high reward.
Cerebras has an interesting position in the AI computing market. Strong revenue growth, improving margins, and evidence of successful order execution could spark a sharp rally. But any disappointment in profitability could lead to equally sharp downside.
$ONDS — Speculative bullish.
Defense technology and autonomous drone systems remain attractive long-term themes. Strong contract growth and improving revenue conversion could support the stock. The biggest question is whether its expanding order pipeline can translate into sustainable business growth.
My Overall Outlook
Strongest fundamental setup: NBIS
Best semiconductor opportunity: AMAT
AI networking upside: CSCO
Highest upside potential with elevated risk: CBRS
Speculative defense play: ONDS
My expectation is that these five stocks could deliver very different reactions to their earnings.
I'm leaning bullish on the AI infrastructure theme, but I wouldn't chase the initial spike. The real opportunity will come from identifying which companies can turn strong demand into sustainable revenue, margins, and cash flow.
Earnings can create momentum. Guidance determines whether that momentum lasts.
Could Nvidia’s bylaws give Jensen Huang a way to fight back if the board ever turns against him?
Nvidia has a little-known provision: Proxy Access.
According to its 2026 proxy filing:
▪️ Huang holds approximately 870.6 million shares, representing 3.58% of voting power.
▪️ Shareholders with at least 3% voting power held continuously for three years can nominate up to two directors, subject to additional requirements.
▪️ The 2027 nomination window: February 24 – March 26.
What does this mean?
Even if Huang were removed as CEO, he could still have a path to challenge the board — provided he meets the eligibility requirements.
A nomination doesn't guarantee a seat, and 3.58% isn't control.
But one thing is clear:
The board can remove Jensen Huang as CEO. It cannot take away his rights as a shareholder.
The door may not be closed as easily as some think. 👀
$NVDA