@Courage_wins@thinkReal Been investing over the past 2 years , excited to experience the run up eventually. Have accumulated a good amount of shares. This will be my first “early” investment.
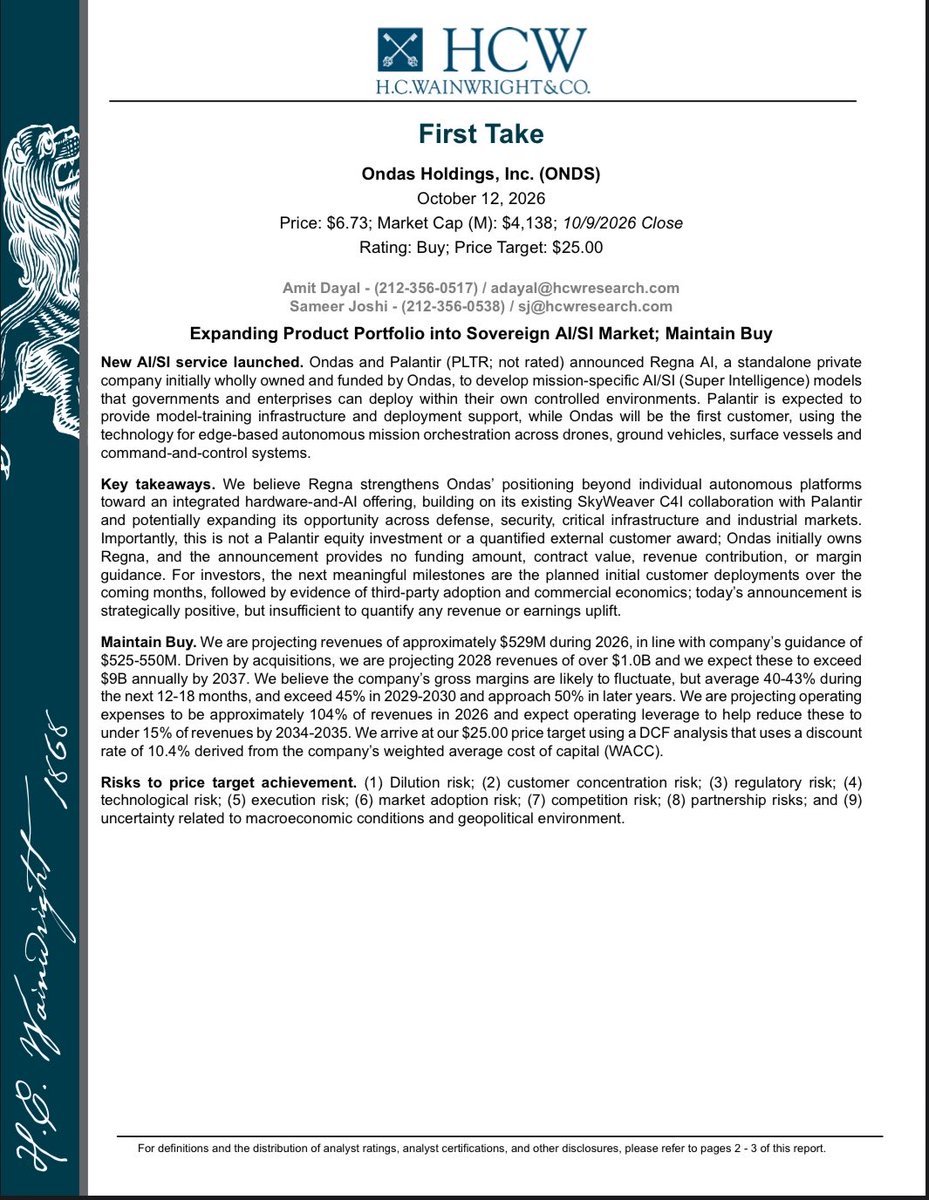
🚨 $ONDS JUST IN: H.C. WAINWRIGHT REITERATES “BUY” RATING ON $ONDS & MAINTAINS $25 PRICE TARGET FOLLOWING THE REGNA AI ANNOUNCEMENT WITH $PLTR 🚨
The firm’s $25 PT represents a 270%+ move from current levels.
H/T: @HighNTight__19 👊🏼
Ondas CEO, @CeoOndas Eric Brock outlines three vectors of value creation for Regna AI: embedded equity value as the platform scales, lower Ondas investment in sovereign AI development, and mission-specialized AI supporting autonomy across the Ondas systems of systems portfolio. $ONDS
https://t.co/otLSIamVVH
When the market looks at $ONDS it sees a pile of acquisitions being built off of shareholder dilution. I see a defense company being assembled in real time without tapping the debt market.
Ondas has a $757 million pro forma backlog with a revenue target of $525 to $550 million for the 2026 fiscal year. I started a position at the end of last week and finished writing a bullish deep dive which will be out tomorrow.
I believe that the acquisitions, customer relationships and $PLTR partnership are beginning to fit together. This combination could become dramatically more valuable over the next five years. Here is the underlying business Ondas is building at a time when autonomous warfare is still in it’s infancy:
· Sentrycs provides cyber-based counter-drone capabilities
· Iron Drone adds physical interception
· DZYNE brings Dronebuster, the ULTRA reconnaissance aircraft and IonStrike.
· World View adds persistent sensing from the stratosphere
· Roboteam adds ground robotics
I see a company positioning itself to detect threats, collect intelligence and deliver responses across multiple domains. Integrating those capabilities could make Ondas more valuable to a customer than any individual product.
Then there is Mistral which was a brilliant acquisition. That acquisition gives Ondas direct prime contractor access to U.S. Army and Special Operations contract vehicles, alongside domestic manufacturing and integration capabilities. Owning that customer relationship matters when you are trying to turn a growing technology portfolio into larger defense programs.
The financial progress is getting harder to ignore:
• Q2 revenue: $83.8 million, up 67% sequentially
• Pro forma organic revenue growth: 85% year over year
• Reported June backlog: $613 million
• Pro forma backlog including DZYNE and Cyberhawk: $757 million
• Full-year 2026 revenue target: $525–$550 million
I will be focusing on the organic growth Ondas can produce because acquisitions alone cannot carry this thesis indefinitely. I want to see the underlying businesses growing while orders convert into deliveries with more cash hitting the cash flow statement.
Palantir is where the longer-term opportunity gets especially interesting. The $PLTR partnership covers manufacturing, mission planning and intelligence processing aboard autonomous platforms. SkyWeaver is being developed to process information closer to the mission and support operations when connectivity is degraded.
My view is that coordinating drones, sensors and ground systems could become one of the most valuable parts of this market. Ondas has an opportunity to participate in that software layer alongside its hardware. A recurring software business would strengthen the economics considerably.
The balance sheet also matters as Ondas ended June with approximately $1.38 billion in cash, cash equivalents and short-term investments, against roughly $6.4 million of debt. Subsequent acquisitions have consumed substantial cash but that starting position gives management room to build.
Equity financing has a real cost as every new share reduces my ownership unless the value created exceeds dilution. I am judging management on whether this acquisition strategy ultimately produces greater earning power per share. You will need to read my article which is forthcoming to see my bull case and price targets.
I will be watching organic growth, backlog conversion, cash consumption and the share count together. My bet is that Ondas can turn this collection of capabilities into a profitable defense platform whose earning power grows faster than its share count.
My question for the Ondas community is which development do you think would provide the strongest evidence that this strategy is working?
Is $ONDS a Buying Opportunity?
There's a ton of you who follow Ondas...
Which means, this SATURDAY at NOON EST, we are doing the next episode of STOCK TANK where @BMSInvests will pitch us $ONDS stock.
Should be fun. Save the link below for the stream. See you on Saturday.
OH. MY. GOODNESS.
CITADEL HAS BOUGHT A MAJORITY OF THE PUBLIC ASSETS FROM LEOPOLD'S SITUATIONAL AWARENESS FUND.
So...Citadel scares everyone on Tuesday about a surprise rate hike during FOMC that WE ALL KNEW was not going to happen...
On Wednesday, the entire market freaks out about the rate hike which causes the selling to compound on itself creating 50-70% drawdowns across the board in high beta semicondcutor names...
Which means Leopold who we now know had $45B of assets and was 400% LEVERED ends up being the sacrifice as he gets liquidated at what theoretically could be the bottom due to not having the margin requirements to keep solvent...
AND THE PERSON WHO CAUSED THE SELLOFF WITH THE RATE HIKE FEARS ENDS UP COMING IN TO BUY HIS ASSETS FOR 40 TO 50 CENTS ON THE DOLLAR.
By the way, Leopold is getting married this weekend. I think he wanted to make sure he wasn't getting margin called during his wedding.
A vet on wall street in Ken Griffin takes out the young new kid.
ABSOLUTE. CINEMA.
🚨🤯 BLACKROCK JUST DISCLOSED 7.2% OWNERSHIP OF $ONDS, TOTALLING 38,129,865 SHARES‼️
This is a 1,668% INCREASE from Q126, where they reported ownership of 2,156,502 shares.
One of the largest and most influential firms in the world is accumulating $ONDS at an ungodly rate AND YOU’RE BEARISH?👀