We help businesses understand what banks look for through eligibility analysis, financial positioning, and approval strategy for long-term funding readiness.
Not every business financing product solves the same problem.
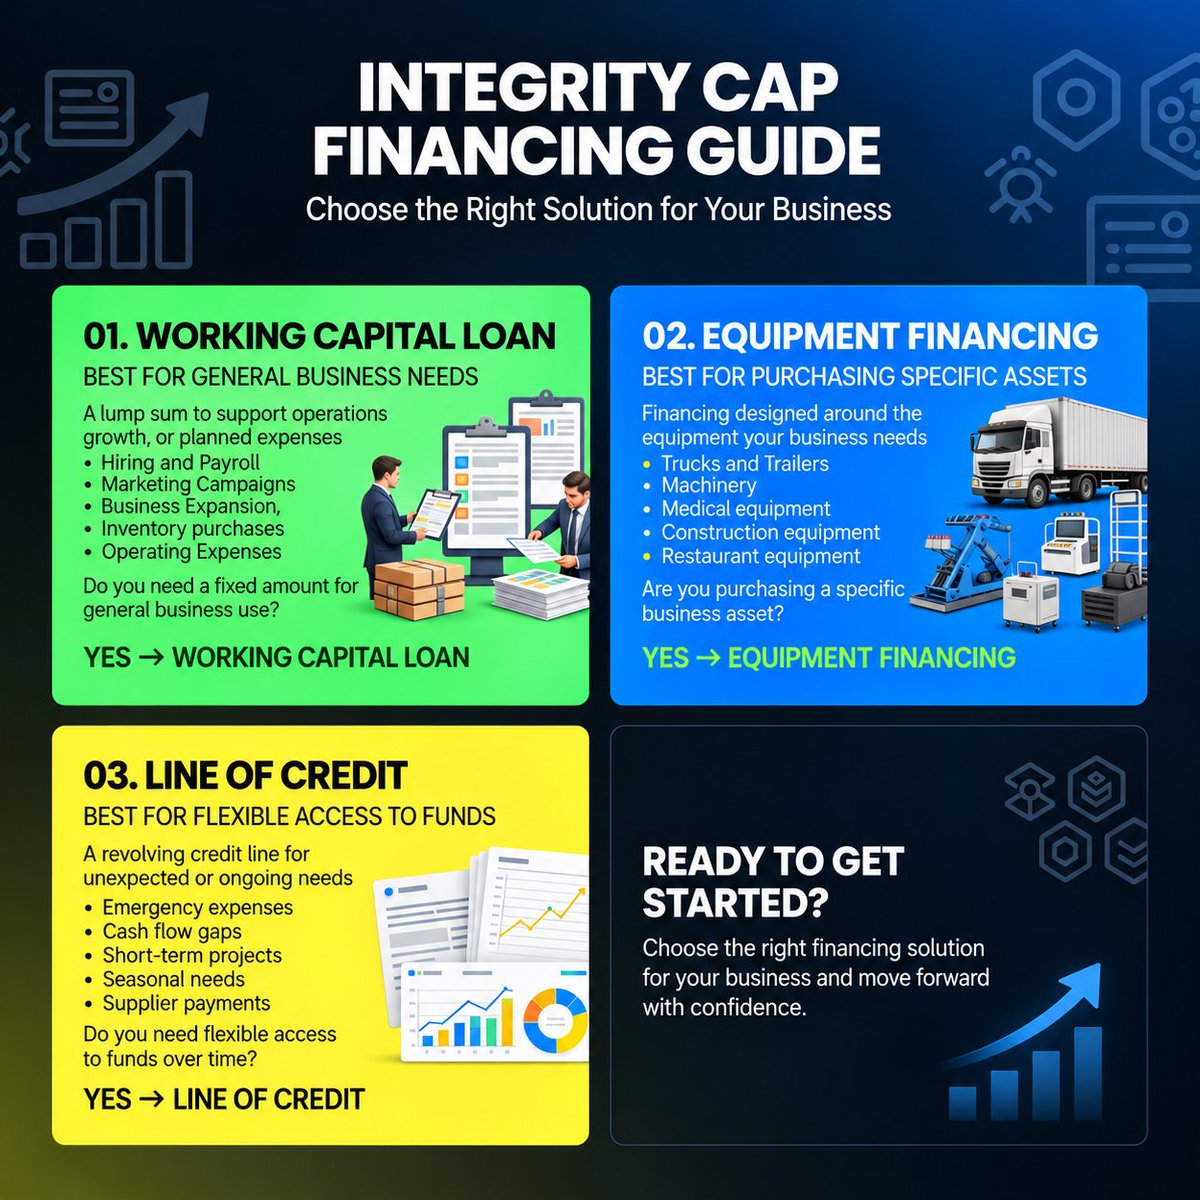
A working capital loan, equipment financing, and a line of credit all serve different purposes.
🟢 Working Capital Loan: For general business expenses, operations, and growth.
🔵 Equipment Financing: For purchasing trucks, machinery, or other business equipment.
🟡 Line of Credit: For recurring expenses, seasonal needs, and flexible access to capital.
The goal isn't just getting approved. It's choosing financing that matches how your business actually needs to use the money.
What does your business need funding for?
Comment below, and we'll help you identify which financing option may fit.
Visit https://t.co/72Fd0r5IAm
#BusinessLoans #BusinessFunding #WorkingCapital #EquipmentFinancing #LineOfCredit #CommercialLending #CashFlow #SmallBusiness
Same-Day Funding, No Documents' Is the Line That Should Slow You Down, Not Speed You Up.
The Same-Day Funding Trap
“Same-day funding.”
“No documents needed.”
“Money today.”
Convenient?
Yes.
Automatically a good deal?
No.
Before accepting a fast MCA offer, check:
Factor rate
Total payback
Daily or weekly payment
Expected repayment period
Prepayment terms
Renewal and stacking risk
The biggest mistake is comparing offers by speed instead of cost.
Fast capital can make sense in the right situation.
But if the lender talks more about how quickly you can get the money than how much the money will actually cost, slow down.
Speed is a feature.
Cost is the decision.
Visit https://t.co/72Fd0r5aKO
#SBALoans #WorkingCapital #BusinessFunding #CommercialLending #CashFlowManagement #DebtRestructuring #BusinessLoans #SmallBusinessFunding #BusinessCapital #MCARelief
[WEEKLY DEAL BREAKDOWN] IT Consulting Firm: $38,000 MCA Payment Down to $6,100 a Month
FRIDAY DEAL BREAKDOWN #1
Priority Systems Group, an IT consulting firm, came in with:
2 merchant cash advances
$38,000/month in combined payments
That level of debt pressure was taking too much cash out of the business every month.
So the MCA debt was restructured into one longer-term facility with a payment structure that better matched the business.
Before:
2 MCA payments
$38,000/month
After:
1 restructured payment
Lower monthly cash flow pressure
Cleaner debt structure
The lesson:
A business can look stressed when the real issue is not revenue.
It is the way the debt is structured.
This is why lender fit and deal structure matter.
Deal breakdown number one complete.
Visit https://t.co/72Fd0r5IAm
#SBALoans #WorkingCapital #BusinessFunding #CommercialLending #CashFlowManagement #DebtRestructuring #BusinessLoans #SmallBusinessFunding #BusinessCapital #MCARelief
Same $150K. $26,500 Different in Financing Cost.
Two financing options can give you the same $150,000 and create two very different outcomes.
Example A: 12-month MCA
$150,000 advance
1.45 factor rate
$217,500 total payback
$67,500 financing cost
Example B: 5-year term loan
$150,000 loan
10% APR
About $191,000 total payback
About $41,000 financing cost
That is a difference of roughly $26,500 in total cost.
And the difference is not only the price.
The MCA can also create much more payment pressure because of the shorter term and more frequent withdrawals.
Same capital. Different structure. Different cash flow outcome.
Before signing, compare more than how fast the money arrives.
Compare the total payback, repayment structure, and real impact on your business cash flow.
#MCA #TermLoan #BusinessFunding #CashFlow #DebtRefinance #WorkingCapital #BusinessLoans #IntegrityCap
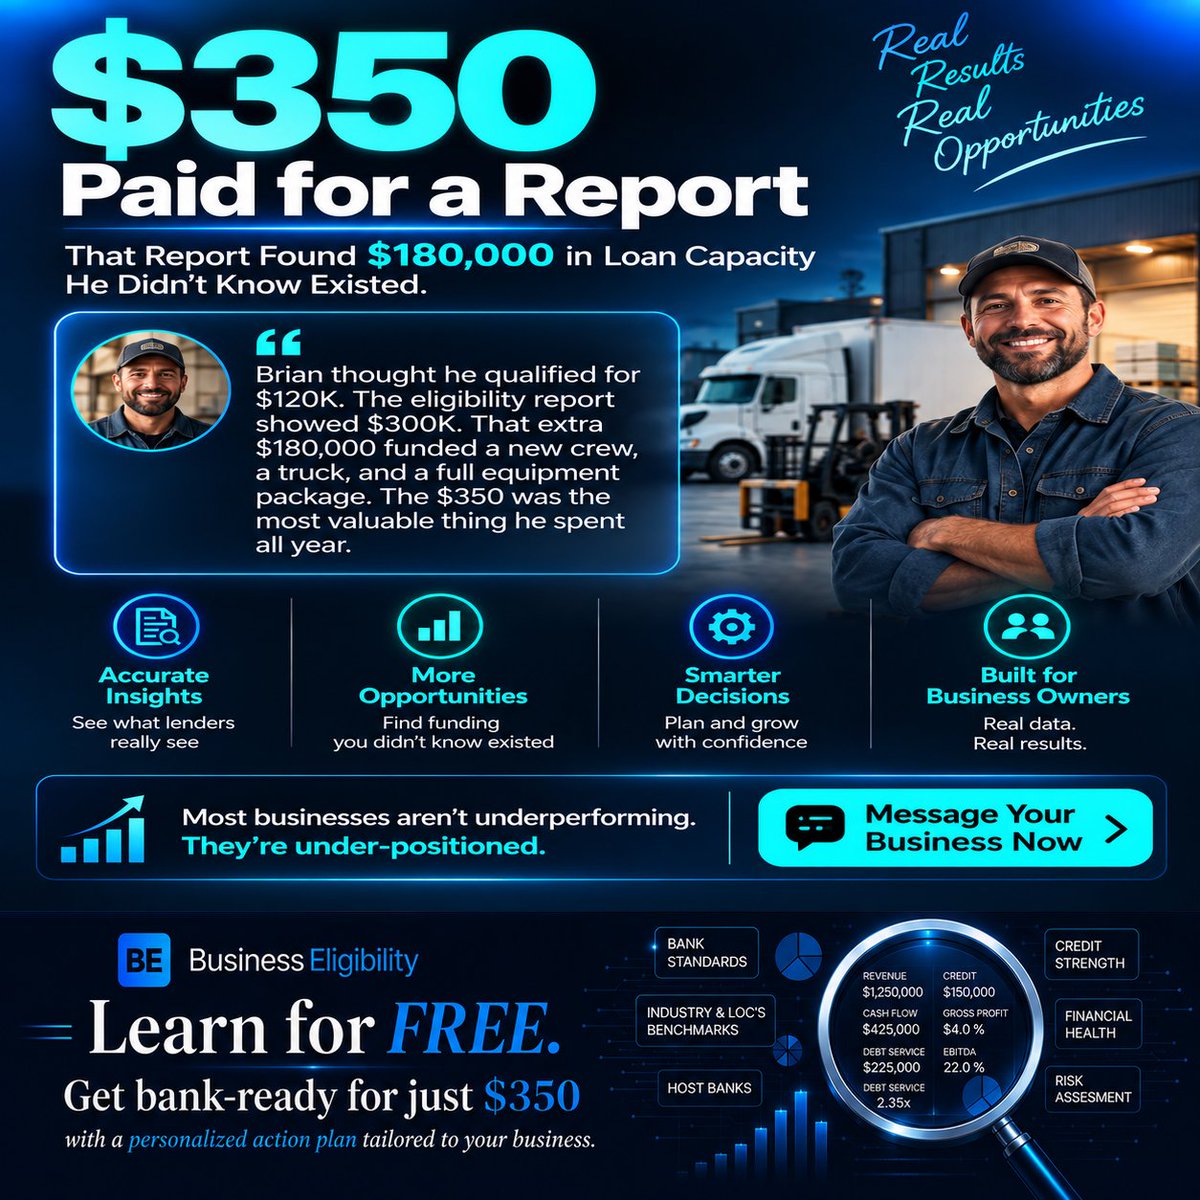
What if you’re qualifying for less simply because your file isn’t structured correctly?
Two businesses can have similar revenue and credit, yet see very different funding options.
Lender fit, debt structure, cash flow, and how the file is presented can all affect capacity.
Before applying, understand what your business can realistically support.
Start learning at https://t.co/D84kDQA1iM.
#BusinessFunding #BusinessLoans #SBALoans #BusinessCredit #FundingStrategy #CashFlow #BankReady #BusinessEligibility
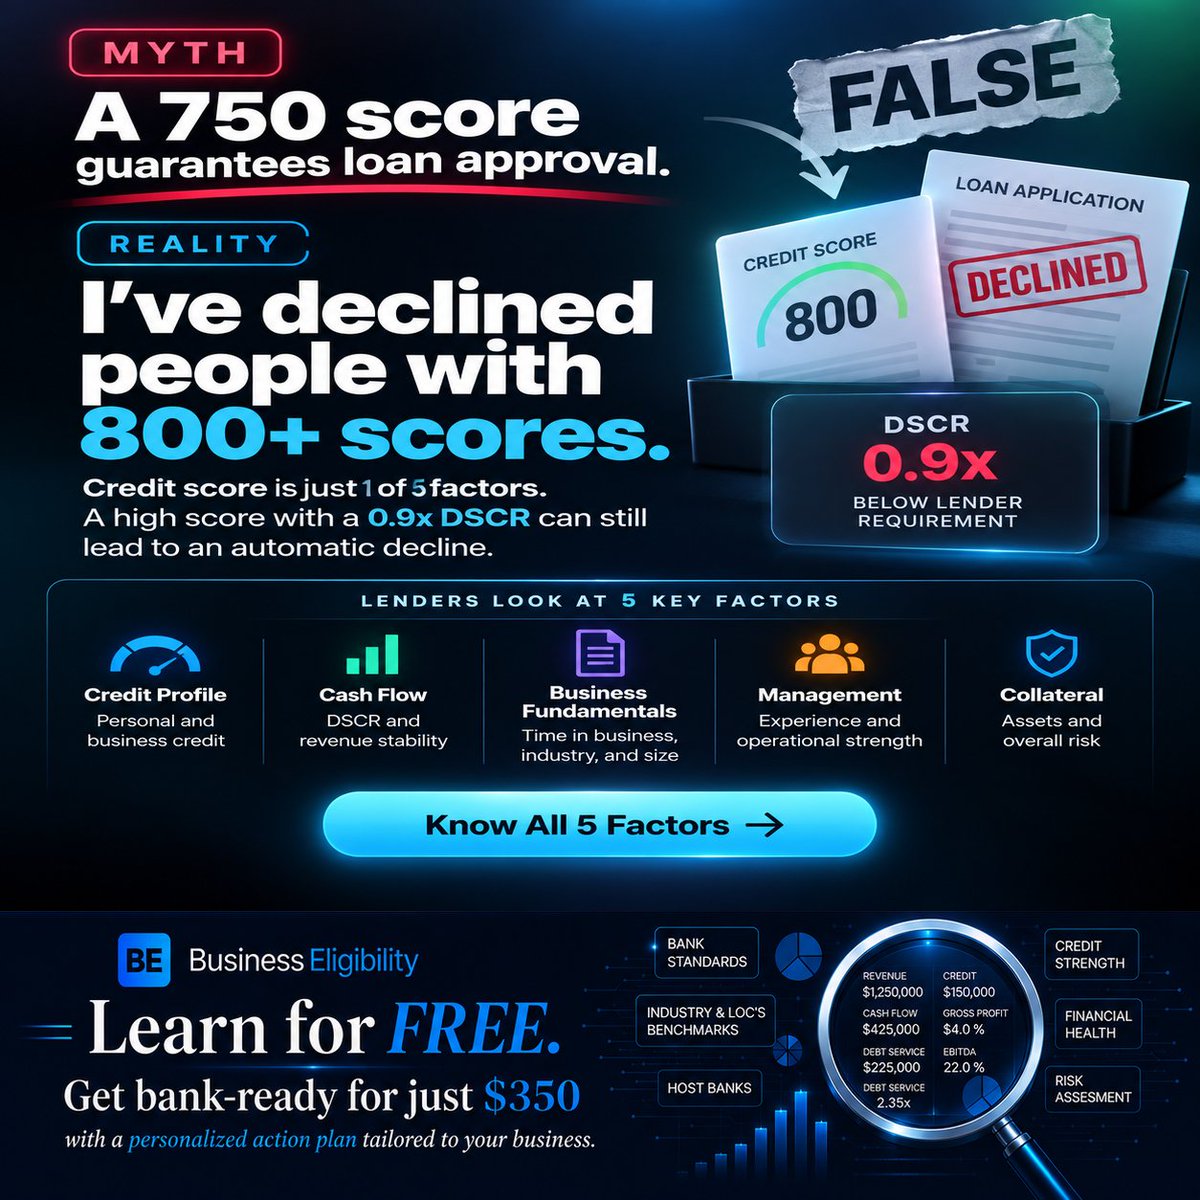
Think an 800 credit score guarantees approval?
It doesn’t.
Banks look at the full picture, and one weak area can outweigh an excellent credit score.
Before you apply, know the 5 factors lenders actually evaluate.
Visit: https://t.co/7KgTY0Wt0o
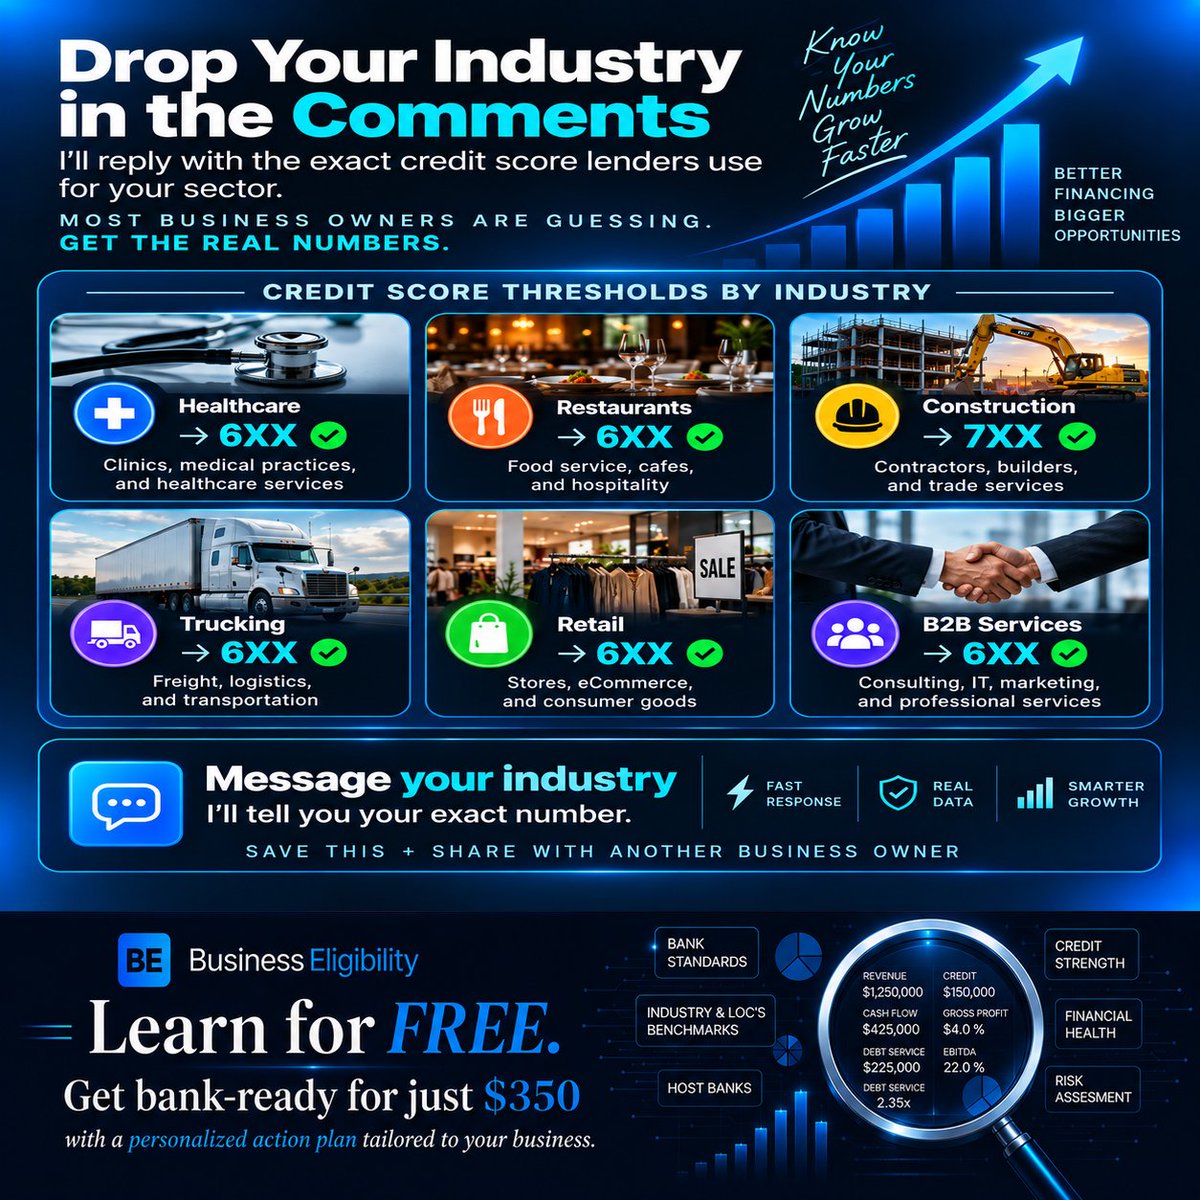
Your industry can change the credit profile lenders expect.
There isn’t one magic credit score that guarantees a business loan.
Lenders may weigh industry risk, cash flow, time in business, debt, and other factors differently.
Before you apply, know what your business profile actually looks like.
What industry are you in?
Visit: https://t.co/D84kDQA1iM
#BusinessLoans #BusinessCredit #BusinessFunding #CreditScore #SBALoans #BankReady #BusinessEligibility
We're Publishing Every SBA Rate We See This Quarter. Follow to Track the Trend With Us.
Want to track SBA rates this quarter?
Follow this page.
We are posting the SBA pricing and structures we see across real deals so you can watch the trend develop over time.
We will track:
Rates
Loan terms
Borrower profiles
Lender differences
Pricing changes throughout the quarter
Rates can vary by lender, borrower profile, loan structure, and market conditions.
The goal is not to give you one universal number.
It is to show you what the market is actually doing as deals move.
Follow and track the trend with us.
Visit https://t.co/72Fd0r5aKO
#SBALoans #WorkingCapital #BusinessFunding #CommercialLending #CashFlowManagement #DebtRestructuring #BusinessLoans #SmallBusinessFunding #BusinessCapital #MCARelief
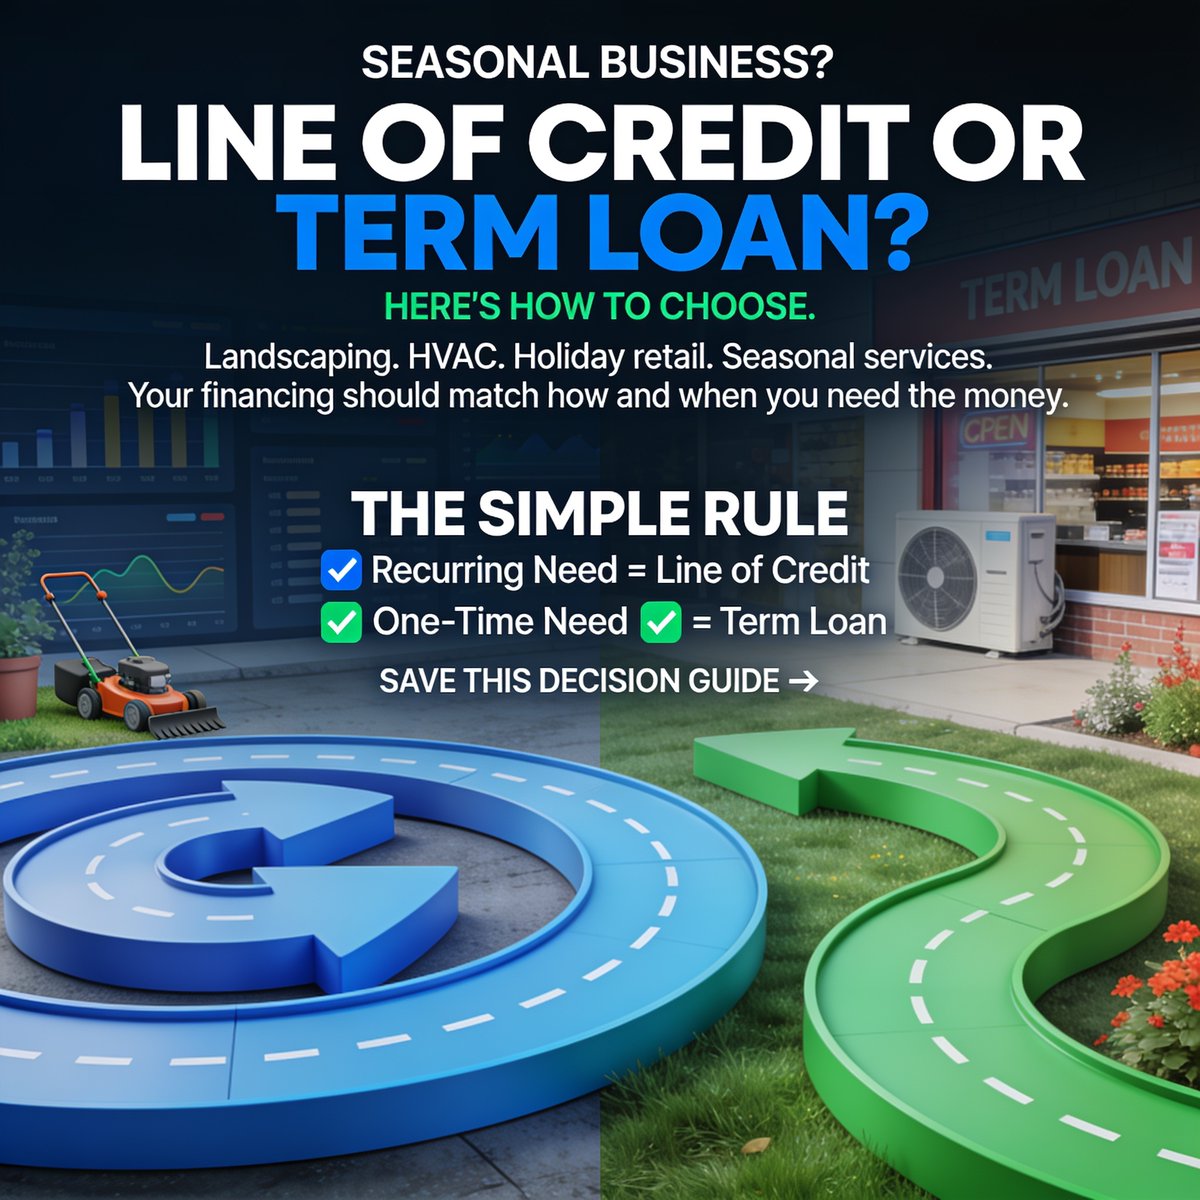
Seasonal businesses often need capital for two very different reasons.
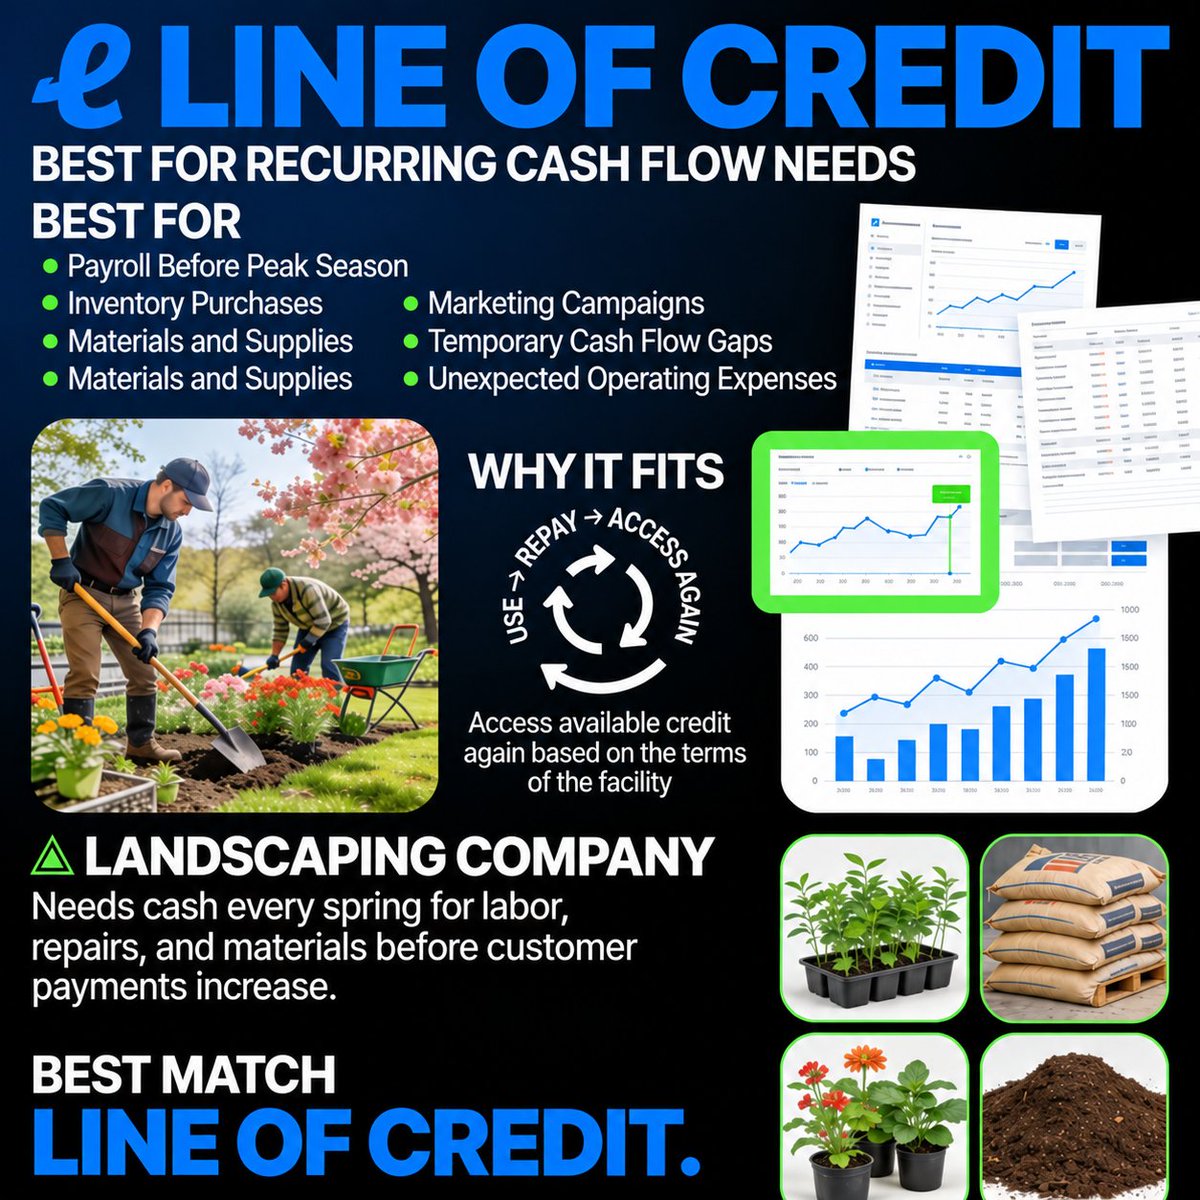
If expenses like payroll, inventory, or materials come back every season, a line of credit may provide the flexibility you need.
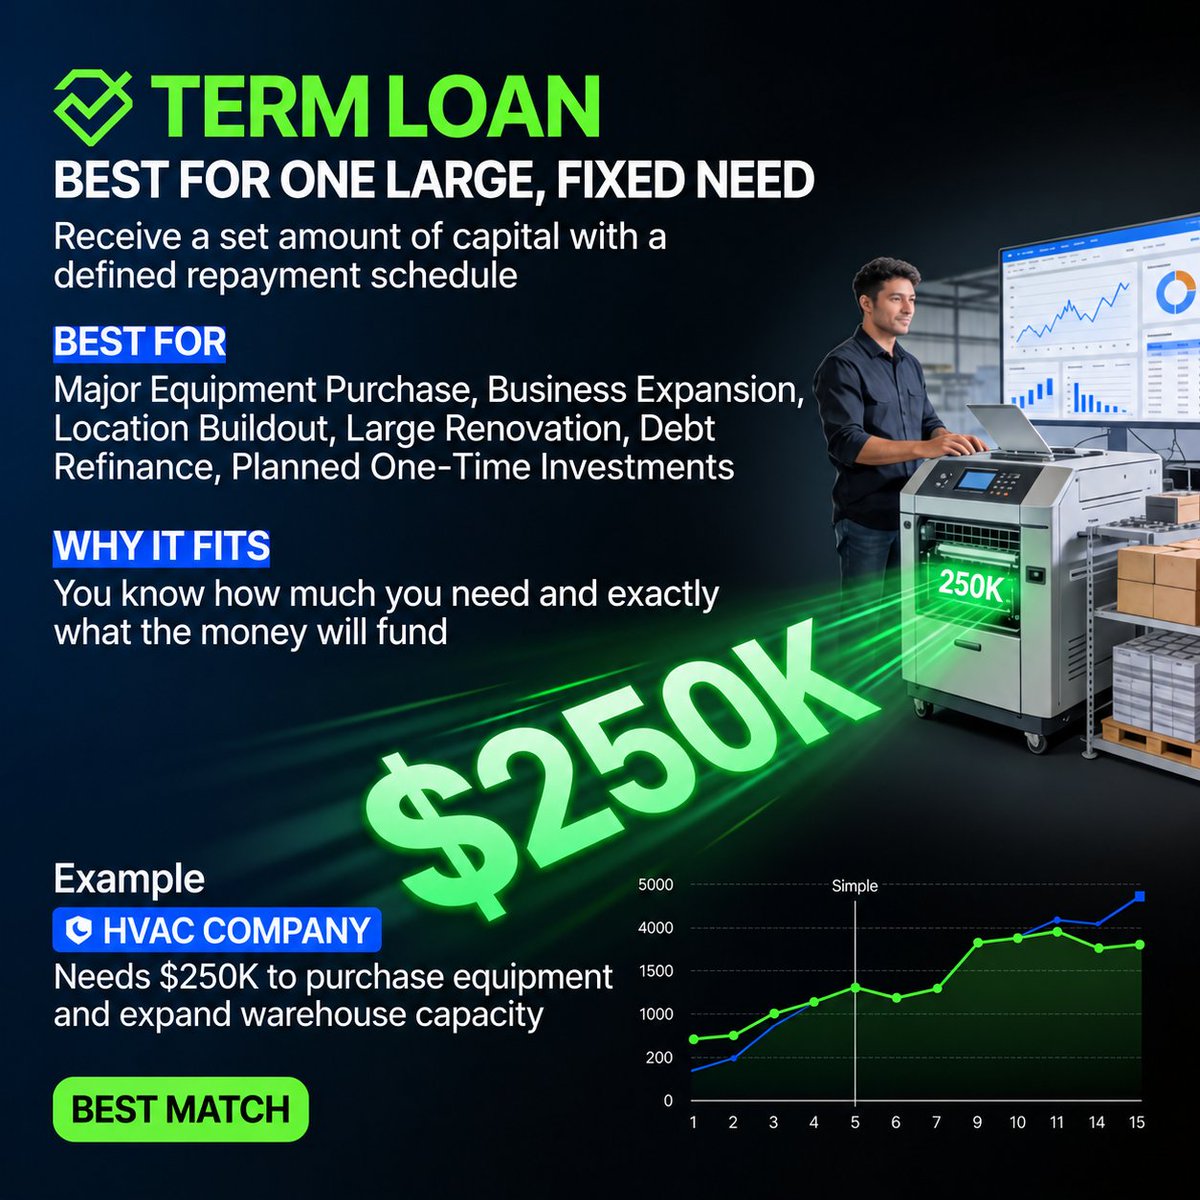
If you're funding one major purchase, expansion, or project, a term loan may be a better fit.
The simple rule:
🔵 Recurring need = Line of Credit
🟢 One-time need = Term Loan
Your full financial profile still determines eligibility, but matching the financing to the expense is a good place to start.
Message "LOC" or "TERM" and tell us your industry.
Visit https://t.co/72Fd0r5aKO
#BusinessLoans #LineOfCredit #TermLoan #BusinessFunding #WorkingCapital #SeasonalBusiness #CashFlow #SmallBusiness
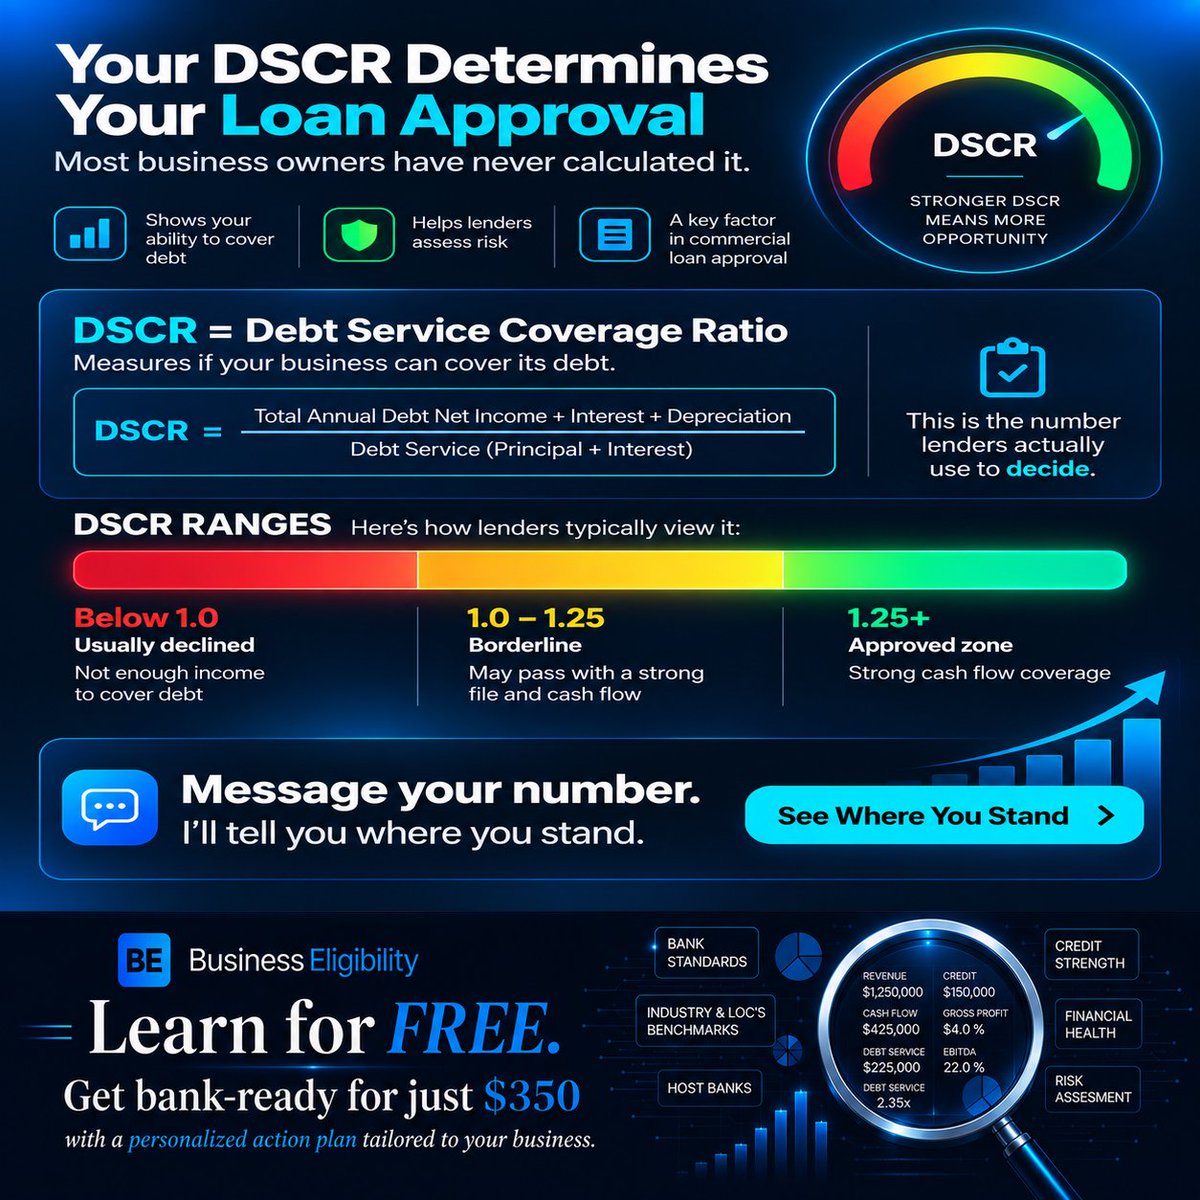
Revenue gets attention. DSCR gets reviewed.
A strong credit score doesn’t guarantee approval if your cash flow can’t comfortably support your existing debt.
Your DSCR helps show lenders how much room your business actually has.
Do you know yours?
Check out the free course at https://t.co/D84kDQAz8k
#DSCR #BusinessLoans #BusinessFunding #CashFlow #BusinessCredit #SBALoans #BankReady #BusinessEligibility
Turning Down a Bigger Loan Offer Was the Smartest Move One Client Made.
He qualified for $400,000.
He borrowed $220,000.
Why leave $180,000 unused?
Because the business did not need it.
Taking the full approval would have meant:
More debt
Higher payments
More interest
More pressure on DSCR
Less flexibility later
Instead, the loan was matched to the actual need.
That is called right-sizing the debt.
The biggest approval is not always the best deal.
Sometimes borrowing less puts the business in the stronger position.
Visit https://t.co/72Fd0r5IAm
#SBALoans #WorkingCapital #BusinessFunding #CommercialLending #CashFlowManagement #DebtRestructuring #BusinessLoans #SmallBusinessFunding #BusinessCapital #MCARelief
Using a personal loan to fund your business and obtaining business financing are two different structures.
With a personal loan, you are the borrower.
The debt is personally yours, even if every dollar is used for business expenses. It can affect your personal credit profile, debt-to-income ratio, and personal borrowing capacity.
With business financing, the financing is structured around the business and may be underwritten using business revenue, cash flow, financial statements, and credit.
But there is an important detail:
Business financing does not automatically mean zero personal liability.
Many commercial loans require owners to provide personal guarantees.
That is why you should understand five things before borrowing:
Who is the borrower?
Who guarantees the debt?
What collateral is pledged?
Where is the obligation reported?
What cash flow will repay it?
Do not compare only the interest rate.
Compare the entire financing structure and understand who is responsible for the debt.
#BusinessFunding #BusinessLoans #BusinessCredit #PersonalCredit #WorkingCapital #CommercialLending #BusinessFinance
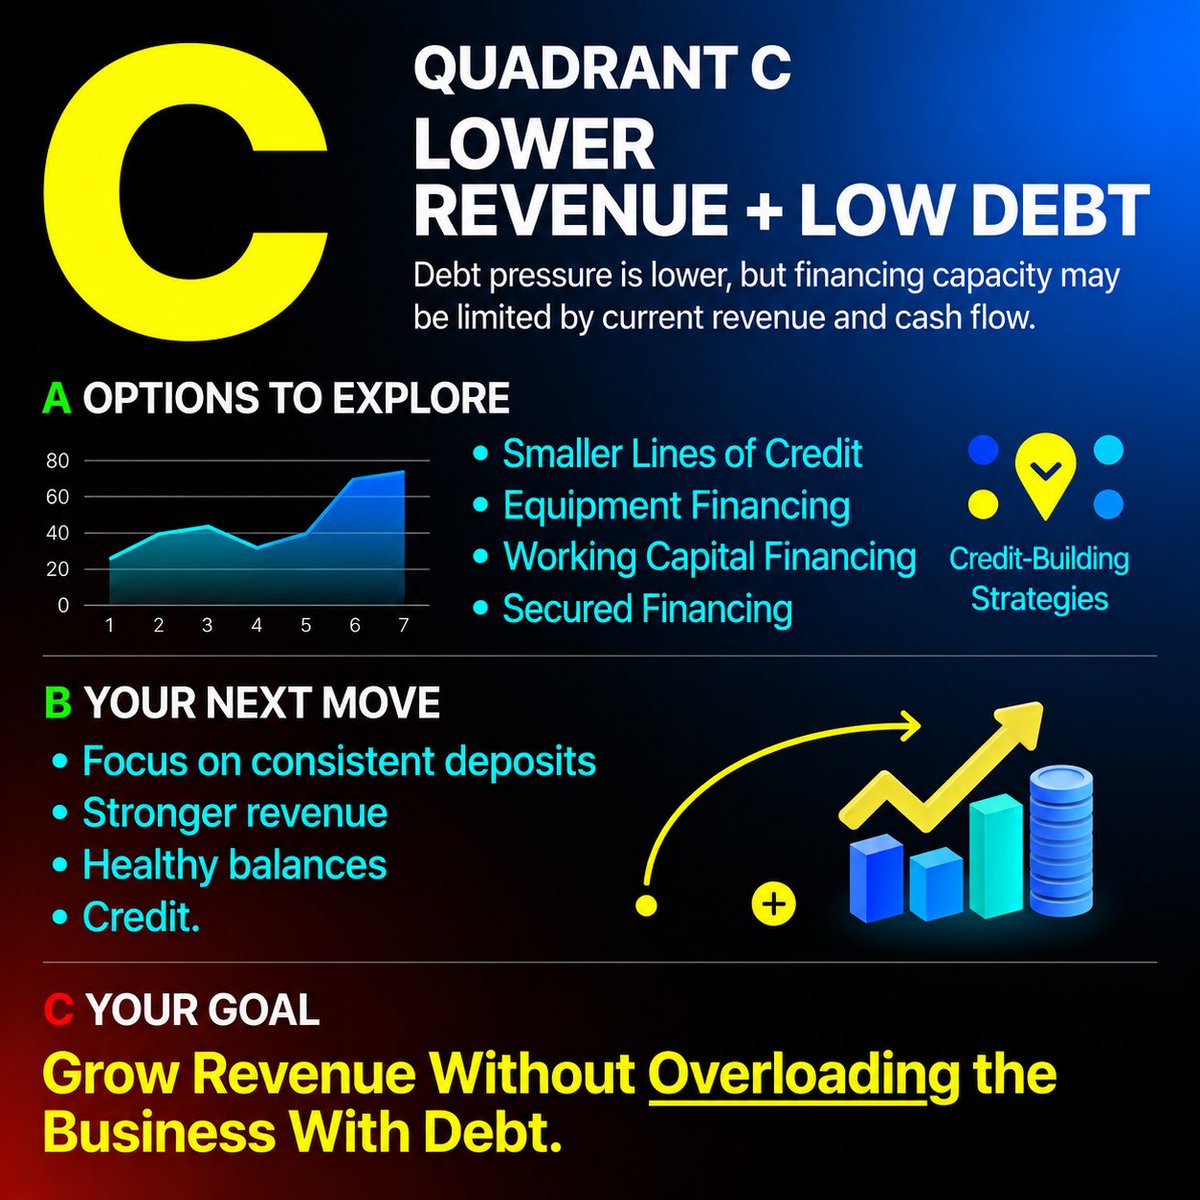
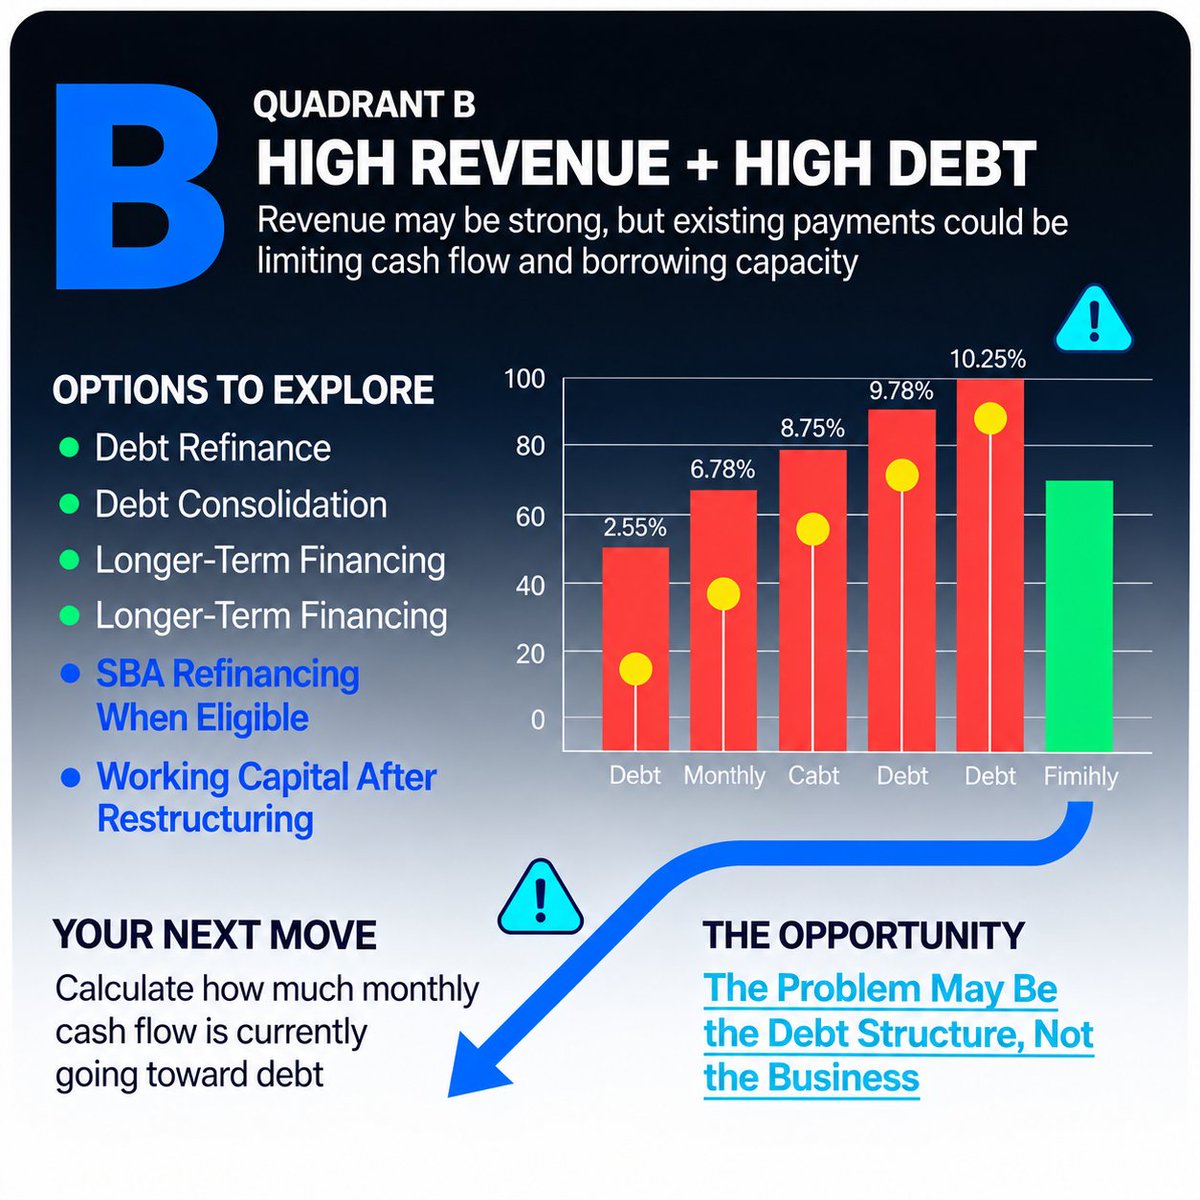
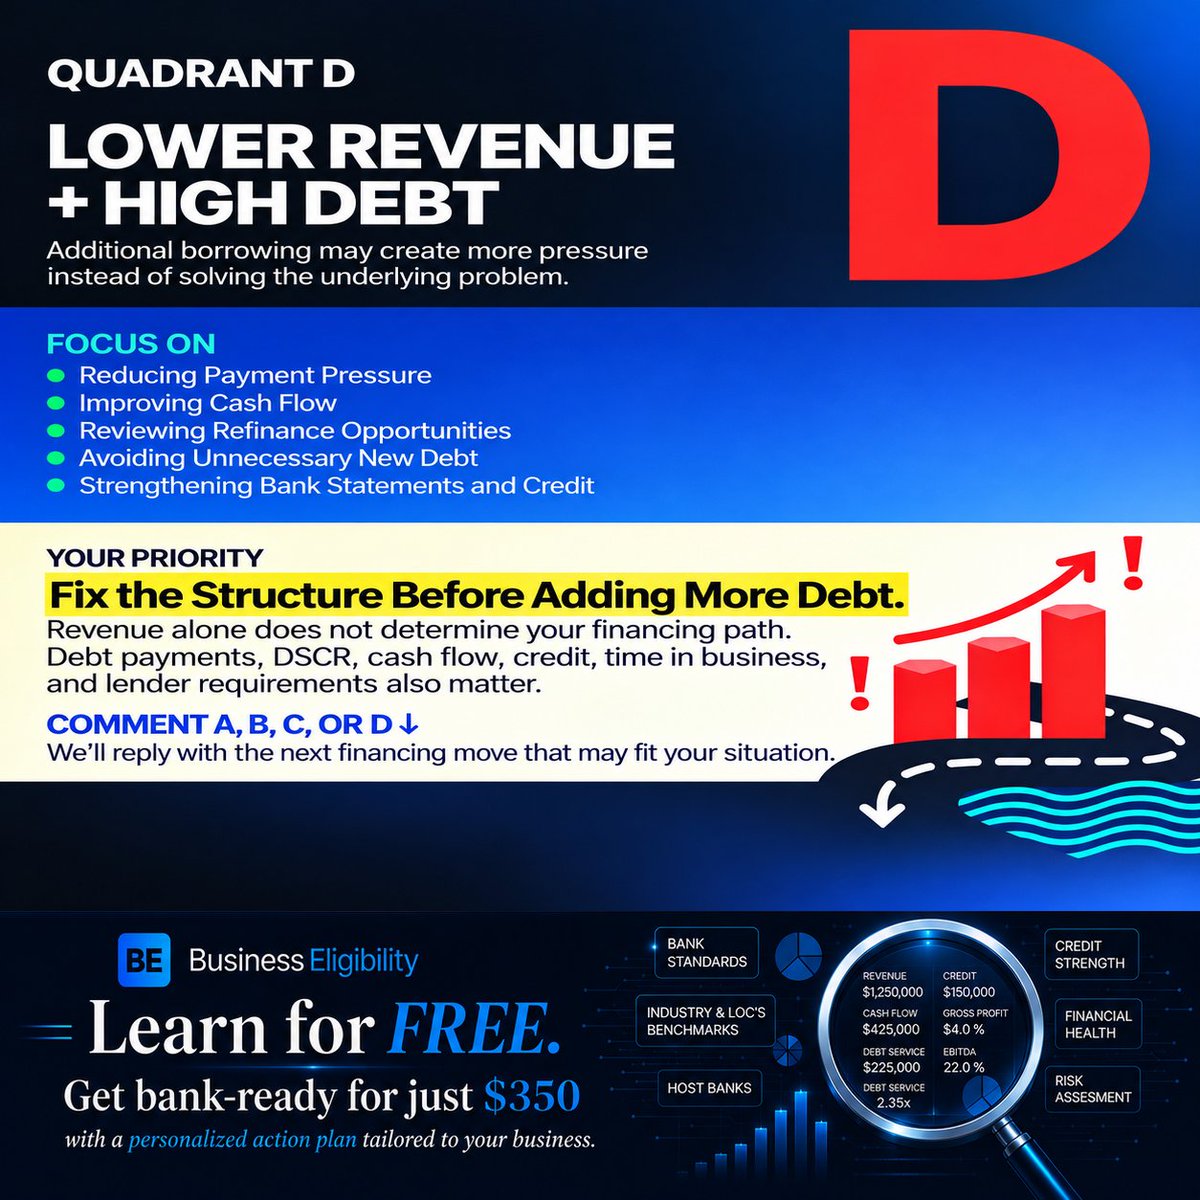
Why Two Businesses With the Same Revenue Can Get Different Loans
Your Revenue Doesn't Tell the Whole Financing Story
Two businesses can generate similar revenue and still have completely different financing options.
Why?
Debt structure.
A business with strong revenue and low debt may have a very different path than one generating the same revenue while carrying heavy monthly obligations.
That's why lenders look beyond revenue. DSCR, cash flow, credit, existing debt, and operating history all help shape the financing decision.
Which quadrant are you in?
Comment A, B, C, or D below and we'll tell you which financing direction may fit your situation.
#BusinessLoans #BusinessFunding #DebtRefinance #DSCR #CashFlow #WorkingCapital #CommercialLending #SmallBusiness
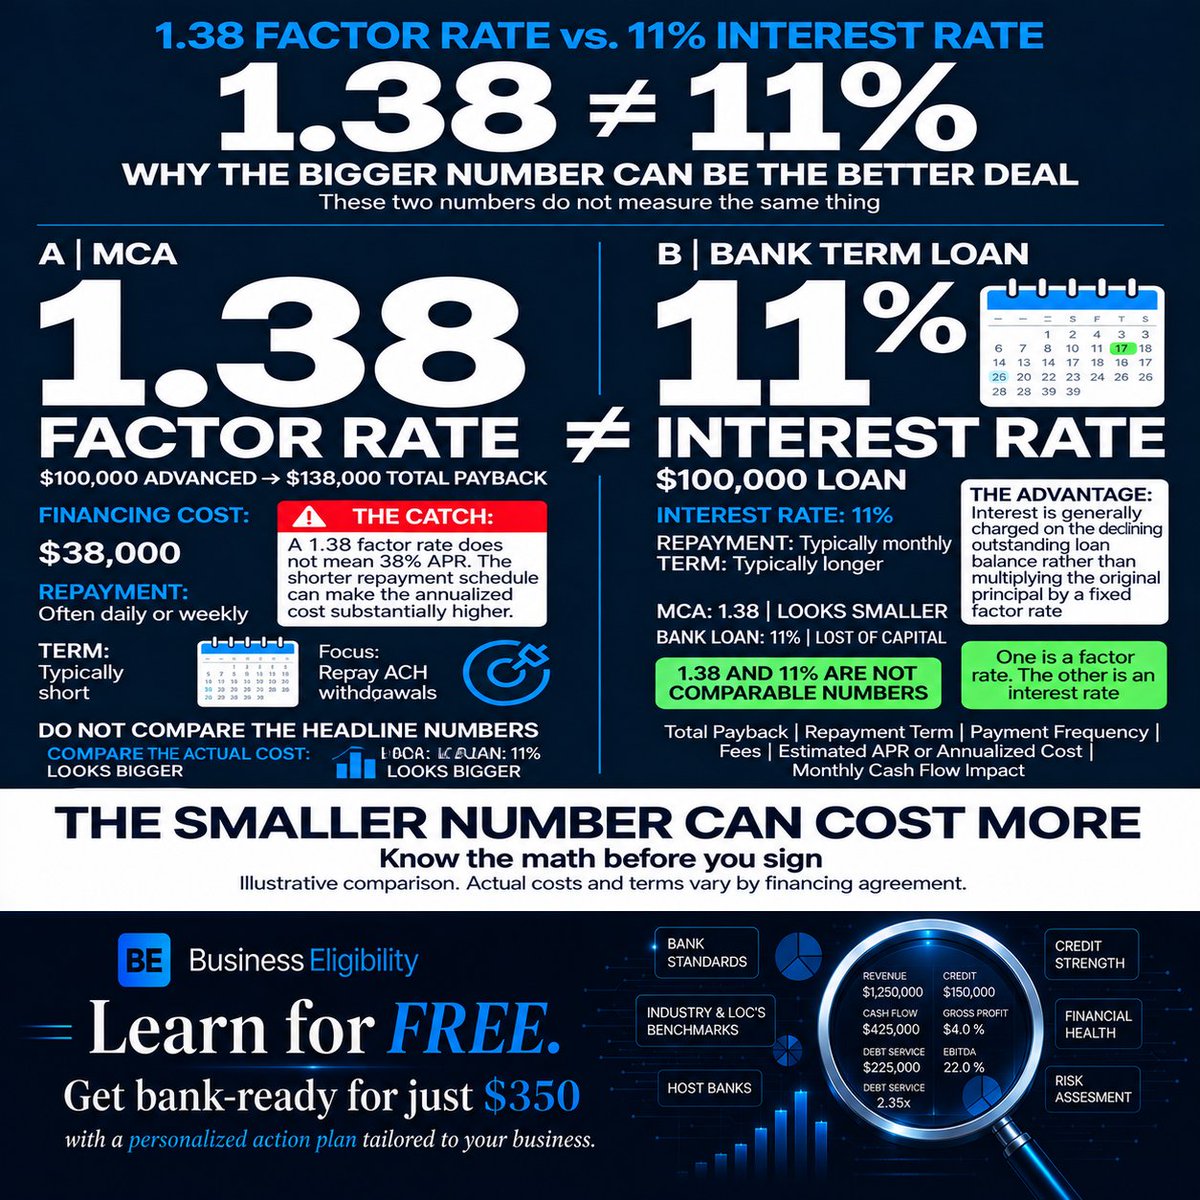
1.38 vs. 11%: Which Financing Is Actually Cheaper?
Which sounds cheaper?
1.38 or 11%?
At first glance, 1.38 looks smaller.
But they are not measuring the same thing.
With a $100,000 MCA at a 1.38 factor rate, the contractual payback is:
$100,000 × 1.38 = $138,000
That's $38,000 above the amount advanced, often repaid over a relatively short period through daily or weekly payments.
An 11% bank loan works differently. Interest is generally calculated based on the outstanding loan balance, with repayment commonly spread across a much longer term.
So comparing 1.38 directly with 11% can be misleading.
Before choosing financing, compare the total payback, repayment period, payment frequency, fees, estimated APR or annualized cost, and impact on cash flow.
The smaller-looking number can still be the more expensive financing structure.
Visit https://t.co/72Fd0r5aKO
#MCA #FactorRate #BusinessLoans #TermLoan #BusinessFunding #CashFlow #CommercialLending
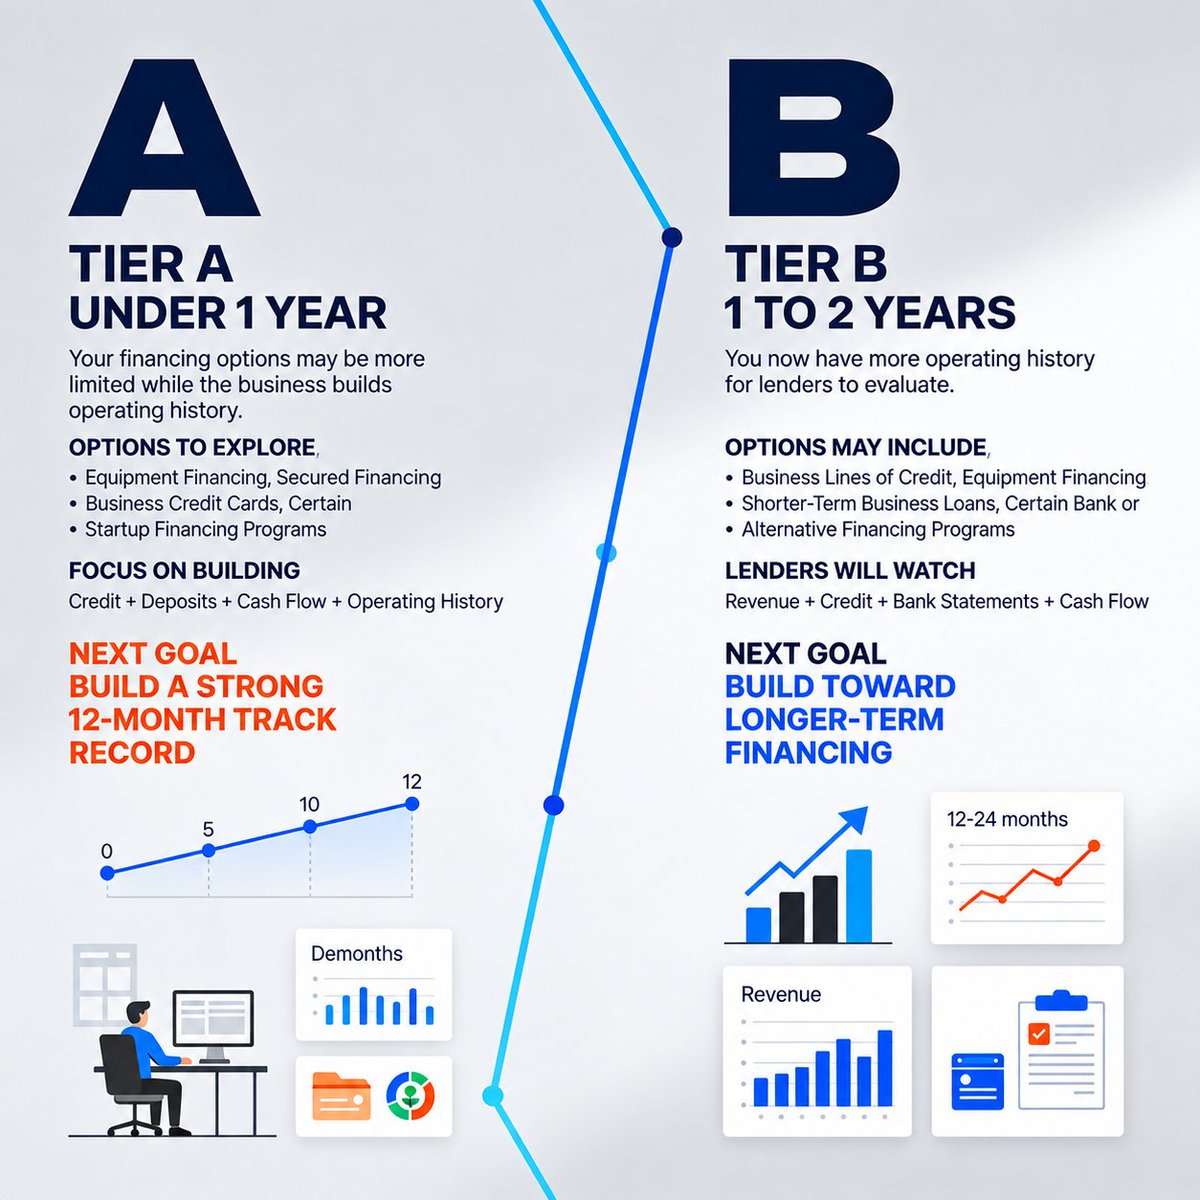
How Long Do You Need to Be in Business to Get a Loan?
How long has your business been operating?
Your answer can influence which financing options are worth exploring.
A: Under 1 year
B: 1 to 2 years
C: 2 to 5 years
D: 5+ years
Operating history matters, but it is only one part of the picture. Lenders may also evaluate cash flow, DSCR, credit, profitability, existing debt, and industry.
Comment A, B, C, or D below.
We'll tell you which financing options may fit your profile.
Visit https://t.co/72Fd0r5aKO
#BusinessLoans #BusinessFunding #SBA #WorkingCapital #BusinessCredit #DSCR #CommercialLending #SmallBusiness
Gym Owner's Equipment Lease Payment Was Eating His Membership Revenue. Here's the Fix.
Marcus T.’s fitness studio was carrying:
An equipment lease
An MCA
Both were hitting the same membership revenue every month.
The solution was to restructure the obligations into one equipment-secured term loan.
Result:
$3,100/month freed up
$37,200/year back into business cash flow
That monthly difference can go toward:
Payroll
Marketing
Equipment maintenance
Member growth
Operating reserves
Sometimes the problem is not how much debt the business has.
It is how that debt is structured.
Visit https://t.co/72Fd0r5aKO
#SBALoans #WorkingCapital #BusinessFunding #CommercialLending #CashFlowManagement #DebtRestructuring #BusinessLoans #SmallBusinessFunding #BusinessCapital #MCARelief
One conversation can start a deal. Integrity Cap and IntegriTech help connect what happens next. 🚀
From scheduling meetings and sharing documents to AI-powered financial analysis, deal tracking, and borrower communication, everything stays connected in one lending workflow.
With Integrity Cap’s funding expertise and IntegriTech’s technology, teams can move from application to underwriting with greater structure, visibility, and efficiency.
Keep conversations connected. Keep files organized. Keep borrowers informed.
▶️ Watch the video and see how it all comes together.
Integrity Cap + IntegriTech, Technology meets lending expertise.
#IntegriTech #IntegrityCap #FinTech #LendingTechnology #BusinessFinancing
This Month's SBA Priority Review Batch Has 6 Spots Left.
This month’s SBA Priority Review Batch has 6 spots left.
We only take a limited number of files into this review each month.
If you are considering an SBA loan, this is your chance to get your file reviewed before the current batch closes.
Priority review helps you:
Identify issues early
Position the file correctly
Match the deal to the right lender type
Move forward with more clarity
6 spots left
Once they are filled, new files move to the next batch.
If you want a spot in this month’s priority SBA review, reach out today.
Visit https://t.co/72Fd0r5aKO
#SBALoans #WorkingCapital #BusinessFunding #CommercialLending #CashFlowManagement #DebtRestructuring #BusinessLoans #SmallBusinessFunding #BusinessCapital #MCARelief
We Ran the Same Business Through 2 Different Lender Boxes. The Rates Weren't Close.
Same business profile.
Same numbers.
Different lender.
Different result.
In this comparison, we kept the borrower profile exactly the same:
Industry
Revenue
Time in business
Credit profile
Requested amount
Then we ran it against two different lender criteria sets.
The rate changed because lenders evaluate risk differently.
Pricing can depend on:
Industry appetite
Credit requirements
Loan size
Time in business
Risk tolerance
Available term structure
The borrower did not change.
The lender did.
That is why applying to the right lender can matter just as much as having a strong business profile.
Visit https://t.co/72Fd0r5aKO
#SBALoans #WorkingCapital #BusinessFunding #CommercialLending #CashFlowManagement #DebtRestructuring #BusinessLoans #SmallBusinessFunding #BusinessCapital #MCARelief
The Renewal Offer Your MCA Lender Sends Right on Schedule Isn't a Reward.
The Renewal Reward Trap
That top-up offer showing up when your MCA balance gets low is not random.
It often arrives at the exact moment when:
You feel close to the finish line
Cash flow is still tight
You are most likely to say yes
What the renewal often does:
Restarts the repayment clock
Extends the expensive debt timeline
Increases total payback
Prevents the business from actually getting free
It feels like help.
But many times it is just the cycle resetting itself.
Before you renew, ask:
Is this helping me finish the debt?
or
Is it putting me right back into it?
That is the renewal reward trap.
Visit https://t.co/72Fd0r5aKO
#SBALoans #WorkingCapital #BusinessFunding #CommercialLending #CashFlowManagement #DebtRestructuring #BusinessLoans #SmallBusinessFunding #BusinessCapital #MCARelief