@sashayanshin how can you know that ? i work in automotive, and the majority of my colleagues would ditch their cars, or at least own just 1 if there would be a cheaper alternative. Ofc waiting for a cybercab 15 min is Nok, but under 5 is perfect. I wouldn't say Elon is wrong, it's to hard
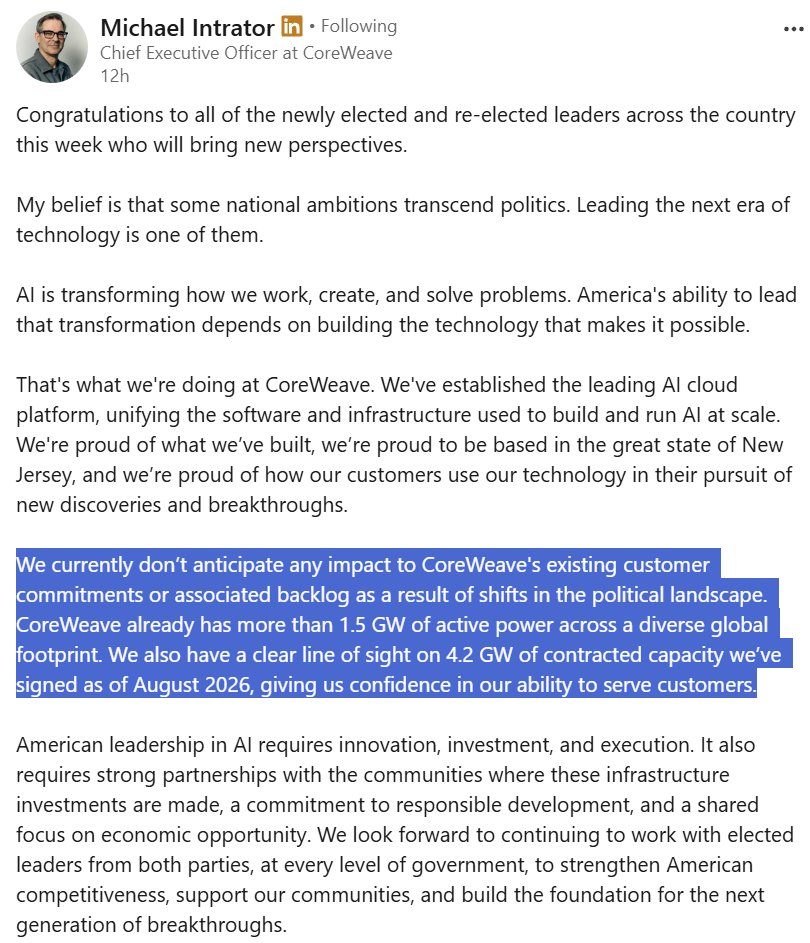
$CRWV says pricing for its older $NVDA Ampere and Hopper GPUs rose 30% to 50% last quarter and now exceeds their original contract rates with new deals extending beyond chips depreciable lives.
That makes the ~300K GPUs coming off contract through 2028 particularly interesting as renewing them at today’s prices could generate ~$10B in ARR without any new GPU capex.
$AMZN just unveiled a $250 Ring drone that autonomously maps your home, navigates around obstacles and investigates triggered alarms.
And I think thiss where physical AI gets really interesting because affordable, purpose-built robots could reach millions of households long before humanoids become mainstream.
@FredLambert@Gfilche not getting invited to a summit in which you are denigrated and GM being pushed as the leader of EVs when it actually sold less than 100 EVs was a fuck you Elon, yes. If you don't see that as bullying, i'm sorry really. Also remember the Lorena Gonzalez 2020 tweet ? "F*ck Elon"?
@FredLambert@Gfilche so you are saying dems fucked Elon, and Elon spent 5 years to fuck back. If you are getting bullied then the only solution is to fight back. Elon fought back. you are saying he shouldn't f fought back ?
@jiahanjimliu you do realise if the stock goes up every shareholder benefits right ? not just Elon ? you do realise that we need to advance technologically right ? you do realise blocking terrestrial data centers pushes them to space right ?
If you sponsor this podcast, calling for the execution of Elon Musk, I will never use your product… and will buy from both of your top two competitors
This is unacceptable and dangerous.
This a dog whistle to murder someone because you disagree with them — and this is the same guy who joked about the assassination against President Trump.
Fuck this piece of shit.
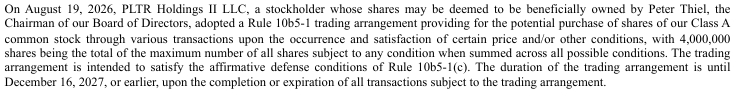
Peter Thiel has set up a plan to buy more $PLTR stock after reducing his stake for years. Every other insider plan in the 10-Q is for selling.
This would allow his holding company to potentially buy up to 4M shares until December 2027.
He already owns about 98M shares. This would add about 4% more.
Steven Bartlett asks James Talarico how Texas chases “equality” without chasing off figures like @ElonMusk.
Talarico’s answer: Musk’s net worth is a “spiritual sickness,” and the rich should pay something closer to the 1950s rate of 90%.
BARTLETT: “What would you have done to stop [Elon from becoming a trillionaire]?”
TALARICO: “We at one point in this country, we had, I think it was in the 1950s, had a top marginal tax rate of 90%. I don’t think it needs to be that high, but we used to have a political system and an economic system that more fairly distributed the fruits of our labor.”
“And I think the thing that really upsets people, particularly about the Elon example, is that Tesla was successful because of taxpayer dollars, right? Tesla got investment from the federal government, which is why it has been so successful.”
CONTEXT: The taxpayer dollars Tesla received were a LOAN from the Department of Energy in 2010. Ford got $5,900,000,000, and Nissan got $1,400,000,000 from the same program.
But Tesla did something those automakers hadn’t. It repaid the full $465,000,000 it had borrowed, with interest, 9 years ahead of schedule, becoming the first automaker in the program to pay its loan back in full.
@SPetrovic2448@wallstengine the thing is in such cases, there are committees of bankers who to the best of their knowledge figure out the worth of a company and decide from both sides the actual transactional price. ofc shareholders are entitled to vote yes, but financially, the offer is the best it can be
Can I please meet the Special Committee of SpaceX and tell them in ten minutes why they have to make the best offer ever for the best company in the world?
Asking, because I dare, lol.
Please, just give me ten minutes.
I don't understand how people actually think we're in a tech & AI bubble.
I keep looking at these consensus earnings estimates and trying to understand why every selloff is supposed to mean the entire AI investment thesis is falling apart.
Look at what these companies are expected to earn and what investors are paying for those earnings at the prices in this chart:
$NVDA: EPS growing from $9.29 in FY27 to $21.38 in FY29. That’s 130% growth, with shares trading at 22x FY27 earnings and 9.6x FY29 estimates.
$AVGO: EPS growing from $11.68 in FY26 to $30.63 in FY28. That’s 162% growth, at just 10.6x FY28 estimates.
$ORCL: EPS growing from $8.14 in FY27 to $15.71 in FY29. That’s 93% growth, at 8.3x FY29 estimates.
$MSFT: EPS growing from $20.01 in FY27 to $29.50 in FY29. That’s 47% growth, at 17.7x FY29 estimates.
$META: EPS growing from $29.18 in FY26 to $40.03 in FY28. That’s 37% growth, at 15.4x FY28 estimates.
Those growth figures cover two fiscal years. They aren’t annual growth rates.
I have a hard time calling that a broad bubble. Several of these businesses are expected to deliver substantial earnings growth while trading at valuations that give investors a reasonable argument for owning them.
Of course consensus estimates aren’t guarantees. A low multiple on earnings that never materialize won’t protect anybody. These companies still have to execute and the spending on AI has to produce an economic return.
That’s where I believe the debate should be and anyone who this that the market is in trouble should be articulating why these earnings won't materialize.
Tell me why the earnings estimates are wrong. Tell me where demand breaks down, margins deteriorate, or customers stop spending. A red week on the screen doesn’t answer any of those questions.
I’m also not saying every company in this chart is cheap. There are meaningful differences and buying anything with “AI” attached to it is not an investment strategy.
For someone investing over the next three to five years this drawdown looks a lot more like an early holiday sale than evidence that the whole sector is a bubble.
If the earnings outlook holds up while share prices fall, I’m being offered those expected profits at a lower price. That deserves a closer look.
I don’t need to catch the exact bottom. I need to be comfortable with the business, the price I’m paying, and its ability to grow earnings over time.
Looking at these estimates, I see plenty of reasons to keep shopping.