Our quick take on the $FANG acquisition from Double Eagle for $5 B.
Diamondback indicating they are going to put rigs to work in the Barnett, and want to take out Double Eagle's interests before the PUDs convert to PDP and get even more expensive.
https://t.co/k9qRAW0xFk
We think Return on Average Capital Employed (ROACE) for the US E&P sector has temporarily peaked, as M&A resets the capital base going into 2027.
@EnergyCynic@SuicideBlonde_2 They have paid out an additional ~$7.5 billion in divs. >$12B of the acquisition spend was financed with debt. You could compare $35 B of equity spend with $55 B of current market cap plus $7.5 B of dividends over the period. Doesn't look bad at all.
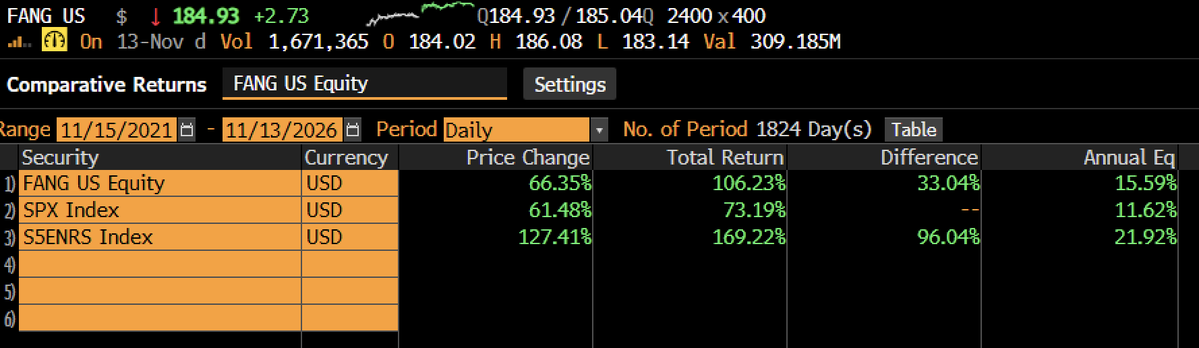
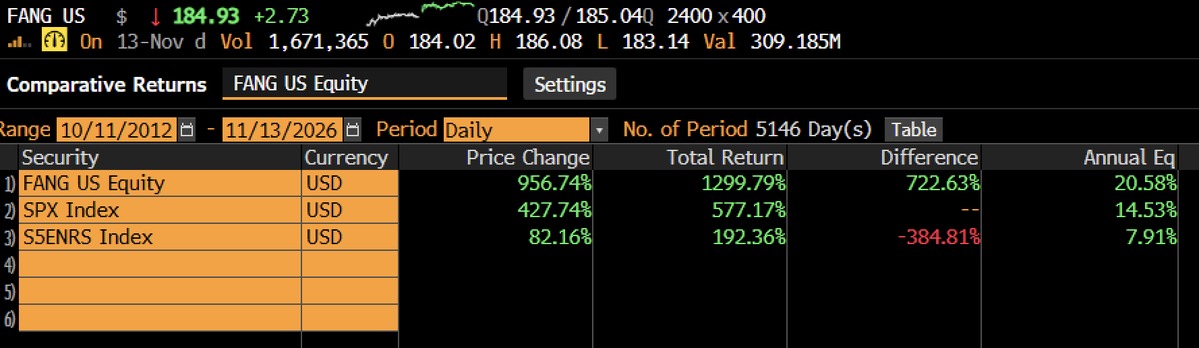
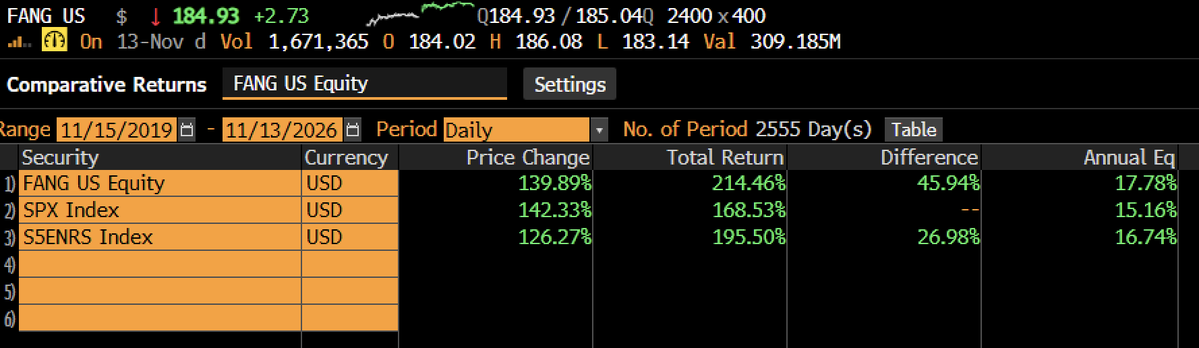
Interesting comment from @EnergyCynic. Ran some quick back of the napkin math in Excel. While no E&P returns can compare to the $SPY over the last 10 years, $FANG materially outperformed the $XOP on total return, with slightly higher vol but still a better Sharpe & Sortino.
$FANG has generated a trailing 10 yr return of 6.8%/yr (9% with divvies) and done a total of $50B in transactions (not including this deal) during that time frame
$52B market cap today and a $65B EV
@EnergyCynic@Brett_Novi 10-year is just one time frame and isn't by any means a definitive measure of value creation. Here's data on other equally valid timeframes:
Since $FANG IPO: 20.6% ($FANG) vs. 14.5% ($SPY)
Last 5 yrs: 15.6% ($FANG) vs. 11.6% ($SPY)
Last 7 yrs: 17.8% ($FANG) vs. 15.2% ($SPY)
Well performance in the sector peaked in 2020/21 in terms of productivity per foot. You can beat degrading inventory quality by improved D&C/opex cost structure, arresting base decline, and of course rising prices. It’s a relative game - how good relative to the rest of the sector - more than absolute.
Another banger from @trevor_rose_ with Chris Kalnin of $BKV
Listening to Chris describe the killer deal he did for $DVN’s Barnett in 2020, you can see why DVN is hesitant to fire-sale the Marcellus today.
https://t.co/lpvWthA1sl
Hart Energy on the Eagle Ford, with support from @novilabs M&A Intelligence and Basin Intelligence.
Murphy CEO: Devon Deal Says Eagle Ford Hotter Than Thought https://t.co/7hU75fwueA
I was at the @hartenergy A&D Strategies Conference in Dallas last week. It was a great event. I posted my notes and some discussion for Novi Intelligence clients.
We're bringing the conversations and insights from industry events directly to you.
For our first edition, we're recapping the 2026 @HartEnergyLive A&D Strategies & Opportunities Conference in #Dallas, where one theme stood out: scarcity.
More buyers and more capital are competing for fewer high-quality upstream assets, while transaction values continue to climb.
According to Novi M&A Intelligence, U.S. upstream M&A reached $87.2 billion across 93 announced deals through November 6, compared with $53.1 billion across 82 deals over the same period in 2025.
But the increase in deal value is largely driven by megadeals, including Devon-Coterra and EQT-Range, rather than a comparable increase in transaction volume.
Our first Novi Roadies recap explores the discussions shaping upstream dealmaking, from inventory-driven valuations and corporate consolidation to ABS financing and evolving transaction structures.
https://t.co/fhXmRL9uUx
Viper $VNOM announced more Midland Basin mineral/royalty acquisitions for nearly-$1 billion from Buckhorn Minerals and an undisclosed seller group.
https://t.co/kDUtzlSYE9
Outstanding episode from @trevor_rose_ with Chris Carter from NGP. Great history, great information, great insights, great conversation. Well done.
https://t.co/5vanEYIuAk