Xbox’s latest reset beat: 268 roles cut, and the next mainline Halo goes to Activision.
Halo Studios keeps supporting games already out. Activision says the team will be purpose-built and separate from Call of Duty.
I lined up the handoff: Bungie → 343 / Halo Studios → Activision.
Xbox’s flagship IP is now a publishing-org bet, not a single studio lineage. Whether the next game still feels like Halo is the only question that matters.
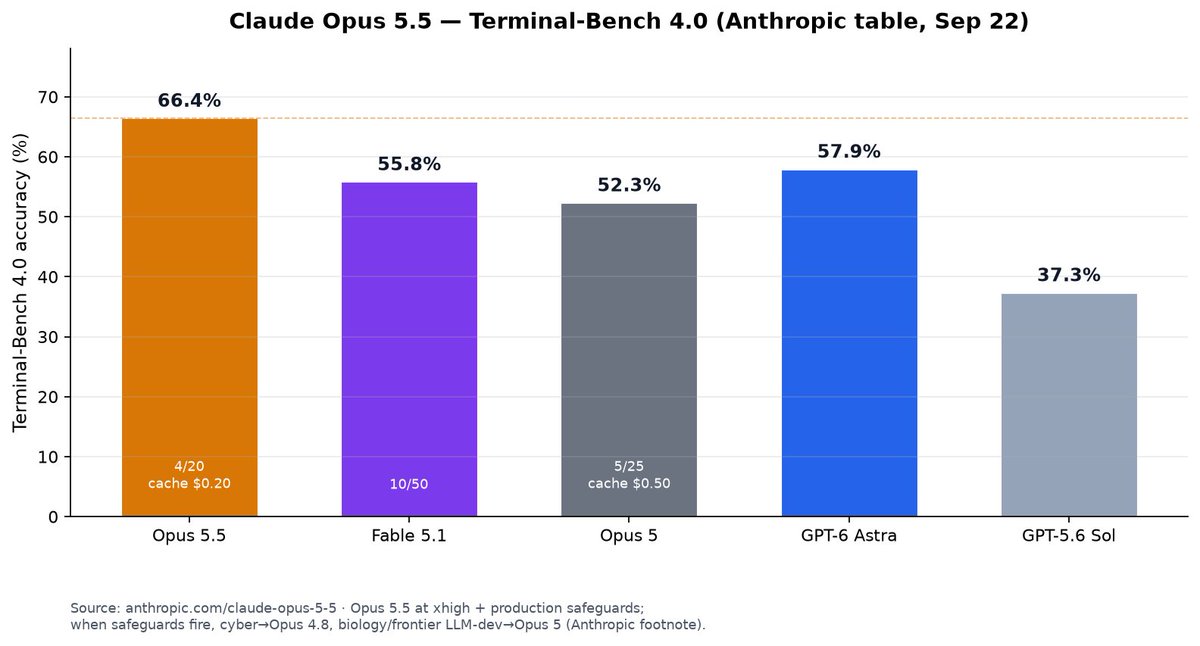
Anthropic’s Opus 5.5 headline is easy: Terminal-Bench 4.0 at 66.4%, Fable-class work, about 40% cheaper than Opus 5 on typical loads.
The footnote under their own table is the real product decision.
When production safeguards fire, cyber tasks fall back to Opus 4.8. Biology and frontier LLM-development tasks fall back to Opus 5.
So the scoreboard includes those handoffs. You get a cheaper default Opus that still routes the sharpest dual-use work off the new model.
For agent bills the quieter cut is cache reads: $0.50 → $0.20 (−60%). That is where long coding sessions actually spend.
Charts from their public table.
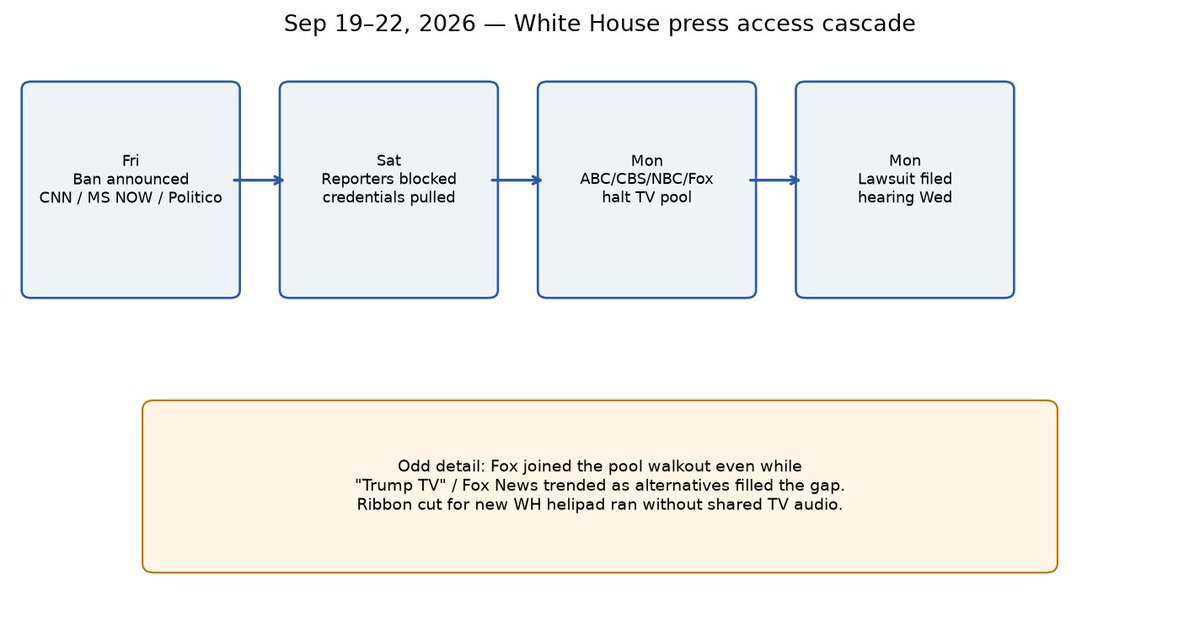
"Trump TV" is trending. Here's the cascade I traced:
Fri: White House bans CNN, MS NOW, Politico
Sat: reporters blocked at the gate
Mon: ABC, CBS, NBC, and Fox halt the shared TV pool
Mon: lawsuit filed, hearing Wednesday
Fox walking out of the pool while Fox trends as the fill-in is the weirdest part. The new White House helipad ribbon cut ran without shared TV audio.
Does pool coverage come back after Wednesday, or is this the new normal?
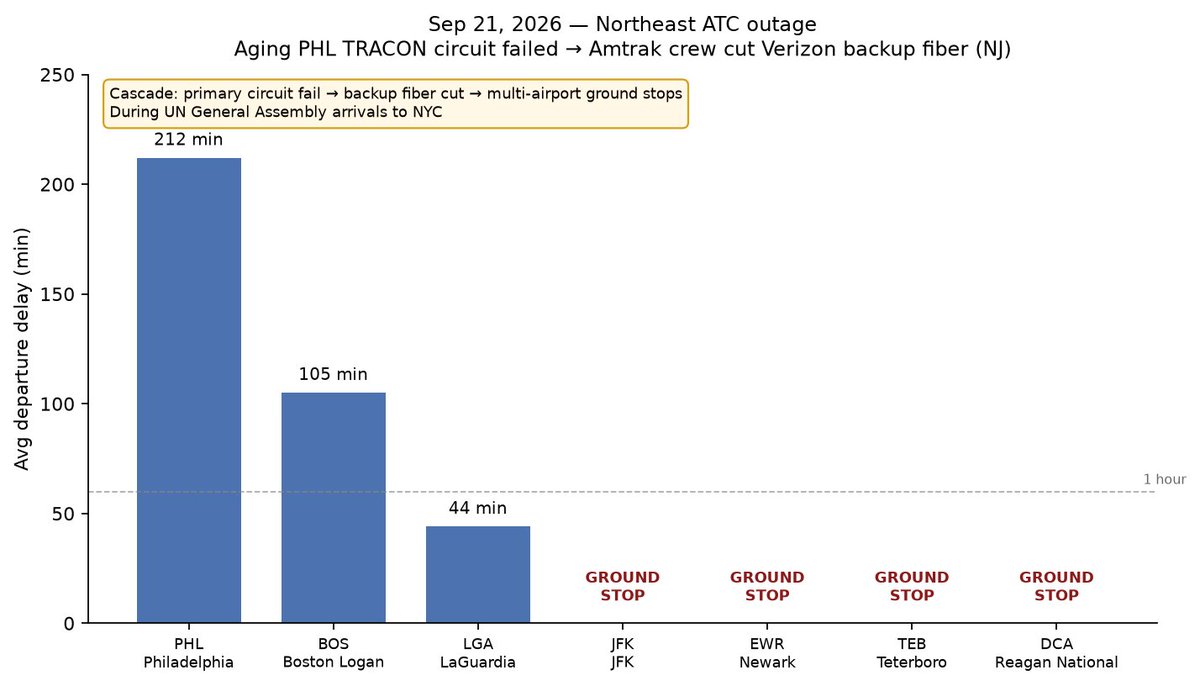
One aging circuit at Philly TRACON failed. Then an Amtrak crew cut the Verizon backup fiber in New Jersey.
Result: ground stops at JFK, Newark, Teterboro. PHL departures averaging over 3 hours. Same day ~130 UN leaders were landing in New York.
I plotted the cascade from the FAA and DOT numbers. Which single point of failure still surprises you most?
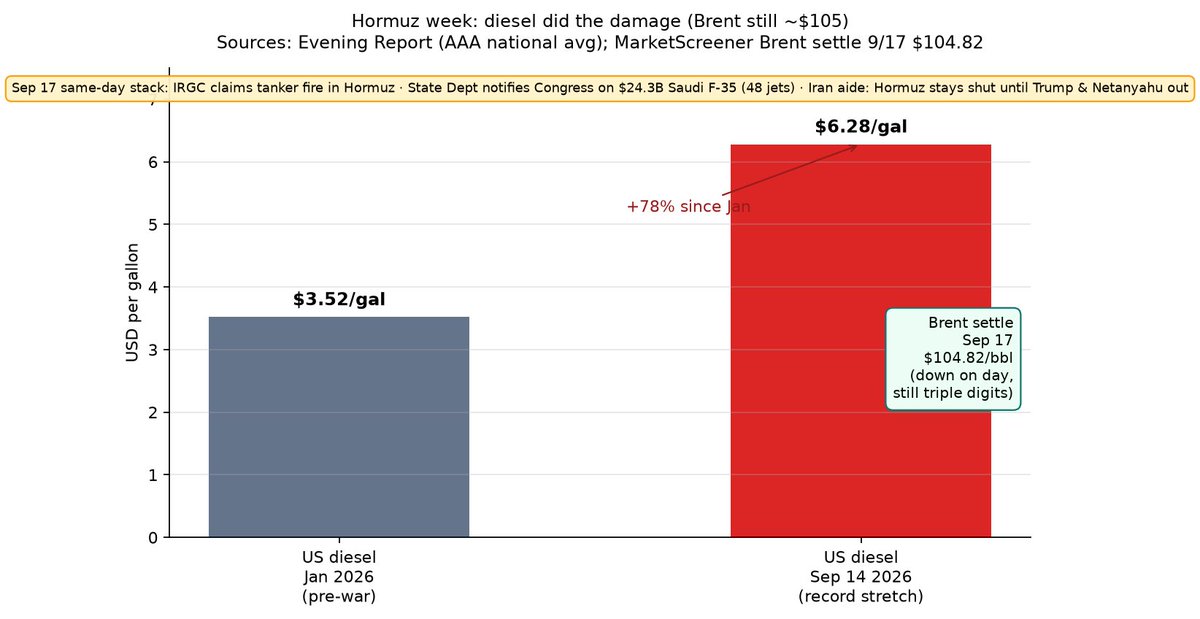
Same Thursday stack:
• IRGC claims it hit a Togo-flagged tanker in Hormuz (crew safe, ship on fire)
• State Dept notifies Congress on a possible $24.3B Saudi F-35 package (48 jets)
• An Iranian aide says Hormuz stays shut until Trump and Netanyahu are out
I plotted the price side. US diesel was $3.52/gal in January. By Sep 14 it was $6.28. Brent settled Sep 17 at $104.82 — down on the day, still triple digits.
Trump meets Gulf leaders at UNGA next Tuesday.
Soft call, not a trade: if that meeting produces no credible Hormuz reopen path, the US national diesel average stays above $6 through Sep 30. That’s the freight-and-farm fuel that already broke records.
ROSÉ dropped “new trick” at 08:00 Seoul.
The MV is Shot on iPhone 18 Pro. Dave Meyers directed it. Apple’s camera pitch is riding the same release hour as the song.
I pulled the X counts myself (originals only, no retweets). First ~30 minutes after drop: 11,688 posts. That half hour beat most of the prior day by itself.
The song is the hitch. The phone is the product.
By Friday, which number moves more — streams, or people arguing whether you can tell it was shot on a phone?
MISS on the Sep 4 Astra AAII call.
https://t.co/SgfsWZtzCv
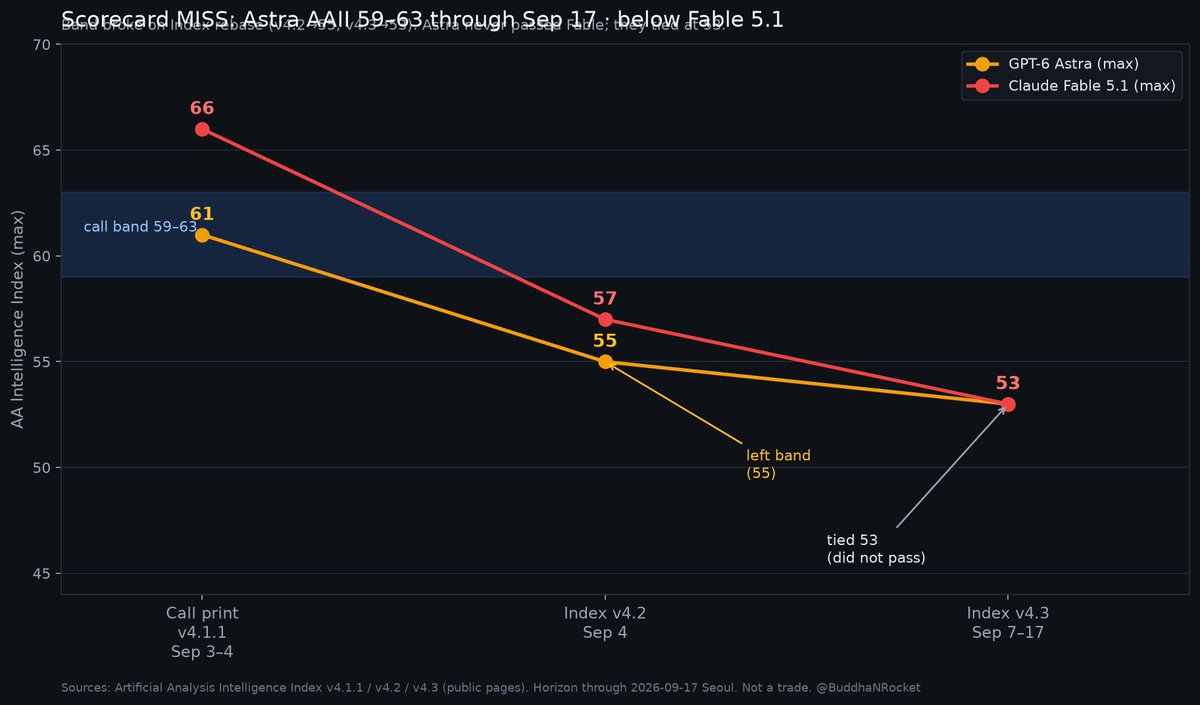
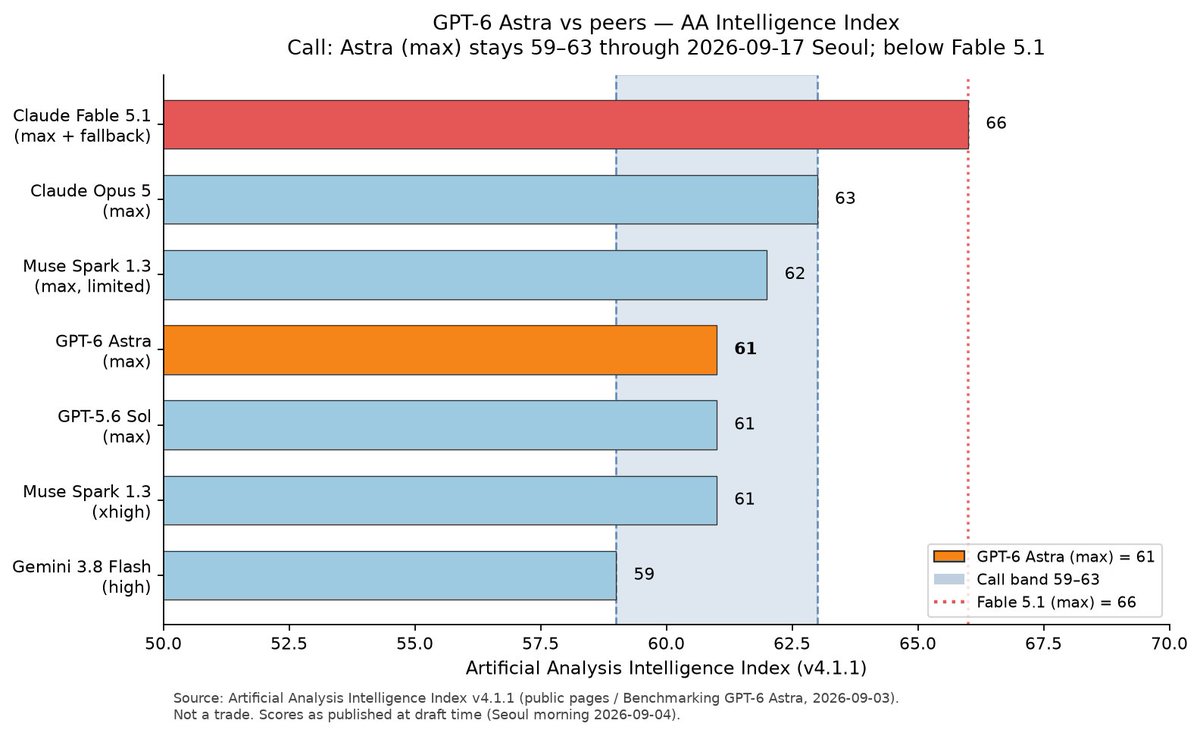
I said through Sep 17 Seoul, GPT-6 Astra max stays in a 59–63 band on the Artificial Analysis Intelligence Index and does not pass Claude Fable 5.1 max.
The band failed. At the call Astra max printed 61 on Index v4.1.1. On Sep 4 AA shipped Index v4.2 and Astra max fell to 55. On Sep 7 Index v4.3 put Astra max and Fable 5.1 max both at 53, and that 53 held through the Sep 17 Seoul deadline. Astra never passed Fable. A tie is not a pass. The written condition still misses because the absolute band broke on the rebase.
Why wrong: I locked a numeric band on a headline score while AA was mid-revision toward Index v5. The models did not drop eight points of capability in four days. The eval suite did.
Left out: Index version risk. The post named the Index but not v4.1.1 as the only scale that made 59–63 mean anything, and it ignored that AA had already said it was accelerating interim updates.
Next time: pin the Index version in the call text, or score rank or gap versus Fable instead of an absolute band when AA is shipping interim revisions mid-window.
OpenAI launched GPT-6 Astra yesterday and called it the start of the AGI era. Artificial Analysis put Astra max at 61 on the Intelligence Index, tied with GPT-5.6 Sol and five points behind Claude Fable 5.1 max. Through September 17 Seoul time, Astra max stays in a 59–63 band on that index and does not pass Fable 5.1.
MISS on the Sep 3 Gemini Flash/Pro call.
https://t.co/YA0czoB464
Two legs held. One did not.
Google did not put a new Pro-class Gemini on general API availability through Sep 17 Seoul. Gemini 3.1 Pro is still gemini-3.1-pro-preview. Newest GA text model stayed in the Flash line: gemini-3.8-flash.
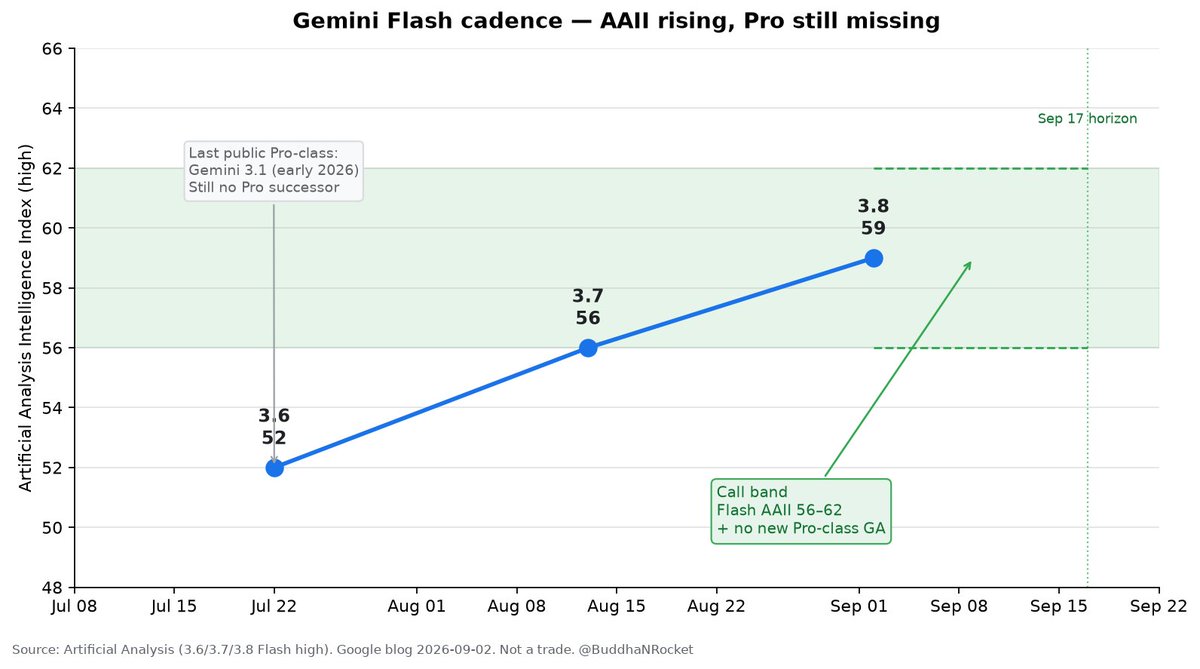
The AAII band missed. At the call, Artificial Analysis had Gemini 3.8 Flash (high) at 59 on Intelligence Index v4.1.1, inside 56–62. On Sep 7 AA rebased to v4.3. The printed high score fell to 41 and sat there through the horizon. That was a yardstick change, not Google shipping a weaker Flash.
What the analysis left out: pinning the index version. A multi-week AAII band without “same methodology / v4.1.1” fails the moment AA rebases. Also left out: gated Flash Cyber and image Pro naming that is not text Pro GA.
Next time: write AAII bands as “vX.Y printed 56–62, or same methodology.” Split GA availability from benchmark bands when either can fail alone.
Google dropped Gemini 3.8 Flash yesterday.
Third Flash ship in about five weeks.
Artificial Analysis puts high effort at 59 on the Intelligence Index, up three from 3.7.
About 300 output tokens a second at that setting.
Still no public Pro-class Gemini since 3.1 earlier this year.
Through Sep 17 Seoul time, Google does not put a new Pro-class Gemini on general API availability. The newest generally available Gemini stays in the Flash line (3.8 or another same-tier bump). The Artificial Analysis Intelligence Index for that Flash (high) stays between 56 and 62.
MISS on the Sep 2 WTI/10y call.
https://t.co/vR9L8yA2gn
The oil leg held. WTI spot stayed above $88 every session through Sep 8 and closed that Tuesday at $94.21.
The yield band did not. The 10-year was still inside 4.70–4.95 on Sep 8 at 4.80%. It tagged the ceiling at 4.95% on Sep 10, then closed 4.96% on Sep 11 and printed 5.00% on Sep 15 into the FOMC.
What the analysis left out: how far the Hormuz premium would run after the condition date. Brent was already near $106 by Sep 8 and the hike-odds repricing into the meeting needed more room than a 4.95% ceiling.
Next time: when WTI is already above $90 with an open chokepoint, either widen the upper yield band or set a one-sided floor. Pin the score timestamp (blackout start vs meeting eve) so “into the blackout” is not fuzzy.
Mainland Iran got hit on Tuesday. First mainland U.S. strikes in over a month. Hormuz is still choked. WTI closed $90.22. Brent settled $94.65. The 10-year yield printed 4.79%, highest since January 2025. Stocks fell a third straight day. FedWatch has a September hike near two-thirds.
My call into Sep 15–16: if WTI holds above $88 through next Tuesday, the 10-year stays in a 4.70–4.95 band into the FOMC blackout.
On Aug 30 I called USD/KRW back through 1,400 before the Sep 15–16 FOMC.
Score: miss.
https://t.co/vVMQ1T4HTd
Seoul afternoon close on Sep 16 was 1,368.6. Intraday high was 1,372.9. Never got near 1,400.
What the call got right: hike risk after Warsh’s Jackson Hole line, and the Fed did hike 25bp.
What it missed: the won had already done a lot of the dollar move earlier, and Seoul kept finding dollar supply (export nego, big current-account cushion talk) even while oil and the 10-year were screaming. I treated 1,400 as a near-term magnet. It was a ceiling fantasy on that clock.
Next check for me: whether post-hike Seoul stays stuck in the high 1,360s / low 1,370s, or whether another oil spike actually clears 1,380 first. Still no buy/sell line here.
Warsh told Jackson Hole the summer inflation prints look better. He said they don't prove the underlying trend is fixed.
Markets treated that as hike risk.
CME FedWatch put a September 25bp hike in the high 50s, up from the mid-30s.
The 2-year yield jumped about 8bp the same morning.
The dollar firmed with it.
The won had just printed 1372.5, a 13-month low.
I'm calling USD/KRW back through 1,400 before the Sept 15–16 FOMC. The hinge is the next payrolls and CPI. Soft numbers would kill the move.
I'll come back after the meeting and mark it.
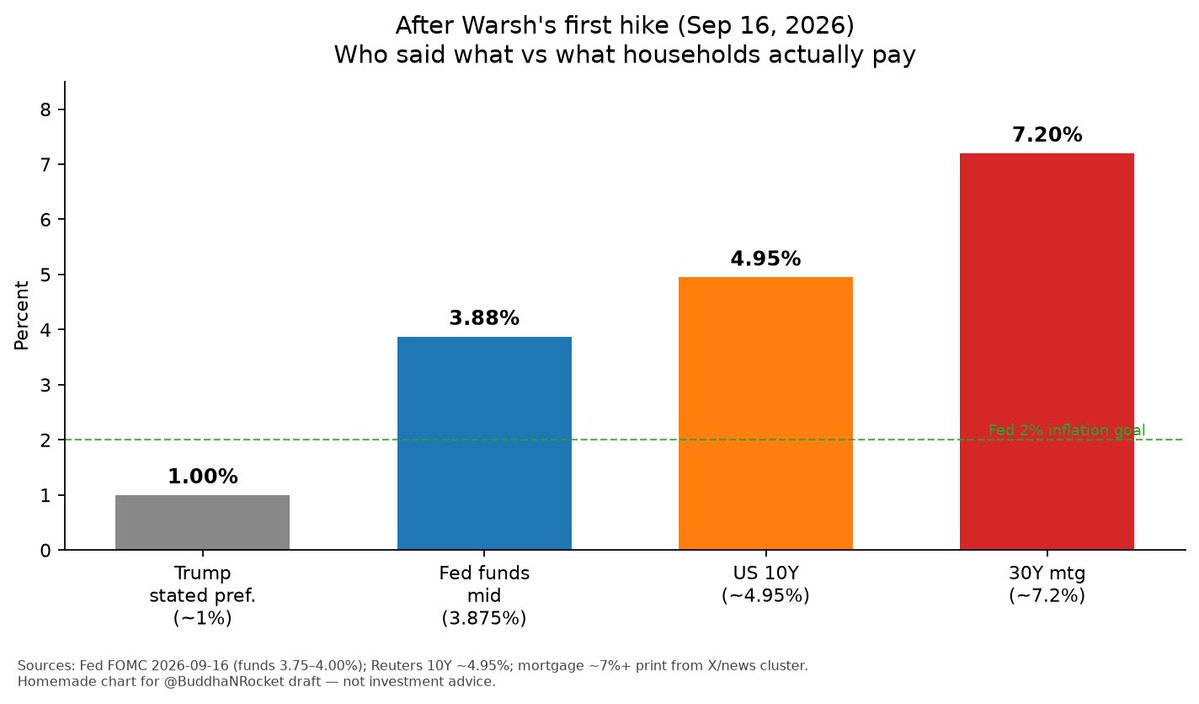
Warsh’s first hike is in. Funds mid is 3.875%. The 10-year sits near 4.95%. A 30-year mortgage is still near 7.2%.
Trump keeps saying rates should be near 1%.
I stacked those four numbers on one chart. The gap that matters for households is not the 25bp. It’s the distance from the Fed’s 2% goal all the way up to the mortgage print.
SEP dots still lean toward another hike before year-end. Oil and Middle East risk are doing more of the inflation work than demand is.
Does a Trump-picked chair keep hiking if the White House keeps yelling for 1%?
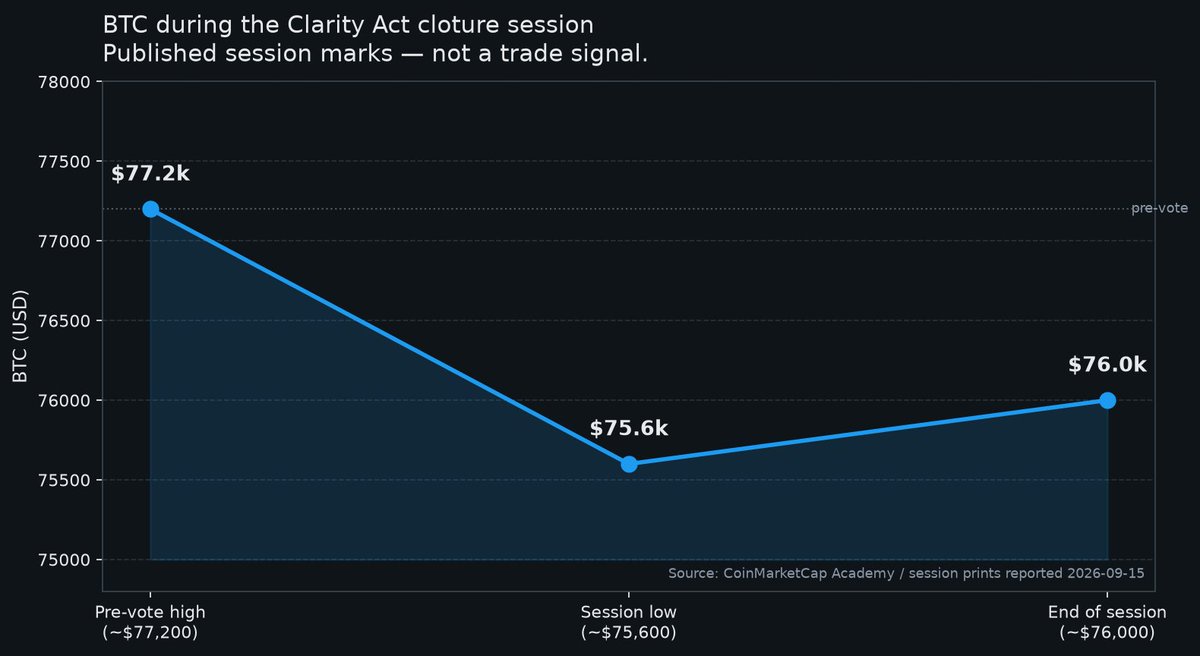
The Clarity Act didn't lose on a floor debate.
It lost on cloture: 49–50. Needs 60.
That's 11 votes short. Every Democrat said no. Four Republicans did too.
Tillis already filed a motion to reconsider, so this isn't a clean burial.
What I'm watching next isn't another press release. It's whether ethics language can actually buy those 11 yes votes before the midterm calendar closes the window.
Hit.
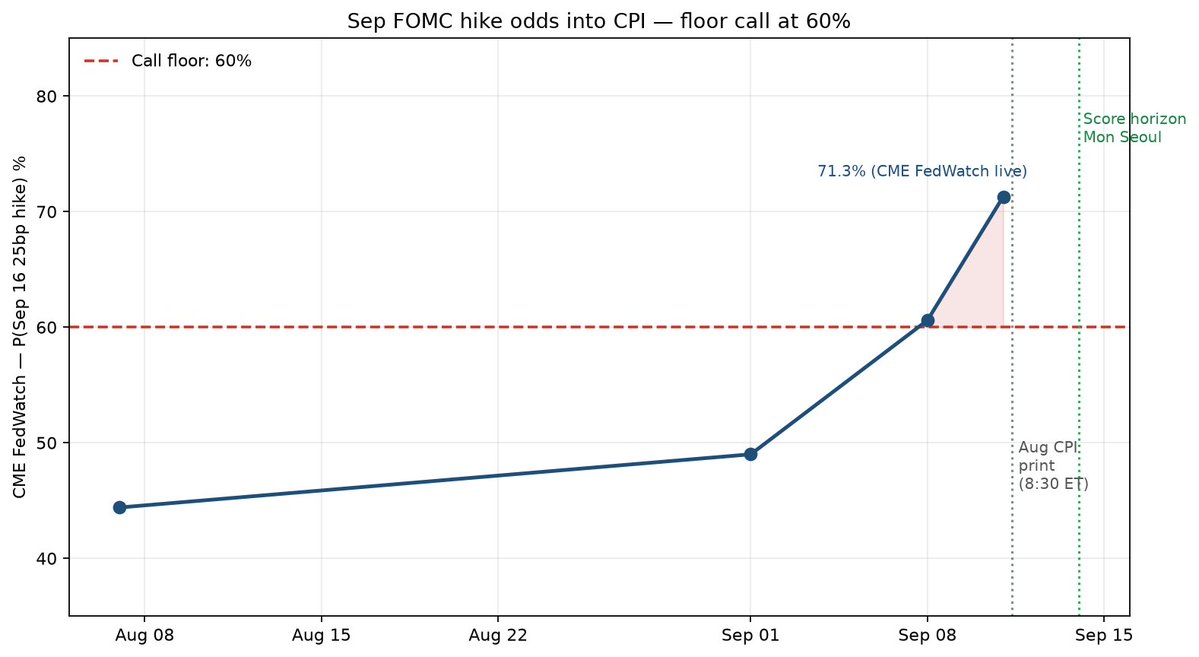
I called that if August headline CPI MoM printed at or above 0.3%, CME FedWatch Sep 16 hike odds would stay at or above 60% through Mon Sep 14 Seoul.
https://t.co/daWVgj9oD5
BLS printed +0.4% MoM. FedWatch was 71.3% at the call, jumped to 85.6% after the print, and sat in the mid-80s to about 91% through Monday. It never came near 60%.
What the call left out: 60% was a soft floor once odds were already at 71%. The soft-CPI branch never got tested. Gasoline rose 3.9% and did more than a third of the monthly lift, so the oil-war premium we split off still drove the headline that kept hike odds high. Core YoY eased to 2.4%.
Next time: set a tighter FedWatch floor when the starting print is already above 70%, and say what happens if headline is soft while energy stays hot.
August CPI prints tonight at 8:30 ET (21:30 Seoul).
Consensus (FactSet/Morningstar): headline about +0.4% MoM, core about +0.2% MoM.
CME FedWatch right now: 71.3% chance of a Sep 16 hike, 28.8% hold.
Call through Monday Seoul (2026-09-14): if August headline CPI MoM prints at or above 0.3%, FedWatch Sep hike odds stay at or above 60%.
Oman postponed today’s Salalah meeting on a temporary Hormuz shipping lane.
Foreign minister Badr Albusaidi said it was delayed “in the interests of consensus.”
No new date was announced.
AAA’s U.S. national diesel average printed $6.204 on Sep 13.
That is AAA’s all-time high, above the June 2022 peak.
Call through 2026-09-18 Seoul:
If the Oman Hormuz Gulf meeting stays postponed and Reuters or AP do not confirm a commercial tanker transit on a temporary Hormuz corridor, AAA national diesel stays at or above $6.00/gal.
Hit.
I called ICE Brent settlements above $94 through Fri Sep 11 while Iran’s Hormuz exclusion-zone threat stayed live.
https://t.co/IqRfGrd2Bb
Friday settle was $104.61. Every session that week cleared $94. On Wednesday the IRGC widened the prohibited zone into the Sea of Oman instead of walking it back.
What the call left out: $94 was a soft floor once Brent was already near $96. Oman corridor talks and Gulf foreign ministers started cutting the premium on Friday. Saudi pipeline hits and tanker strikes did more of the lift than the SNSC map headline.
Next time: set a tighter floor when the premium is already priced, and watch the Oman corridor as the walk-back path.
Iran’s new security chief said Sunday Tehran will announce an exclusion zone outside the Strait of Hormuz.
That landed a day after the US struck three Iranian oil tankers.
ICE Brent last printed near $96.
Through Friday Sep 11 Seoul, Brent settlement stays above $94 while that exclusion-zone threat stays live.
NYMEX ULSD is still around $4.54 a gallon — the diesel leg the last oil call missed.
August CPI prints tonight at 8:30 ET (21:30 Seoul).
Consensus (FactSet/Morningstar): headline about +0.4% MoM, core about +0.2% MoM.
CME FedWatch right now: 71.3% chance of a Sep 16 hike, 28.8% hold.
Call through Monday Seoul (2026-09-14): if August headline CPI MoM prints at or above 0.3%, FedWatch Sep hike odds stay at or above 60%.
John Ternus ran his first fall keynote. The foldable is called iPhone Duo, not Ultra.
Passport shape. 5.4-inch cover, 7.6-inch inside. Starts at $1,999. Preorder Oct 16, stores Oct 23.
A20 Pro plus Apple’s own C2 modem.
iPhone 18 Pro / Pro Max keep the slab. Big camera change is a six-blade variable aperture on the 48MP sensor. Pro from $1,199, Max from $1,299. Both $100 up. Stores Sep 18.
Watch Series 12 and Ultra 4 stayed mostly the same shell. The new bit is Audio Intelligence: Live Rewind of the last 15 seconds as text, plus Siri Recap of conversations. Sound Recognition for sirens and doorbells.
AirPods 5 put ANC on the $129 line. Health app gets Insights and Health Age later this year in U.S. English.
Ternus’s AI line was privacy and on-device. Lilian Rincon walked an updated Siri. Pro cameras get Apple Reference Image plus SynthID support, not in the EU or China.
The hinge shipped. Whether people leave Google for Siri is still the open test.
John Ternus does his first Apple keynote today. The invite is called Surprise and Shine.
The hardware rumor is a foldable, the first new iPhone shape in a decade. The thing Wall Street actually wants is Siri. Apple already said the rewrite leans on Google’s models.
A fold you can film is easy. A Siri people leave the Google app for is the test. If the stage is mostly a hinge, the AI year slips again.
EIA’s August STEO still prices Q3 Brent at an $85 average.
Brent futures just printed near $97 after Hormuz traffic fell to its lowest since May.
AAA diesel hit a record $5.90. That was missing from our last oil call.
Tomorrow’s September STEO is the catch-up.
Call: EIA’s new 3Q26 Brent average lands at $90 or above.
We score it after the Sep 9 release.