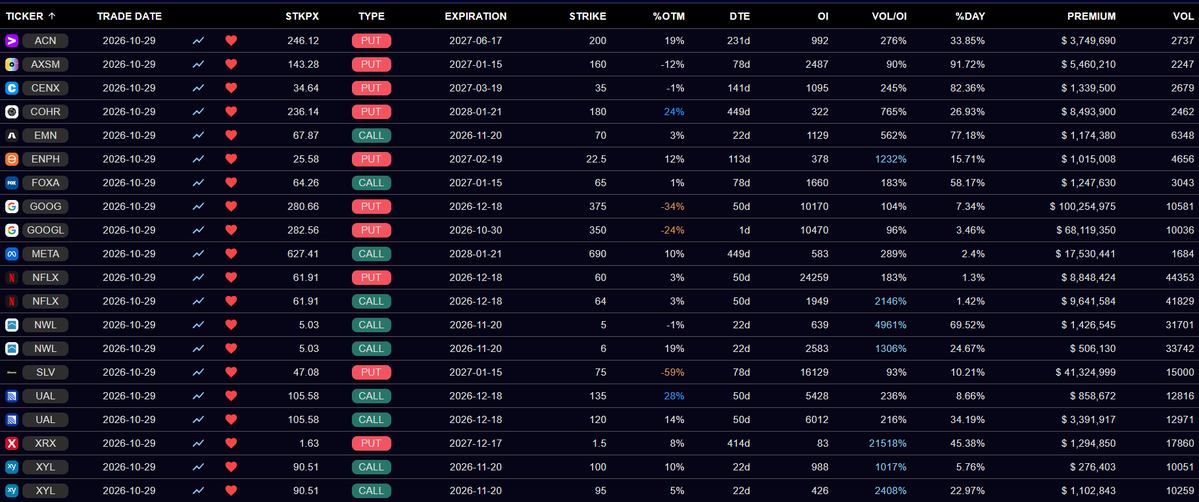
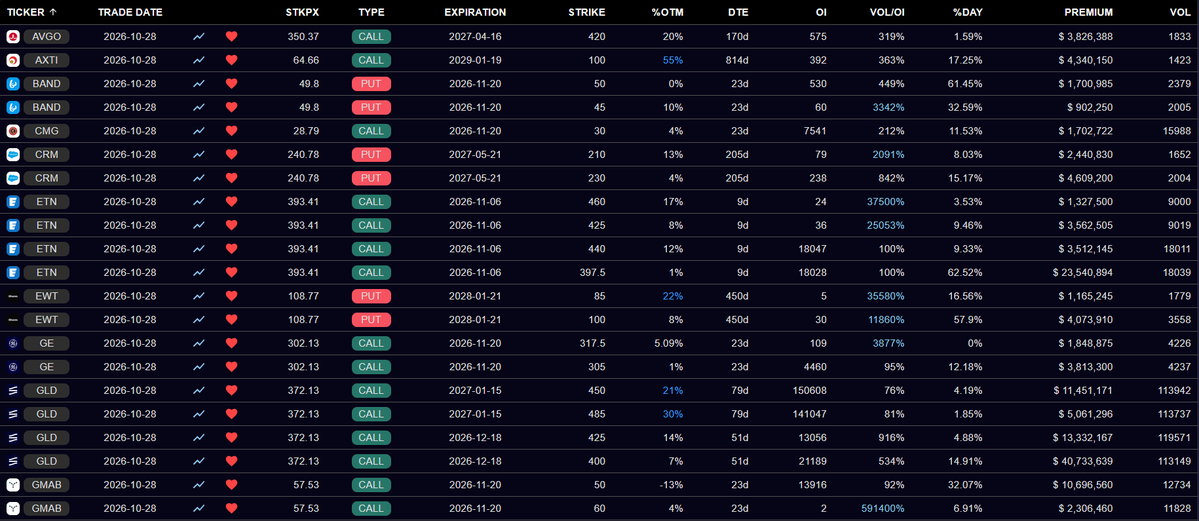
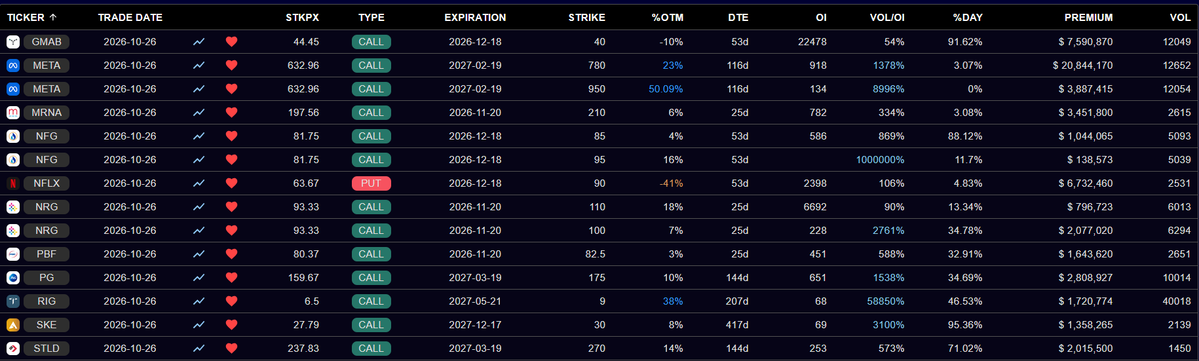
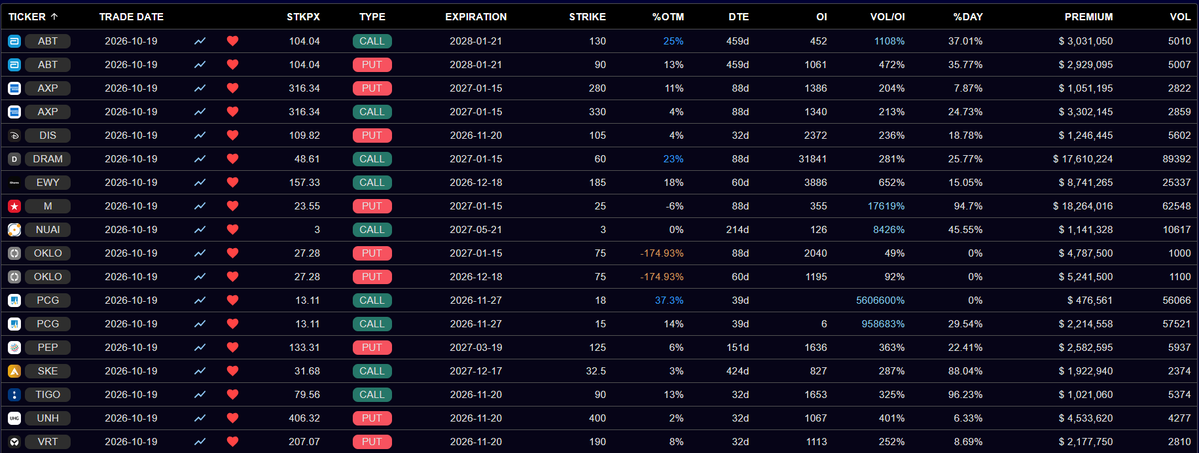
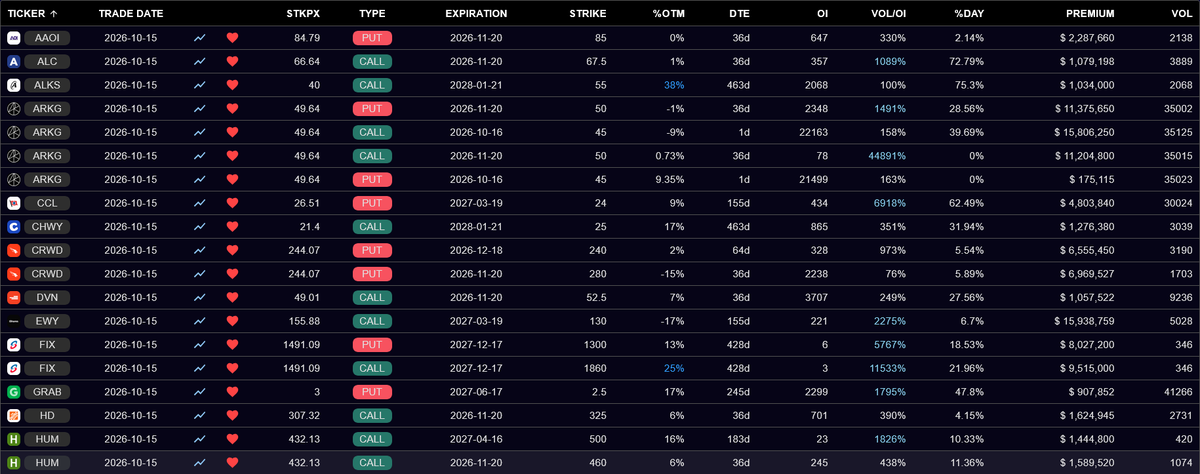
10/28 flow
$AVGO sold calls
$AXTI sold calls
$BAND put spread
$CMG calls
$CRM sold puts
$ETN profit take C spread -> new C spread
$EWT put spread 👀
$GE sold call spread
$GLD profit take short C spread -> long C spread 👀
$GMAB insider trader whale profit take and small roll
$GMAB large call 50% profit take
$META call spread
$MRNA calls
$NFG call spread
$NFLX put profit take
$NRG call spread
$PBF calls
$PG sold calls
$RIG sold calls
$SKE calls
$STLD sold calls
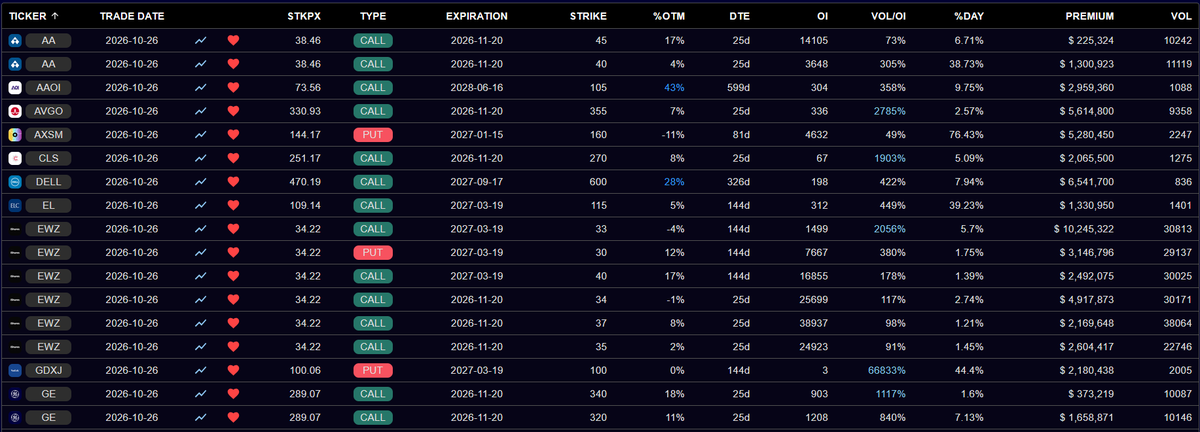
10/26 flow
$AA short call close -> long call
$AAOI calls
$AVGO calls
$AXSM large put 50% profit take
$CLS sold calls
$DELL calls -
$EL calls
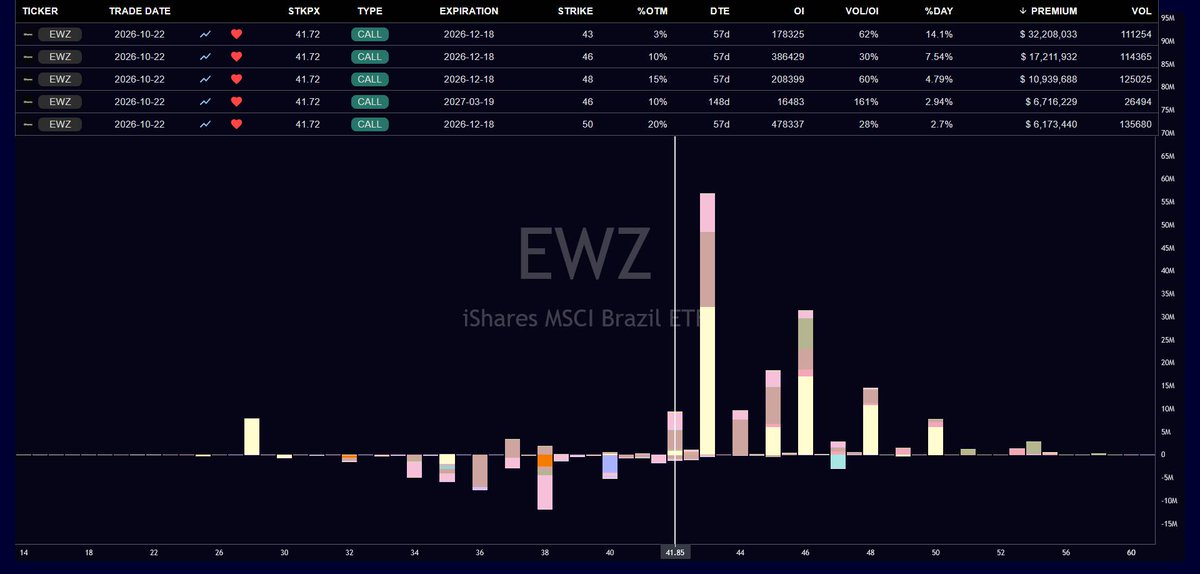
$EWZ cut calls + financed call spread
$GDXJ sold puts
$GE call spread
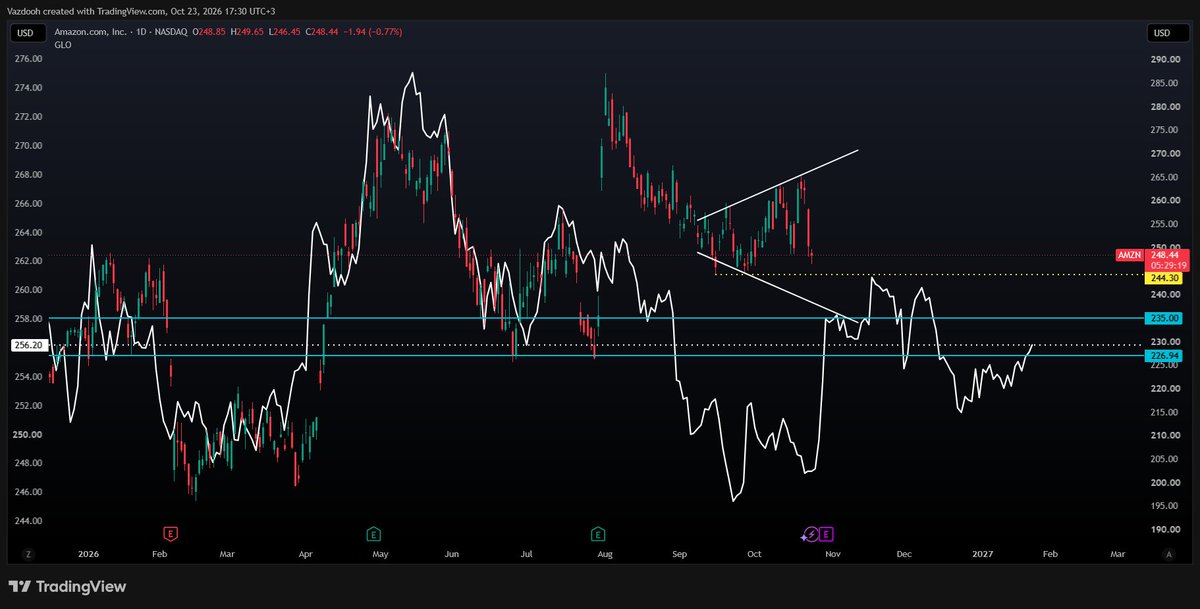
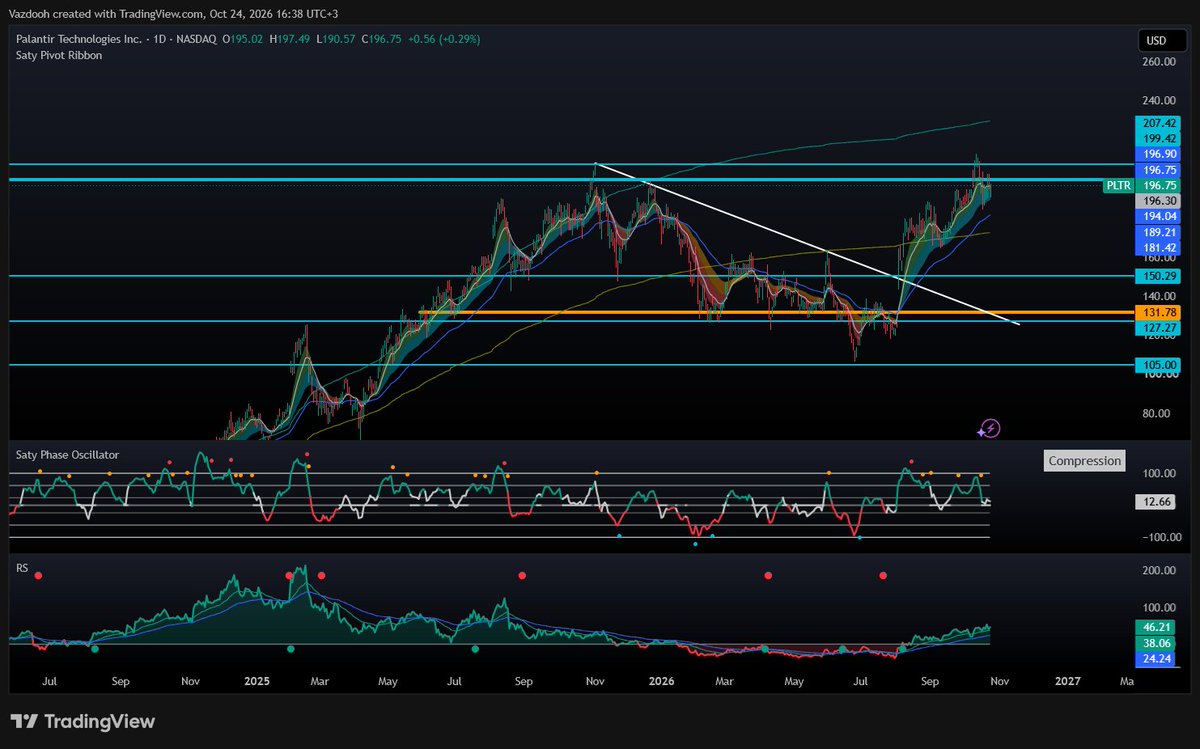
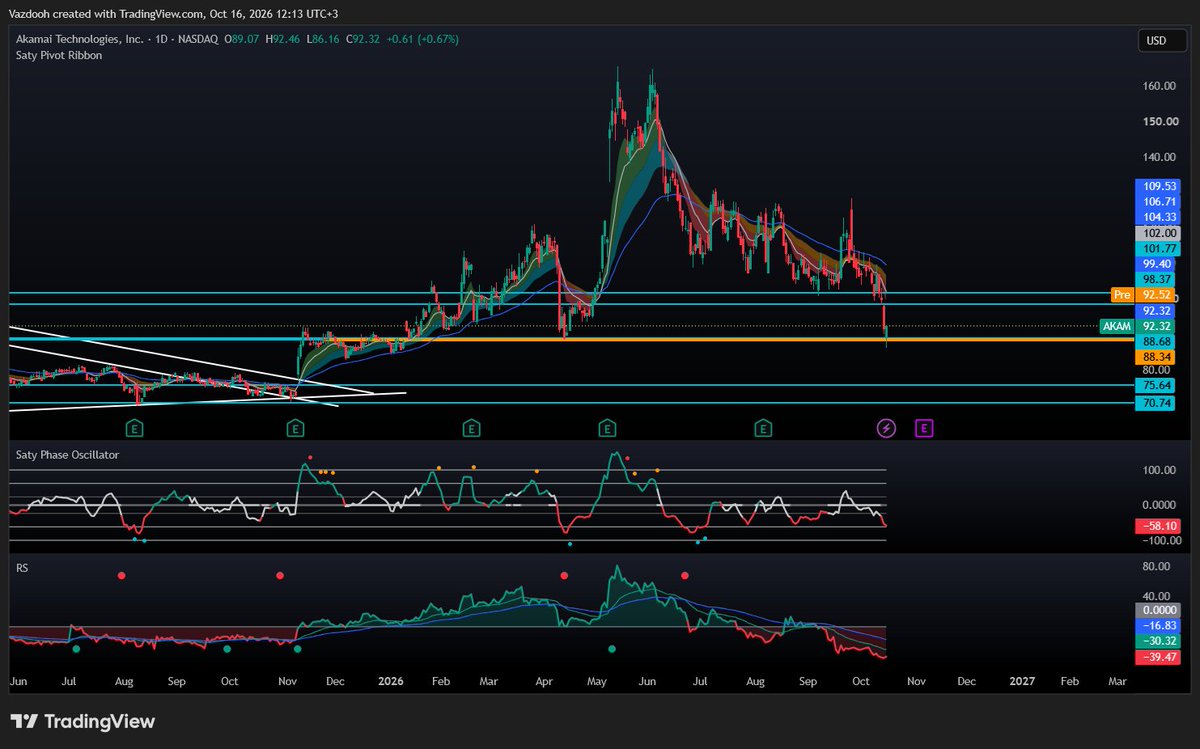
$MU & $AMZN
$GOOGL & $WDC as well since they have the best correlation
I don't know anymore. I am reluctant to call a bottom here even though we're at the projected liquidity low. Feels like we have more downside until either US elections pass or we get some sort of price capitulation at the index level.
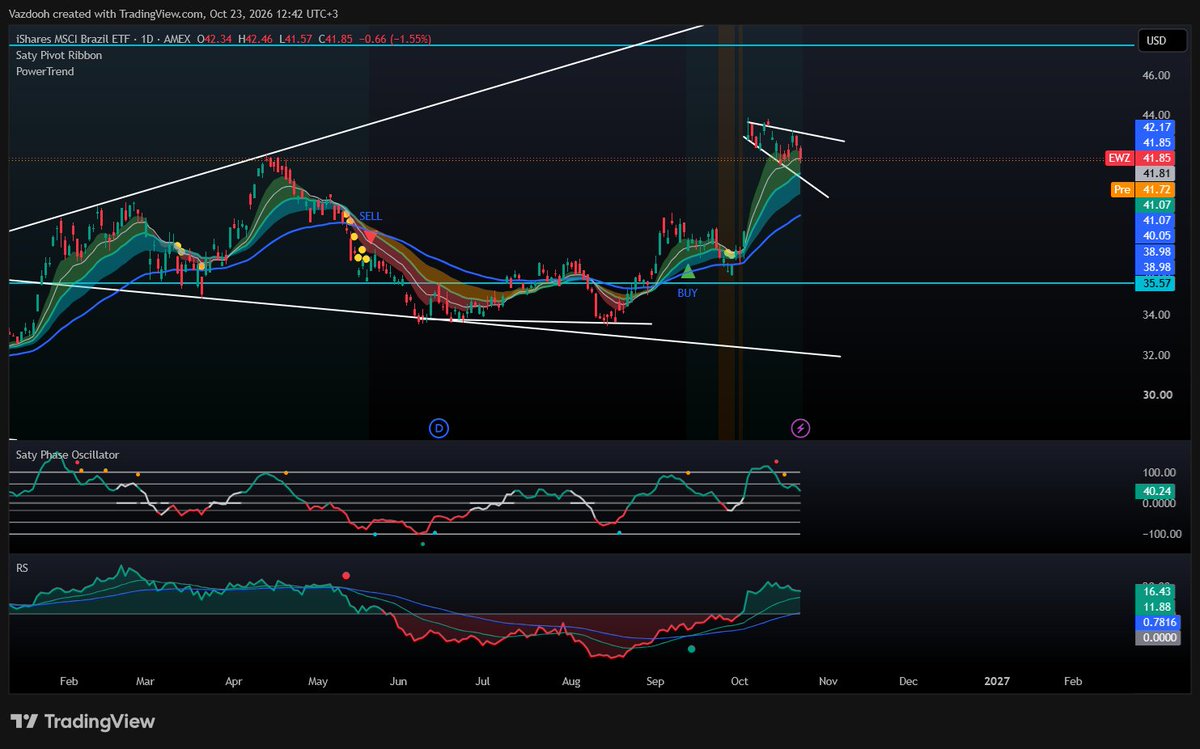
$EWZ I thought this was profit taking ahead of election weekend, but seems to be a roll up from 43C to 46 & 48C, with some sold 50C for credit. A smaller 46C 3/19 in there as well.
Whale is staying invested through elections from what it seems.
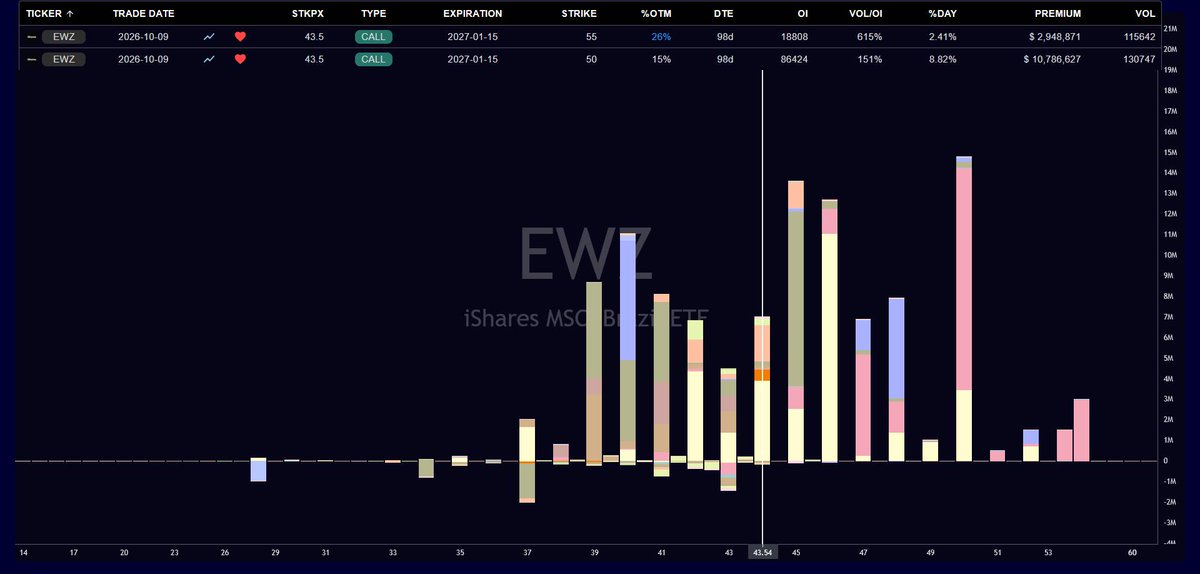
$EWZ still showing strength and getting activity.
50-55C spread for $10.7 - 2.9M. I think this goes to 47-50 before any meaningful pullback.
Since it's tied with the outcome of the Brazilian elections, the best time to take profits is right before the second round of the election, on Oct 23rd. The higher it goes before then, the higher the chance of a sell the news reaction regardless of who wins.
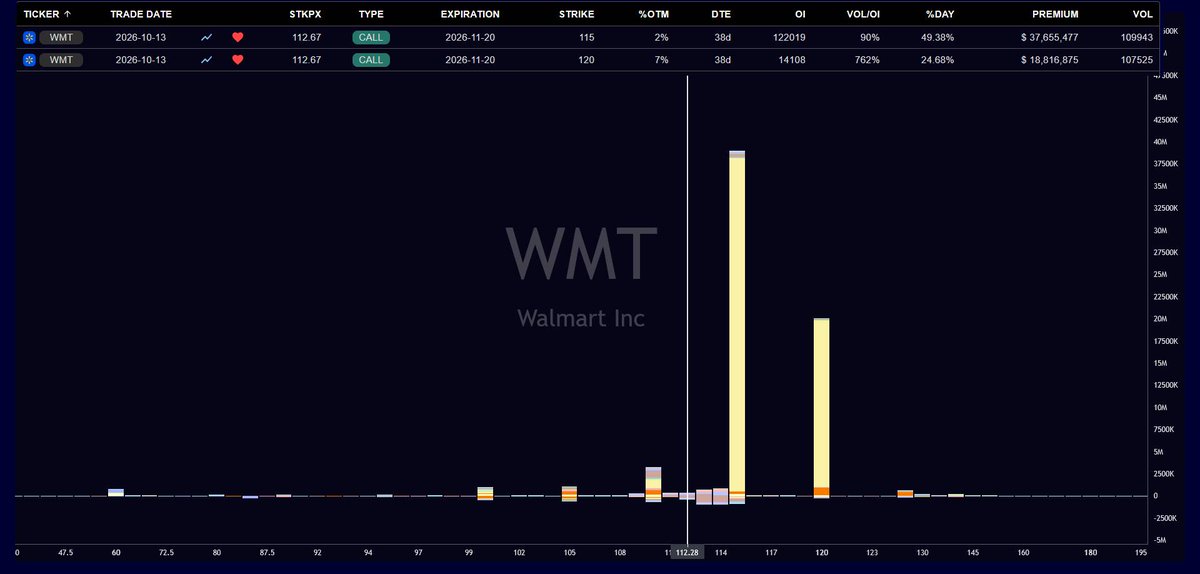
$WMT the 115C leg was rolled into 120C. 125C unchanged.
After digging around more into this one it gets a bit complicated. The original trade on Oct 6th was a darkpool print (for 1.9M shares and $202M premium), and that 115-125C spread for 11/20.
The darkpool print traded as a QCT (qualified contingent trade). Those are required by the SEC to be hedged. That means we have either short shares, hedged with the call spread, or the other way around. Both legs are delta matched to 1.9M shares.
This roll from 115 to 120, while leaving the 125C untouched, rebalances the delta of the spread. Because the stock rallied, the delta for the 115C increased, making the spread position lopsided relative to the share position. After rolling to 120, the delta of the spread (now 120-125) is back to 1.9M shares.
Taking this into account, this strongly suggest the 202M darkpool print was short stock, and it was hedged for upside with the call spread. This hedge will be in place until right after earnings (Nov 19th). Whoever put this trade on is bearish long term, but hedged any short term or earnings upside with a delta matched call spread.
$CNC whale almost fully out. ~10k contracts, $50M, left.
$OSCR one moving more slowly, but I think they entered when OI was already ~10k. Another ~10K contracts left for this one as well.
$CNC $OSCR
Whales slowly exiting deep ITM calls without rolling.
OSCR 10C went from ~55K OI to ~23K (after this one). CNC 25C went from ~61K OI to ~32K (also after this one). Underlying price going nowhere since they started exiting these at the end of June.
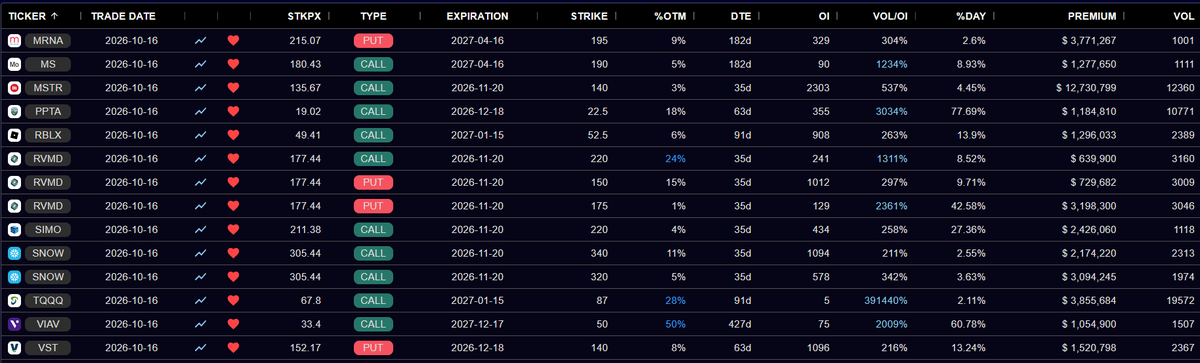
10/16 flow
$AAOI sold puts
$AFRM sold calls
$CART calls
$CRWD puts + sold calls
$CZR sold puts
$EWY puts + sold calls
$HOOD sold calls
$IEF sold calls
$MCO sold call spread
$MGM puts
$MNDY sold calls
$MOD sold calls
$MRNA puts
$MS sold calls
$MSTR sold calls 👀
$PPTA calls
$RBLX sold calls
$RVMD financed put spread
$SIMO sold calls
$SNOW calls 👀
$TQQQ calls
$VIAV sold calls
$VST puts 👀
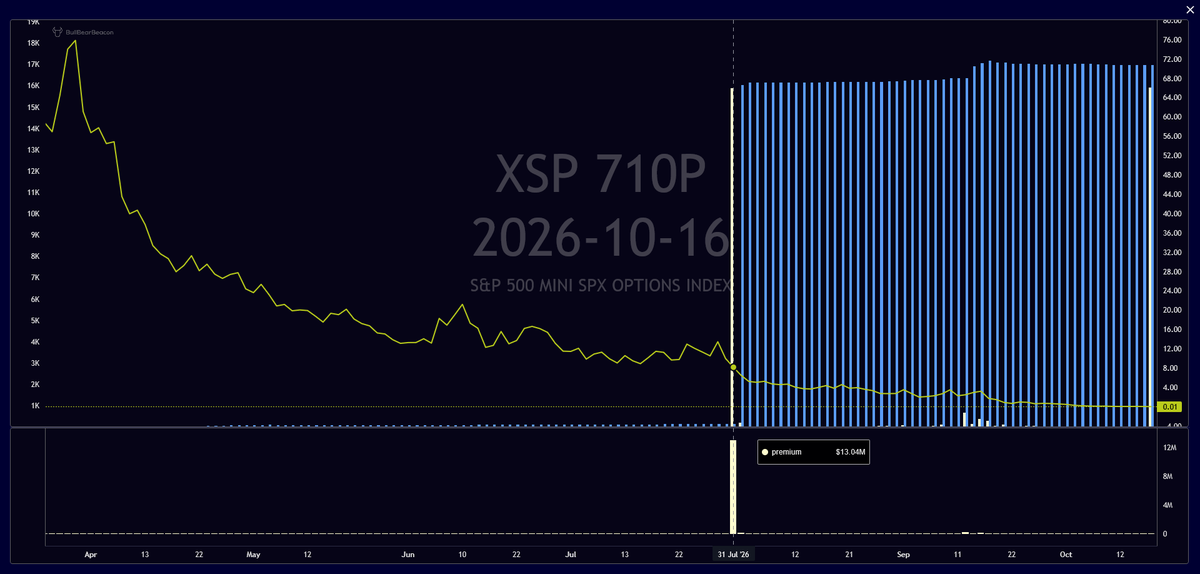
$XSP has a long running "program" of 10-15M short puts, that get rolled every 1-2 months.
On Friday two of those short puts positions were closed, but got rolled into long puts.
690P 10/16 short put $14.3M -> $7.7K
710P 10/16 short put $13M -> $15.9K
735P 1/15 for $20.6M bought