Anthropic saying they’re “profitable” on an adjusted basis basically means the core business of running Claude for customers is covering its day-to-day costs right now.
What they’re leaving out:
- The HUGE cost of training new models
-Stock-based compensation (employee equity)
-Some of the revenue share they pay partners like Amazon
So the part where people are actually using the product looks healthy and improving. The part where they’re still spending massive amounts to build the next models is excluded from that “profitable” number.
The full picture of what it costs to stay at the frontier. $SPY $QQQ $IWM $NVDA $SPCX
Anthropic Says Q3 Revenue Jumped To $16.8 Billion And Turned "Adjusted" Profitable... But Run-Rate Math Shows Growth Hitting The Brakes https://t.co/5V75RW6eaR
The standard is trust, then verify.
Funds have bought satellite shots of oil tank shadows to estimate crude supply and counted cars in Walmart lots to get ahead of earnings.
Great investigative work. Very entertaining. Dedication.
But irrelevant as a serious investor. It’s also creepy and maybe illegal.
Either you trust management or not. That’s it. Binary. All else noise.
No need to microanalyze any company you trust with literal thermal goggles.
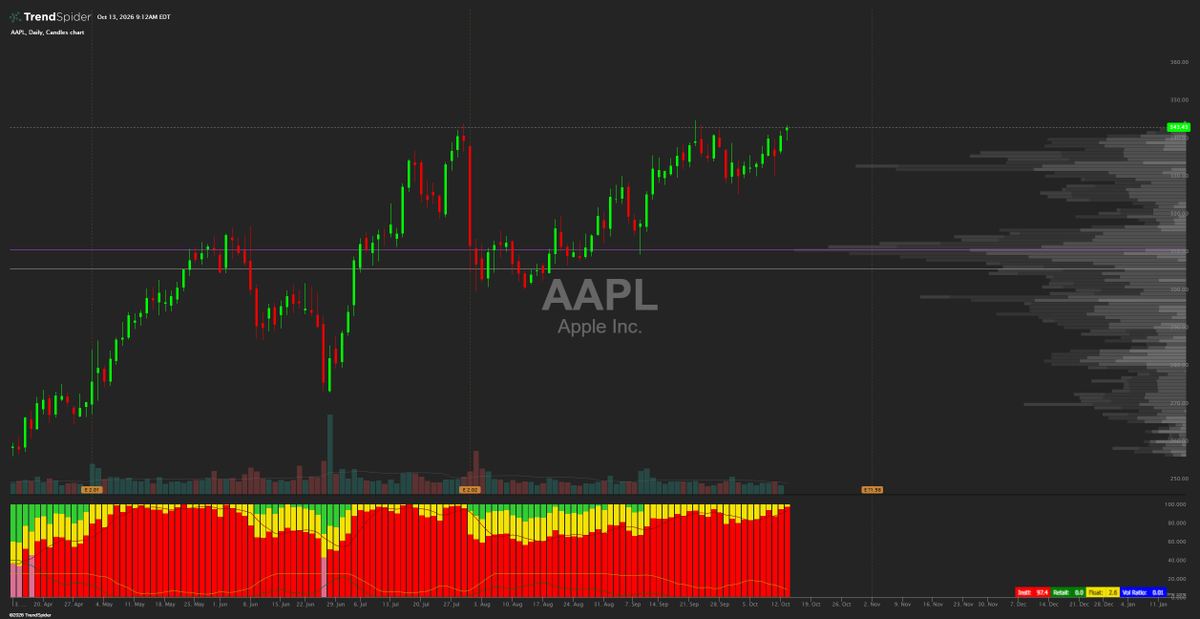
$AAPL news enough to break out of the Cup and Handle to the upside?
$AAPL has held up through this tech sell-off because it isn’t spending hundreds of billions on AI data centers. Today’s “Welcome Home” event adds a new home hub (HomeView), a new Apple TV, and HomePod mini 2, all running Siri AI.
Chart: Cup from the July high near $343 down to about $300 in August, back up to the rim in September, then a tight handle down to about $328. It’s pressing the rim again this morning. A cup this deep measures to roughly $385.
Confirmation is a close above $345. Invalidation is a close below $328.
APPLE $AAPL JUST INTRODUCED THE HOMEVIEW, A $299 SMART HOME DISPLAY
- 7-inch touch screen with an iPhone-style app grid
- No physical buttons, mainly runs on voice commands
- Built-in camera recognizes up to 6 people and personalizes Siri for each
- Available Nov. 13
Apple is also launching cameras, a video doorbell, thermostats, and door locks with LG and Schneider Electric, priced from $199 to $399 and shipping in December - Bloomberg
$UNIT
Uniti owns fiber networks and, since the Windstream merger, the Kinetic home fiber business.
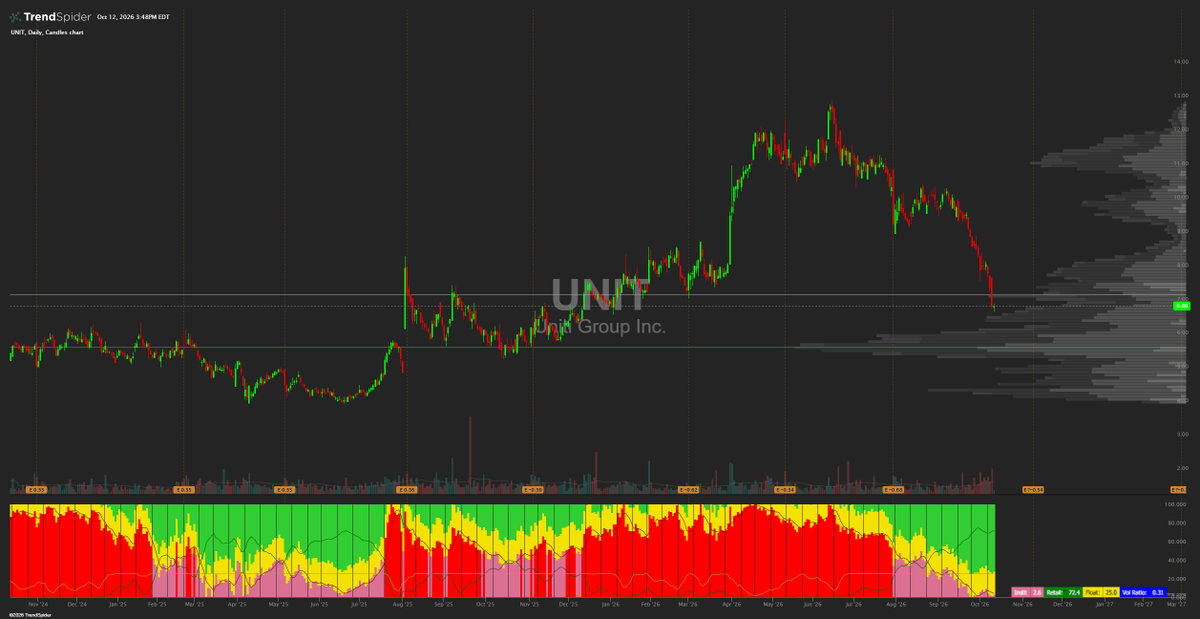
Chart: Down 46% from the June high near $12.80. The August low at $9 gave way in late September and the stock has fallen almost straight down to $6.87, giving back the whole 2026 rally. Next real support is the volume shelf around $5.50.
Fundamentals: Q2 revenue $910M and adjusted EBITDA $357M. Kinetic fiber revenue grew 19% with a record 38,000 subscriber adds. On the other side are $10.6B of debt, about 7x EBITDA, and $805M a year of interest. The whole company trades for about $1.7B.
Options: Someone bought $1M of May 2027 $9 calls today, 10,000 contracts at the ask, through the floor, into a strike that had 1 contract open. It pays off above $10 by May, which means a 46% move.
The fiber business is growing, and the stock is a thin slice of equity sitting on top of a lot of debt, which is why it fell this hard and why someone can bet $1M on it coming back.
Confirmation is a close back above $9. Invalidation is a close below $5.50.
$AVGO
Chart: Falling wedge from the June high near $495. Tagged the top line around $378 this week and got rejected. Sitting at $362 in the middle of the wedge, with the September low around $335 as the floor.
Fundamentals: Last quarter revenue was $29.6B, up 86%. AI chip revenue was $16.7B, up 221%, and is guided to $21.7B this quarter. The catch is gross margin, which slipped to 75% and is guided to 73% as custom AI chips (heavier on memory) become more of the mix.
The AI business is growing faster than almost anything in large-cap tech, and the stock is down about 27% from the high.
Confirmation is a close above $378. Invalidation is a close below $330.
Nice. The Robert brother have been great leaders for $IREN.
I'm not a fan of buying or selling a stock strictly based on TA. I've seen too many failed bullish or bearish pattern go the other way.
Between fundamentals, TA, option data, and the macro, it's like a grown man's game of Tetris putting the pieces together.
I like the IREN/SMH chart. Good luck with your investments.
Adding $25 1/21/2028 $IREN Calls at $21.85 and $IRE shares at $8.54
Citadel just bought yesterday. We are seeing the start of the quarter shenanigans. I will be taking advantage of these prices.
$IREN: Is it time to approach new highs?
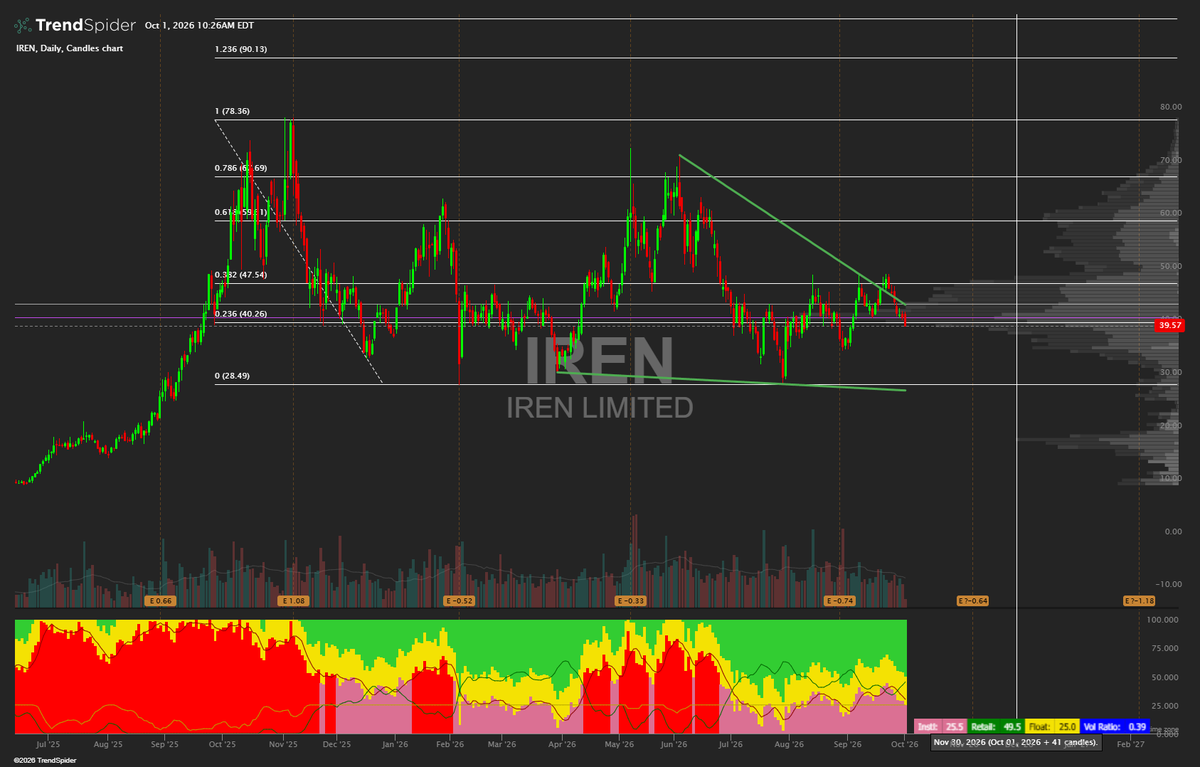
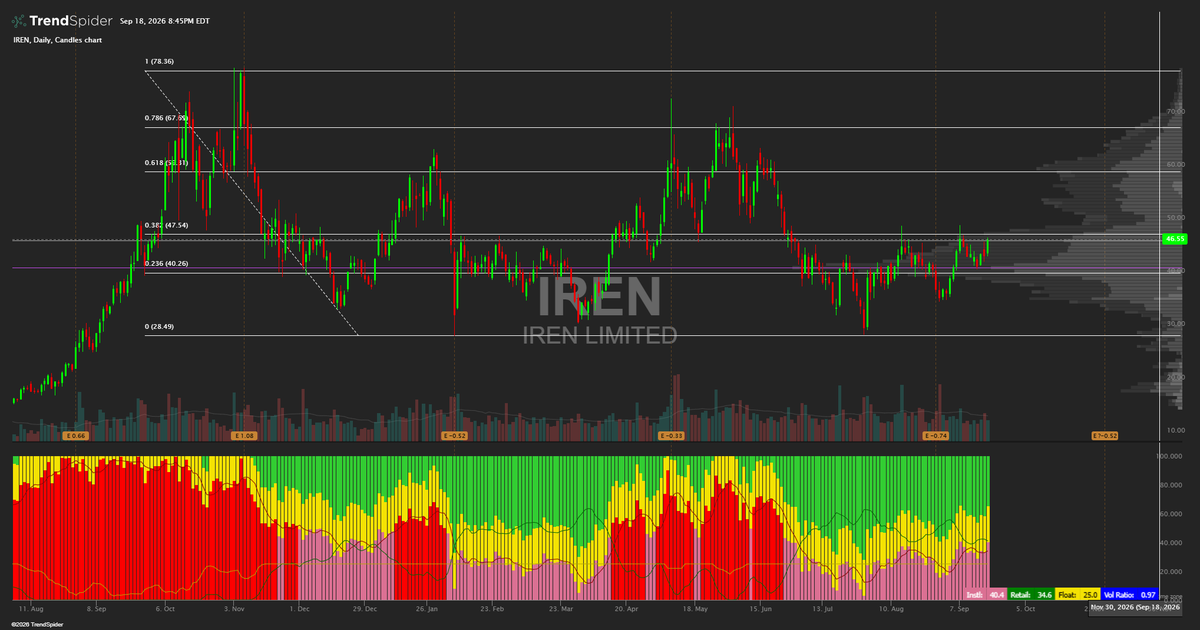
Rejected at $49 twice in five weeks, Aug 13 and Sep 8. Price at $46.55, up 61% from the July low of $28.93 and still 41% below the November high.
FY26 revenue $707M. AI Cloud went from $16.4M to $128.8M in one year. Operating run-rate is $1.0B as of late August, with 2026 capacity largely sold out and new contracts signed above $20M per megawatt.
The AI business is real and compounding, and the balance sheet is now $7.6B of debt against $7.6B of cash, mostly convertible notes.
$IREN triple tap of resistance at the .382 fib. Above $49.29, the range breaks and $59 is next.
BREAKING: US August PCE inflation, the Fed's preferred inflation metric, falls to 3.4%, below expectations of 3.7%.
Core PCE inflation fell to 3.0%, below expectations of 3.3%.
July headline and core PCE inflation were also revised down by 30 basis points each.
October rate hike odds are falling again.
$BKKT
Bakkt is a crypto trading and stablecoin payments platform, rebuilt this year after CEO Akshay Naheta sold his company DTR, into it for stock. $365M market cap.
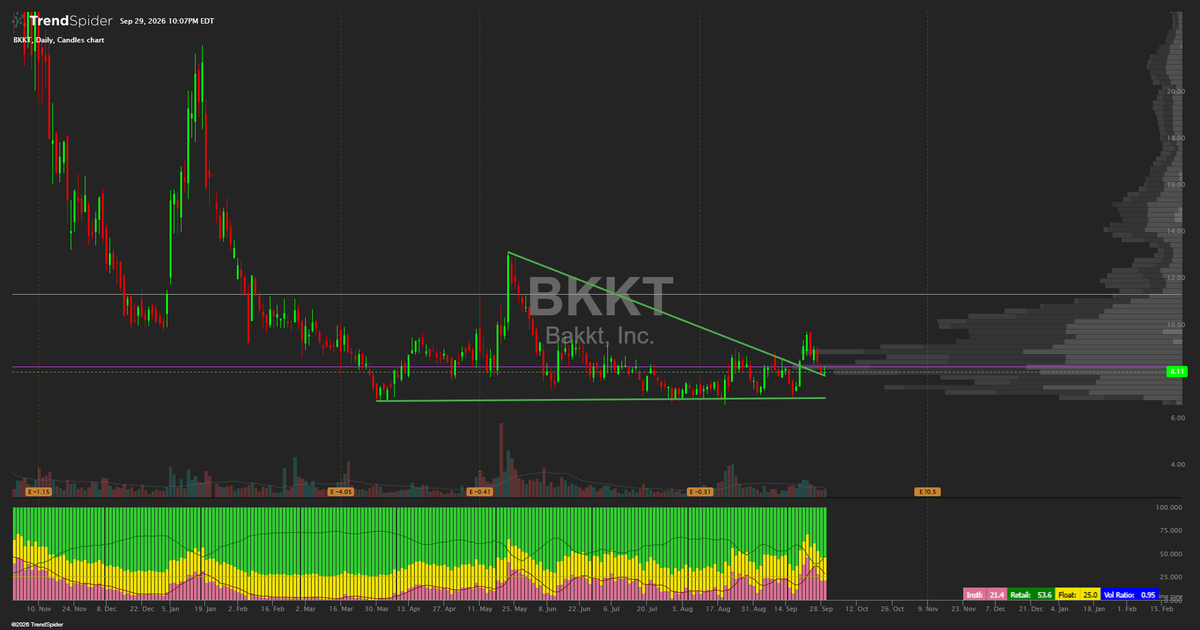
Chart: Descending triangle since May. Lower highs at $13.04, $9.77, and $8.95 over a floor near $6.75 that has held three times since March. Last week's crypto rally popped it 36% to $9.79, the exact level that stopped it in June, and it gave all of it back. Now sitting on the triangle's top line at $8.09.
Fundamentals: Q2 revenue $170M, but $168M of that is crypto pass-through. What is left is about $2M against $21M of operating cost. Adjusted EBITDA loss $12M a quarter, cash $51M, about four quarters at that rate. The reported $81M profit is a paper mark on warrants in an Indian shell company bought in June for $9M. Volume target for 2026 was raised to $3B on Sep 9, with $410M done in the first half.
Insiders: Director Michael Alfred bought 1.16M shares through his fund for $9.1M between May and August, average $7.86, last buy at $7.12. CEO owns 20%.
Options: Too thin to matter. About $38K of Oct $9 calls bought on the Sep 18 pop, nothing since.
Confirmation is a close above $9.79. Invalidation is a close below $6.75.