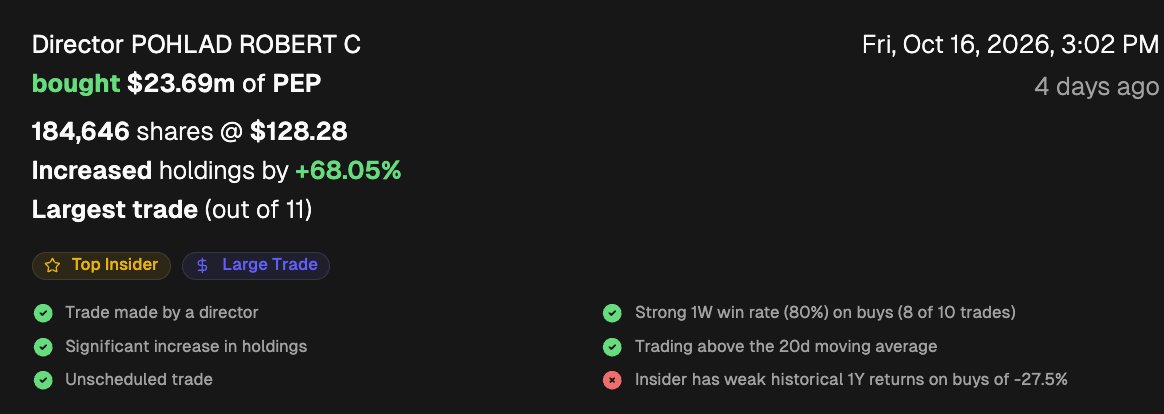
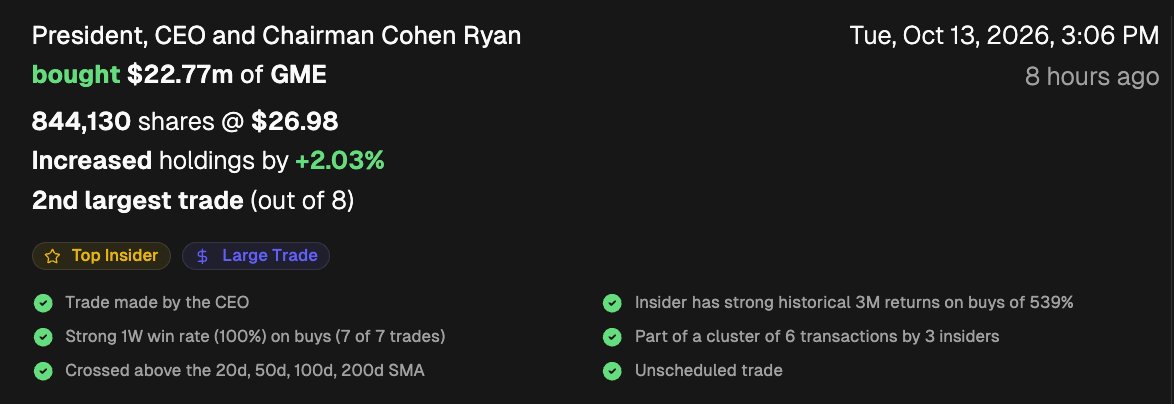
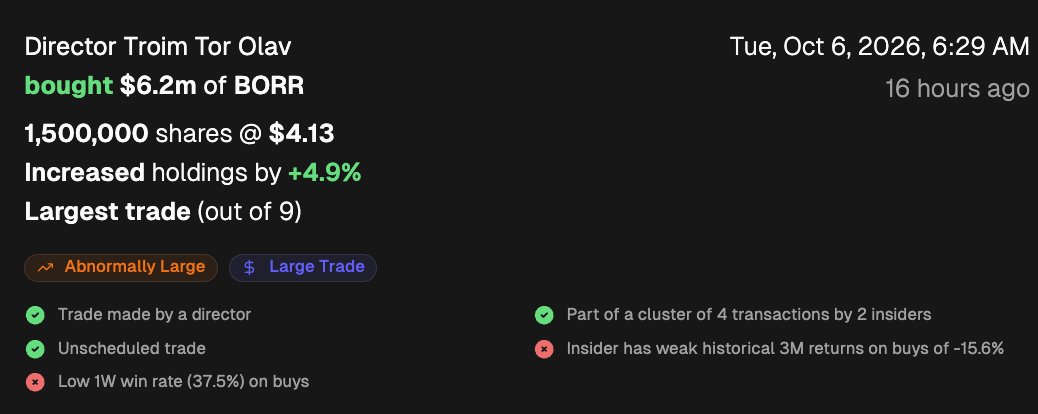
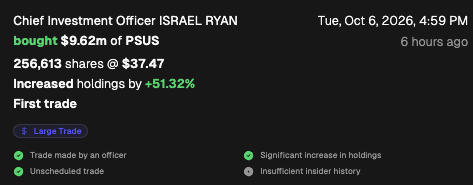
Aurelion Research (@AurelionRsch) is one of the best new research teams sharing stock ideas.
They gave me access to their paid research to see what I could find.
Here are some of their best pitches (and a couple of their newest ones):
10% Owner (Rusnak Paul P.) at SONIC AUTOMOTIVE INC $SAH purchased $1.66M (3rd largest purchase, out of 5).
Dip Buy: the stock was down -24% in the previous month.
This insider has purchased the stock 2 times in the last 30 days.
US breadth has deteriorated quickly (from 70% of stocks above 200d in August to 40% now).
I used YB API to pull US pitches from the last 6m from authors with 20%+ 6m returns, kept those within 10% of 52wk low, and had Astra rank them.
Here are some of the most interesting:
$KRMN - defense/space supplier. $4.5b mkt cap / $5.3b EV. 21x EBITDA (v peers at high teens). 30% EBITDA growth (v peers in low teens). De-rated 70% from highs. Worse-than-expected FCF (mgmt blames growth). Director bought $1m. Sector de-rated. Recently written up by @CEOStockWatcher@BlackScholesMan@invest091
$SARO - engine aftermarket services. $6.9b mkt cap / $9.3b EV. 9.5x EBITDA (13% FY27E growth). Down 36% from highs. Mgmt raised FY rev and EBITDA guidance and reiterated $1b of LEAP rev by 2030 (from $400m). LEAP became profitable in Q2. Expanded OEM to add $25m annual EBITDA. Recently pitched by Pender US Small/Mid Cap and Middle Coast Investing
$APP - mobile ad-tech. $94b mkt cap, $94b EV. 12x EBITDA (v 22x 3y median). 26% FY27E EBITDA growth (v 29% median), but mgmt expects 30% for next few years. Down 60% from highs. Expanding into e-commerce. Repurchased $1.5b in H1. Written up by @Uzocapital@HatedMoats@WisemanCap
$NOC - aerospace/defense. $68b mkt cap / $83b EV. 13x EBITDA (v 15x 3y median). 7.5% FY27E EBITDA growth. Down 36% from high. Record backlog (+17%), raised EPS guidance (FCF only reaffirmed), 1.8x book-to-bill. Sector de-rated.
$PCG - california electric/gas utility. $27b mkt cap, $93b EV. 7.7x EBITDA (v 9x 3y median). 10% FY27E EBITDA growth, mgmt guides 9% EPS growth. 35% below highs. Wildfire reform/strategic review could lower funding costs and narrow valuation discount. Recently pitched on VIC.
$LODE - solar panel recycler with data center land kicker. $171.0m mkt cap / $162.3m EV. Down 50% from high. Recycling plant is operational (guided to breakeven by year-end). Sold mining asset for $45m ($25m cash upfront). Mgmt pegs land value at $300m, targeting sale by mid-2027. Multiple insiders buying. Written up by @Uzocapital@CEOStockWatcher@whirlybard@Aksel465@AlmostMongolian@BetterIRR@Miroslavtepnek1
$MOB - drone communications + security software. $54m mkt cap, $40m EV. 5x EV/sales. FY27E 150% rev growth. Negative EBITDA. Down 53% from highs. $2.2m follow-on orders tied to U.S. military drone program; deliveries now monthly. Adding higher-margin recurring cybersecurity licenses. Recently pitched on VIC.
$MIAX - US options exchange. $3.3b mkt cap / $2.6b EV. 9.5x EBITDA (below peers). 13% FY27E EBITDA growth. Increased options trading + higher access fees driving growth. Bloomberg-index futures add upside. Written up by @Miroslavtepnek1@capytalmgmt@Petty__Cash@DavidBarbato_@MoodyWriter13@ragingbullcap