CA Student,but in my left brain nothin is right & in my right nothin is left! Love Foot ball and Food bowl. I'm so poor that I can't pay attention to anybody!!
BIG UPDATE FOR TAX PROFESSIONALS!
A major change in the Income-tax Act, 2025 deserves your attention.
Under Section 195, tax on income referred to in Sections 102 to 106 has been revised, with the highlighted provisions showing significant changes in the applicable tax rates.
📌 Key takeaway:
• 75% in specified cases
• 99% where income is determined by the Assessing Officer in the specified circumstances
• 30% tax rate for income referred to in the relevant clauses
These changes are extremely important for tax professionals, practitioners and taxpayers preparing for the transition to the new Income-tax Act.
Save this update & share it with every CA/Tax Professional!
Follow the Tax Talk with CA Nitin Chawla A.C.C.A channel on WhatsApp: 👇 https://t.co/7KtKmuv6rW
#IncomeTax #IncomeTaxAct2025 #TaxUpdate #IncomeTax2025 #DirectTax #Taxation #CAFinal #ICAI #CharteredAccountant #TaxProfessionals #IncomeTaxIndia #Finance #TaxNews #TaxUpdates
Important GST Judicial Update
The Hon’ble Punjab & Haryana High Court, in Luxmi Traders v. Union Territory of Chandigarh, has held that mere uploading of a Show Cause Notice (SCN) or Order-in-Original under the “View Additional Notices and Orders” tab on the GST portal does not constitute valid service, where the SCN/order has not otherwise been duly communicated and has neither been acknowledged nor acted upon by the taxpayer. The Court accordingly directed restoration of ex parte proceedings and appeals dismissed on limitation, subject to the circumstances laid down in the judgment.
@theicai@cbic_india@FCAUmeshSharma@rajendrakumarRK@nacincbic@Infosys_GSTN@GST_Council@GSTATofficial
कलकत्ता हाई कोर्ट ने एक महत्वपूर्ण फैसले में स्पष्ट किया है कि किसी व्यक्ति के खिलाफ आपराधिक मामला लंबित होने मात्र से उसे पासपोर्ट पाने या उसका नवीनीकरण कराने के अधिकार से वंचित नहीं किया जा सकता।
न्यायमूर्ति कृष्ण राव ने बुधवार को कहा कि पासपोर्ट भी अन्य सरकारी दस्तावेजों की तरह एक नागरिक दस्तावेज है। केवल यह मान लेना कि पासपोर्ट बनते ही व्यक्ति विदेश भाग जाएगा, कानून की सही व्याख्या नहीं हो सकती। पासपोर्ट बनवाना और विदेश यात्रा करना दोनों बिल्कुल अलग विषय हैं।
विदेश जाने की अनुमति देना या रोकना न्यायालय के अधिकार क्षेत्र का विषय हो सकता है, लेकिन पासपोर्ट की वैधता तय करना पूरी तरह पासपोर्ट प्राधिकरण की प्रशासनिक जिम्मेदारी है। किसी कानून की ऐसी व्याख्या नहीं की जा सकती, जिससे नागरिकों के अधिकार अनावश्यक रूप से सीमित हों या अदालतों पर अतिरिक्त बोझ पड़े।
यह पूरा मामला अमित कुमार अग्रवाल नामक एक व्यक्ति से जुड़ा है, जिन पर प्रिवेंशन आफ मनी लॉन्ड्रिंग एक्ट (पीएमएलए) के तहत झारखंड के रांची की विशेष अदालत में दो मामले लंबित हैं।
इन मामलों के चलते उनके पासपोर्ट की मियाद पूरी होने के बाद जब उन्होंने नवीनीकरण (रिन्यूअल) के लिए आवेदन किया, तो निचली अदालत ने कुछ शर्तों के साथ अनुमति तो दी, लेकिन पासपोर्ट प्राधिकारी ने यह तर्क देते हुए केवल एक साल का पासपोर्ट देने की जिद पकड़ी कि अदालत ने अवधि स्पष्ट नहीं की है।
इसके खिलाफ अमित कुमार अग्रवाल ने कलकत्ता हाई कोर्ट का दरवाजा खटखटाया था। उनका तर्क था कि बालिगों के लिए सामान्य नियमों के तहत 10 साल का पासपोर्ट मिलना चाहिए, न कि सिर्फ एक साल का।
विदेश मंत्रालय की ओर से 1993 की एक अधिसूचना का हवाला देते हुए यह दलील दी गई थी कि यदि अदालत अवधि का जिक्र न करे, तो एक साल का पासपोर्ट देने का नियम है। हालांकि, हाई कोर्ट ने इस दलील को सिरे से खारिज कर दिया। अदालत ने कहा कि किसी भी कानून की व्याख्या इस तरह नहीं की जानी चाहिए जिससे नागरिकों के अधिकारों का अनावश्यक हनन हो या अदालतों पर प्रशासनिक बोझ बढ़े।
हाई कोर्ट ने स्पष्ट किया कि यदि किसी आरोपित के पासपोर्ट की अवधि 10 साल के लिए बढ़ाई जाती है, तो इससे चल रही जांच या न्यायिक प्रक्रिया में कोई बाधा उत्पन्न नहीं होगी। इससे हर साल रिन्यूअल के लिए अदालतों के चक्कर काटने की झंझट से राहत मिलेगी।
अदालत ने यह भी साफ कर दिया कि पासपोर्ट की अवधि 10 साल की होगी, लेकिन इसका मतलब यह नहीं है कि आरोपित बिना अनुमति विदेश जा सकेगा।
विदेश यात्रा करने के लिए उसे संबंधित विशेष अदालत से पूर्व अनुमति लेनी होगी और निचली अदालत की सभी शर्तें ज्यों की त्यों लागू रहेंगी। अदालत ने पासपोर्ट प्राधिकरण को निर्देश दिया है कि वह आगामी तीन सप्ताह के भीतर आवेदक का पासपोर्ट पूरे 10 साल की अवधि के लिए नवीनीकृत (रिन्यू) करे।
#CalcuttaHighCourt #HighCourt #Passport #DainikJagran
🚨 Tax Audit Season is Here!
Still confused about Tax Audit applicability under Section 44AB and Presumptive Scheme applicability under Sections 44AD, 44ADA & 44AE?
This slides cover everything you need to know for AY 2026-27:
✔ Specific provisons for Business + Professionals + Transporters
✔ Get clarity for all possible combinations of Turnover limits for Audit & Presumptive -> Everything explained in just 4 slides.
✔ Opting in & opting out provisions for 44AD
━━━━━━━━━━━━━━━━━━━━
📘 Want a complete ready referencer for the entire Audit & ITR season for your team? having 35 INCOME TAX Topics all packed in 163 pages (updated with Amendments of Finance Act 2026
Get the Income Tax Ready Referencer (ITRR) – 5th Edition (E-Book). Here is Link for subscription & start reading instantly (₹175) https://t.co/HUBDGbxhJ4
CA HARSHIL SHETH
PS- Printed edition is out of stock.
Assessee's ITC for FY 2018–19 was denied for delayed return filing, but the Kerala High Court held that the benefit of Section 16(5) must be considered and remanded the matter for allowing ITC, if otherwise eligible.
Issue:
Whether the Department was justified in denying Input Tax Credit (ITC) under Section 16(4) of the CGST Act for delayed filing of returns, despite the subsequent relaxation provided under Section 16(5).
Rule:
Section 16(5) of the CGST Act permits availment of ITC where the prescribed returns are furnished within the extended statutory cut-off date. An Assessee satisfying this condition is entitled to have the claim examined on merits, subject to fulfilment of the other statutory requirements.
Application:
The Assessee was issued an order under Section 73 denying ITC for the period April 2018 to March 2019 on the ground that the returns were not filed within the time prescribed under Section 16(4). The Court found that the relevant returns had been filed within the extended timeline recognised under Section 16(5). Consequently, the denial of ITC solely on the basis of Section 16(4), without considering the benefit of Section 16(5), was held to be unsustainable.
Conclusion:
The High Court set aside the impugned order and remitted the matter to the Department for fresh consideration, directing that the benefit of Section 16(5) be extended to the Assessee, subject to satisfaction of the other eligibility conditions for ITC.
Impact Analysis:
This judgment reiterates that the statutory relaxation under Section 16(5) must be given full effect, and ITC cannot be denied merely on the basis of Section 16(4) where the Assessee has complied with the extended time limit prescribed by law. It strengthens the principle that beneficial legislative amendments should be applied while deciding pending ITC disputes.
Title: OYSTER AUTO BODY vs. STATE TAX OFFICER
Court: THE HIGH COURT OF KERALA
Citation: WP(C) NO. 18712 OF
Dated: 02-06-2026
Provision: Under Section 16(4), 16(5), 73
IF YOU DIED TOMORROW🚨,
YOUR FAMILY WOULDN'T BE ABLE TO ACCESS A SINGLE THING YOU OWN DIGITALLY.
BANK ACCOUNTS. PASSWORDS. CLOUD STORAGE. ALL OF IT PERMANENTLY LOCKED AWAY.
HERE'S HOW TO FIX IT IN 30 MINUTES:
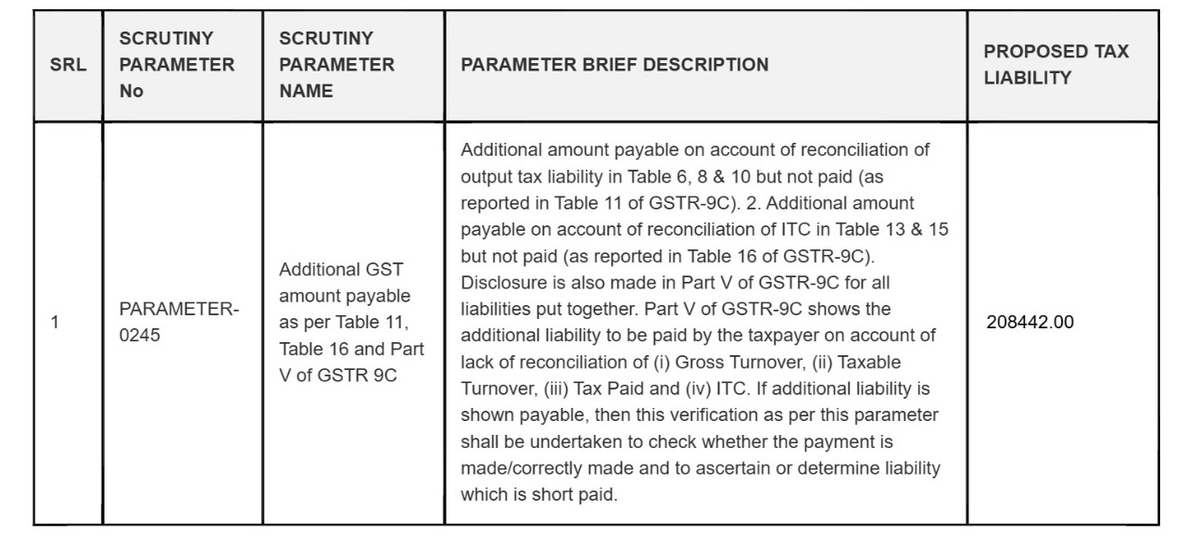
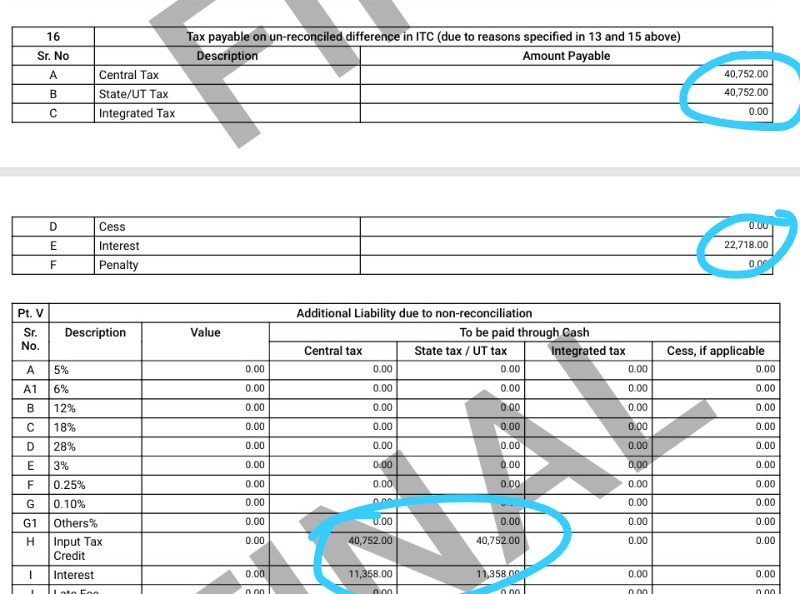
System generated notice...
Officer issues ASMT-10 by adding..
GSTR-9C Table 16 and Part V- counting the same ITC reversal twice.
The taxpayer had already paid the tax with interest through DRC-03 and had disclosed it in GSTR-9C itself.
Was the DRC-03 checked before issuing the notice?
Apparently not.
No application of mind.
No cross-verification.
Just a system-generated parameter converted into a readymade notice.
And now the taxpayer has to file a reply and re submit evidence that is already available on record.
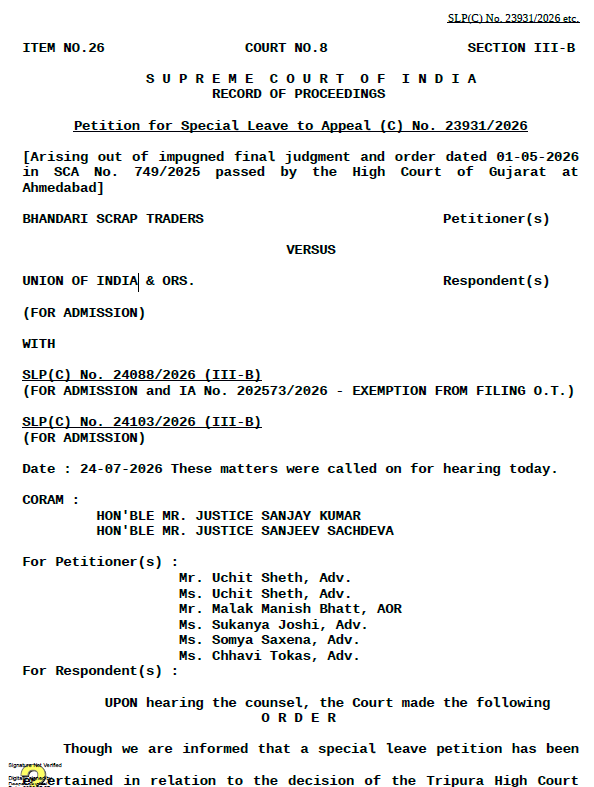
The Supreme Court upheld Section 16(2)(c) of the CGST Act as valid. Petitioners argued buyers should not lose Input Tax Credit over a supplier's default, citing a Tripura High Court ruling favouring purchasers.
The Court rejected this comparison, holding that the CGST Act and Delhi VAT Act follow different ITC schemes. It further noted that Sections 41, 73 and 74 already protect buyers, allowing them to reclaim reversed credit once the supplier pays the tax. The petitions were accordingly dismissed.
[Section 16(2)(c) of the CGST Act requires that tax charged on a purchase must actually be paid to the government by the supplier before the buyer can claim Input Tax Credit on it.]
Impact: Buyers must now verify supplier compliance carefully, since Section 16(2)(c) remains fully enforceable and ITC can be denied for a supplier's default.
Bhandari Scrap Traders vs Union of India & Ors. (SLP(C) No. 23931/2026)
💥 TDS UPDATE | New TRACES Portal
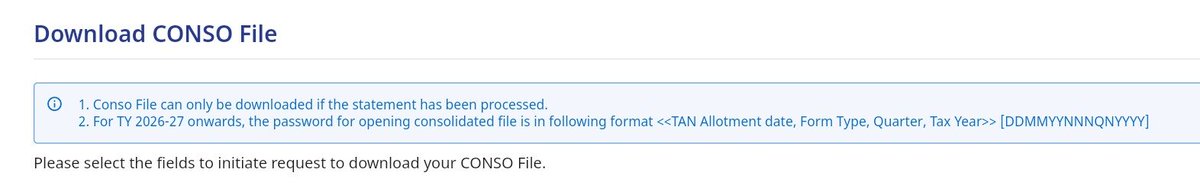
The password for the Conso File downloaded from the new TRACES portal will be:
TAN Allotment Date + Form Type + Quarter + Tax Year
Format:
DDMMYYNNNQNYYYY
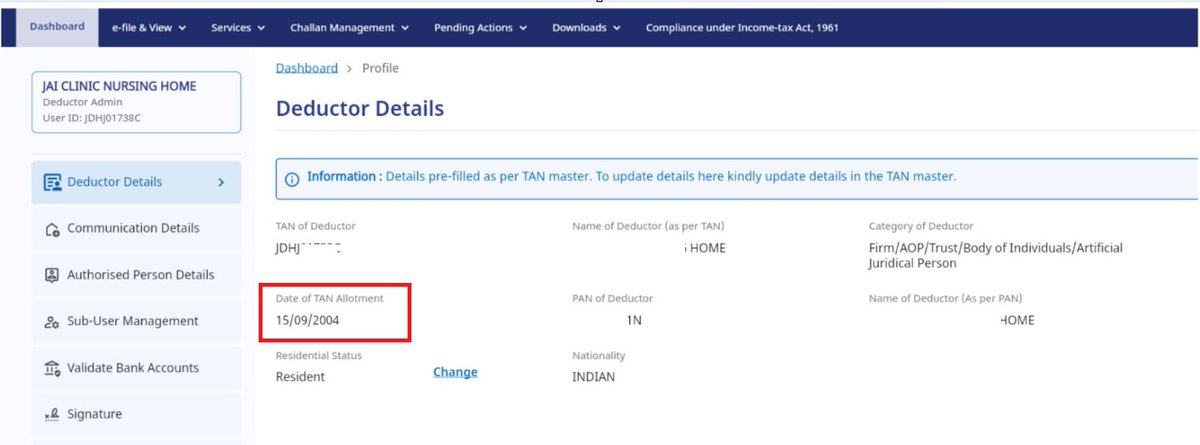
The TAN allotment date is available under Profile on the dashboard - PIC 👇
Example: TAN allotment date 15/09/2004
📌 Password: 15090414OQ12026
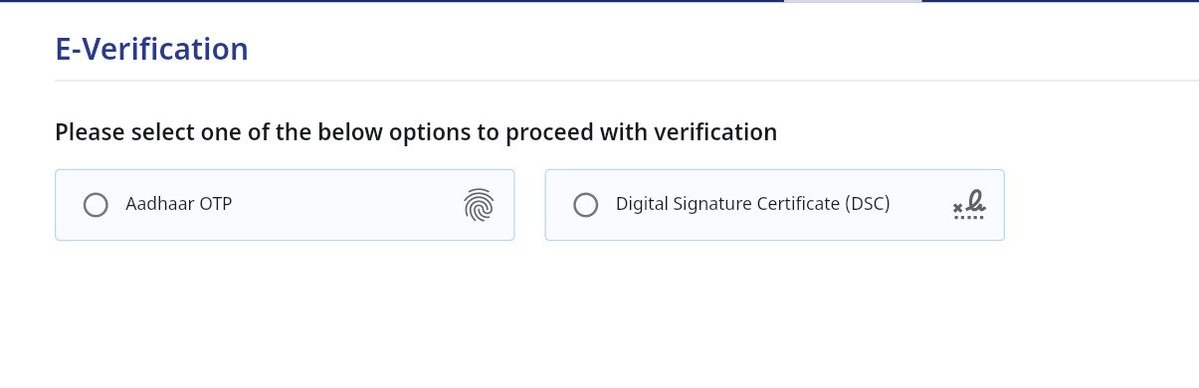
Further, E-VERIFICATION through Aadhaar OTP or DSC is now mandatory for downloading the Conso File.
We have moved to the new portal but the complication related to Traces procedure still remains/increased!!
Thanks @hirenbhandari_ for the help 👍
💥💥🔴 SC affirms constitutional validity of Section 16(2)(c) – No ITC to the recipient unless the supplier deposit taxes
📌📌 The Hon’ble Supreme Court in Bhandari Scrap Traders v. Union of India & Ors. [SLP (C) No. 23931 of 2026 dated July 24, 2026] dismissed the Special Leave Petitions filed relying on the judgment of the Hon’ble Gujarat High Court in Maruti Enterprise v. Union of India & Ors. [R/Special Civil Application No. 18080 of 2023 and allied matters including R/Special Civil Application No. 749 of 2025 dated May 01, 2026], thereby affirming that Section 16(2)(c) of the Central Goods and Services Tax Act, 2017 (“the CGST Act”) is neither unconstitutional nor liable to be read down, and holding that Input Tax Credit (“ITC”) is not available to the recipient unless the tax charged in respect of the supply has actually been paid to the Government by the supplier.
Read Our GST Newsletter at: https://t.co/uvZmOX0MaX
Científicos japoneses acaban de descubrir una noticia sorprendente sobre las canas.
Es, literalmente, la forma en que tu cuerpo elige la supervivencia en lugar del cáncer.
Aquí tienes todo lo que necesitas saber (y cómo mantener tu cabello oscuro):
Do u know that from this year i.e. AY 2026-27 onwards, we need to report "Receipts which are not in the nature of income" but received by the Assessee during the year.
Wake up, lawyers, Genzee, and citizens: Reforms in judiciary are a crying need.
1.Reforms in Judiciary are far more difficult than Reforms in the Government. The Supreme Court and the Bar Council of India, as if working in tandem, seek to suppress dissent and criticism by imposing sweeping restrictions on advocates and social media from criticising the judges. While the court has banned circulation of video clips of court proceedings, the Bar Council has gone even further. It has even made it mandatory for law graduates seeking enrollment to give an undertaking that they will not make videos or circulate court proceedings critical of judges and even lawyers on social media.
2.What is even stranger and more dangerous is that here, those who support and oppose the Government are united. The Bar Council Circular is considered to be the handiwork of Manan Kumar Mishra (BJP). What is even more shocking is that it is Vikas Singh (Anti BJP) who brought up the so-called PILs and got circulation of video clips of court proceedings banned.
3.But there is no reason for despondency. The Genzee movement has brought a new era of hope. An unjust and oppressive law ought to be opposed. The right to rebellion against oppression and tyranny is a fundamental right, said Justice K.K. Mathew, a saint jurist the nation has forgotten. Buddha, Martin Luther King, Krishna Iyer, Christ, and Gandhi teach us to disobey unjust and oppressive laws. Christ violated the Sabbath and set an example for humanity.
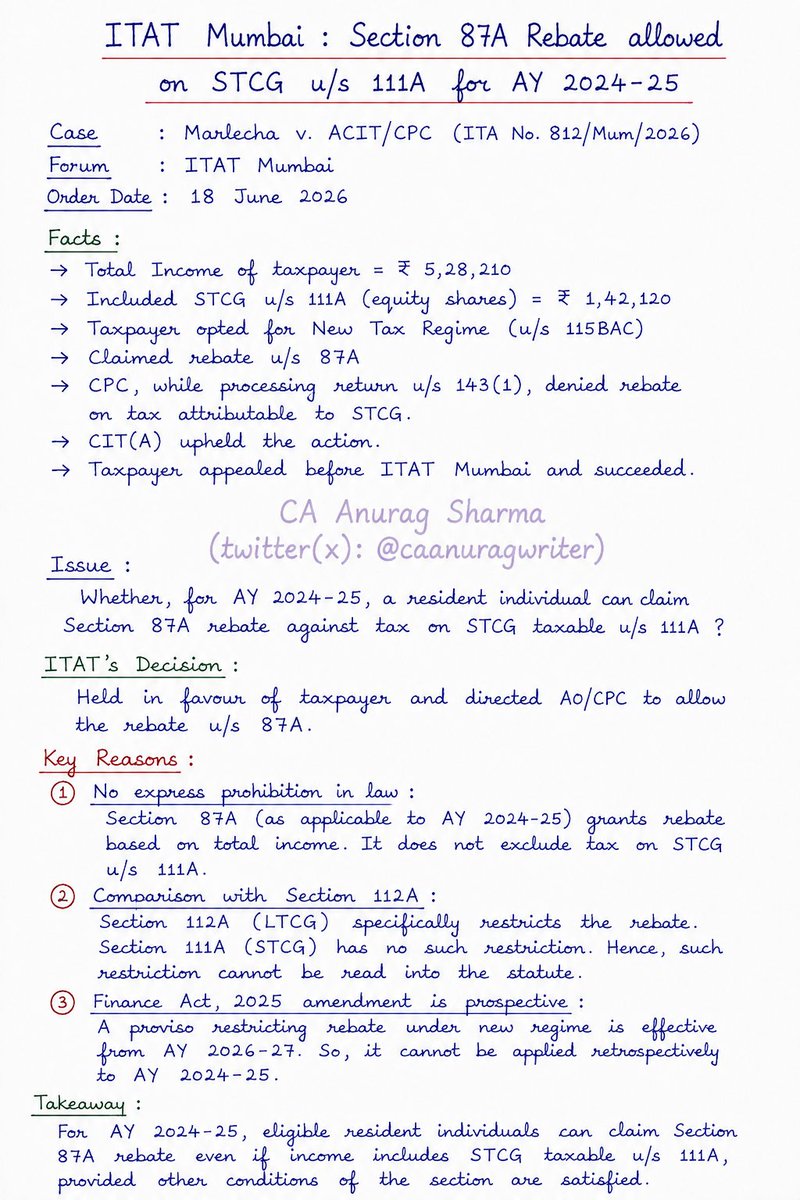
ITAT Mumbai Ruling | Section 87A & STCG (AY 2024-25)
ITAT Mumbai has held that eligible resident individuals can claim the Section 87A rebate even against tax on STCG u/s 111A for AY 2024-25, as no such restriction existed in law then. The Finance Act, 2025 amendment is prospective (from AY 2026-27) and cannot be applied retrospectively.
#IncomeTax #Section87A #ITAT #TaxUpdates #CapitalGains