$BRUN backed by $2.7 billion in total contract value, the company is set to reach $195 million in ARR by the end of this month, ramp up to $435 million in ARR in Q1 2027, and hit a full run-rate target of $750 million in ARR later in 2027.
On the balance sheet side, BRUN holds $1 billion in total assets and is projected to have $325 million in total cash by year-end ($170 million on hand plus ~$155 million in incoming project completion payments)—meaning over half of its current market cap is backed by cash alone.
Meanwhile, management is already executing aggressively on its $4B–$5B 2027 strategic hardware procurement plan, with roughly $330 million in purchase orders already submitted and accepted by primary OEM partners.
$LASE
Already Happened:
Q3 Earnings Turnaround: Revenue grew 24.6% YoY to $1.1M (first growth since Q4 2025), while net loss narrowed by 46% after cutting operating costs by 34%.
Clean Balance Sheet: Cash jumped 10x to $7.6M, $4.6M in debt was completely paid off, and the company regained full Nasdaq compliance.
Rebrand to Defense Tech: Officially rebranded to LASE Corp. to focus on high-tech defense and counter-drone laser systems, backed by new experienced board members.
New Commercial Orders: Landed a $1.05M pharma order and delivered an $800K robotic laser system for the AI data center supply chain.
What’s Next:
Nov 30 – Dec 3 Defense Expo (I/ITSEC): LASE will unveil its new Quantum Bullet™ counter-drone platform, kicking off live customer evaluations.
U.S. Military Contracts: Its Laser Shield counter-drone system is already in Phase 2 evaluation with the U.S. Air Force (and in talks with USSOCOM/Army)—any formal contract award would be a massive trigger.
Data Center Repeat Orders: Potential follow-on bulk orders after its first successful delivery into the data center supply chain.
$VKTX LLY is up another 4 VK’s again today on the back of their obesity franchise but according to our shorties there is no room in that market for a BIC drug. Kinda of like no way a little cell phone maker could topple the mighty Kodak.
$ENVX just made a massive move to clean up its balance sheet by repurchasing $100 million of its 2030 convertible notes at roughly a 37% discount, slashing debt while giving the company plenty of runway to scale its commercial model. With Honor eyeing the higher-density AI-2 platform as qualification testing continues, management is smartly concentrating near-term resources on high-margin, fast-growing markets—drones and smart glasses—where demand is already translating into record 34.5% non-GAAP gross margins and projected 75%–128% revenue growth for FY27.
$ONDS if Nasdaq recovers today it would have tested the 9 day and the 200 day ema. IMO very bullish. The schlongs at NVDA will pop the stockyard, maybe today ( small loss ) up in the am tomorrow, one man don't maketh a co. NVDA is a. screaming buy. Ignore the noise IF we close above the 200 day.
$TE The decline in TE’s share price following its earnings release overlooks the broader landscape. Looking at the operational execution detailed during the third-quarter earnings call, T1 Energy currently holds a substantial backlog of contracts and projects totaling 23 gigawatts (GW), with visibility extending through 2030—a figure that includes approximately 1.6 GW in newly signed power purchase agreements. Furthermore, the G1_Dallas facility is operating at full capacity, bolstered by a recent "Section 232" exemption granted by the U.S. Department of Commerce. Meanwhile, at the 2.1 GW G2_Austin battery plant in Texas, the steel and concrete structural work has been completed; management is currently engaged in exclusive negotiations with institutional investors to finalize a financing package centered on debt. With artificial intelligence (AI) driving an urgent demand for electricity, and "Section 232" policies exerting upward pressure on the prices of solar products in the U.S., the key pieces are falling into place for TE—the full picture is coming together.
$FRMI I can't get off of this idea... i think i have to take a shot.
Yesterday, owning the stock meant owning a piece of a great piece of land. The permits were in hand, some of the power equipment was already bought, but the company was borrowing money at payday-loan rates and had a giant loan payment coming due that it might not be able to make.
Today, it's the same land and the same equipment. But now the company has real cash in the bank, a rich and reliable customer — have to believe "investment grade hyperscaler" means one of the megacap tech names — has put up $200 million of its own money, and that customer will pay to build its own buildings. Fermi just has to deliver the land with the power hooked up.
Before today, the risk was they might go broke before they finish the job, and now today they have the money, and the buyer, to actually finish. For a company that's still building everything, not going broke before you finish is the whole ballgame.
$SPCX SpaceX announced today that it plans to build a new supercomputing complex in the United States, with a total investment exceeding $74 billion. The initiative includes the construction of a facility at "Starbase" in Texas, as well as a second project in Cochise County, Arizona—all aimed at expanding the company's ground-based artificial intelligence computing capacity.
SpaceX’s primary existing supercomputing footprint is the Colossus cluster along the Tennessee–Mississippi border.
At Starbase in the Rio Grande Valley, SpaceX intends to invest more than $24 billion in a supercompute facility.
The Arizona campus is planned at roughly $50 billion and is expected to create about 5,500 construction jobs and 1,000 permanent positions.
SpaceX is now targeting 2.5GW to 3GW of compute capacity by the end of 2026 while also developing the Starmind orbital constellation.
$HUMA
1/2 Confirming the exact steps detailed by management during the last call regarding the sBLA for hemodialysis (AV access):
1. Filing (November): The documentation is being submitted this month, backed by data from 3 Phase III studies. Notably, showing extraordinarily solid and consistent evidence in the female subgroup and in patients at high risk of fistula non-maturation.
2. Acceptance Window (60 days - January): The FDA has 60 days to formally accept the application. In January, we will officially know if they accept the filing and, crucially, if they will grant Priority Review. Given that the product holds an RMAT (Regenerative Medicine Advanced Therapy) designation, there is a strong probability of getting it.
$CBRS Cerebras Systems is developing wafer-scale AI processors designed to accelerate high-performance computing and AI inference.
**Key Bullish Catalysts:**
1. **OpenAI Partnership:** Expanding AI deployments could drive significant demand for Cerebras computing capacity.
2. **Unique Technology:** Its wafer-scale architecture offers a differentiated approach to high-speed AI inference.
3. **AWS Integration:** Planned Amazon Bedrock integration could expand access to enterprise customers.
4. **Upcoming Earnings:** Q3 results are due November 12 after market close, with investors watching revenue growth and margin trends.
**My Take:** CBRS has an interesting position in the rapidly growing AI infrastructure market. Its technology and strategic partnerships offer meaningful growth potential, but operating losses, margin pressure, and customer concentration remain key risks.
$HIVE is a sleeper AI play—mining 10+ BTC daily for steady cash, locking in $200M in AI cloud ARR with Cohere, and sitting on 500 MW of prime power & land with minimal dilution!
$RZLV almost 12% ctb...what is the point of holding 43 million short shares with valuation this low and company growing rapidly?
Especially if the rotation from infrastructure spending into other aspects of AI is imminent.
This is an incredible entry point or chance to dca.
I can't explain the short rationale but I'm glad they are sticking with it.
Or they just can't find enough shares to buy even if they wanted to cover?
$EOSE Ever since the earnings announcement and the good news, there have been frantic attempts to cap the share price.
Naked short selling by market makers is even more rampant than usual; it’s skyrocketing (exempt volume, Green in the picture), and they’re actually only allowed to do this to provide liquidity. However, with nearly 20 million shares traded a day, there’s plenty of liquidity, so it’s a lie to claim they’re deliberately engaging in illegal naked short selling.
But apart from that, the short volume ratio is soaring to over 50% and 60% (orange Mark), and despite the massive lid, we’re rising every day. The spring is wound tight and will soon snap. Don’t sell then – this thing is going to explode. Every second share is short, so there are hardly any shares left for short sellers to cover their positions. If there are no shares to cover the price will go into space. Lets burn them! We have time they dont!
$GRRR I think it’s reasonable to believe that as the notes mature and revenue ramp kicks in well before the 2031 mark that the cash will be used to pay off or restructure the debt as well as “ some dilution” that’s why the bonds and private financing are full of potential ways to pay back the debt. I truly believe Jay and Bruce see how they can minimilize the dilution while still maintaining the debt until margin/cash flow handles those concerns. Yes there will be some dilution, but hopefully all this fear of 70 million more , etc just amounts to insurance for the issuers of debt. I don’t think we will get worst case, I think we’ll get pretty dang good with 10-20 million added shares over the next few years while they pay most back in cash. When Jay said 12-18 months come talk to me about cash flow, I do believe him. I think they got everyone on board for a successful 5 year run.
Bruce still needs to answer “the coming days”
$GME is no longer just a "meme stock"—it has evolved into a bona fide "turnaround" investment opportunity.
🔹 Wall Street has issued a "Buy" rating (with a price target of $33)
🔹 A thriving ecosystem for trading cards and the resale of pre-owned goods
🔹 Ryan Cohen has made a massive investment, acquiring millions of shares
🔹 Poised for its strongest performance of 2024
Momentum is building rapidly. What do you think the price target for $GME will be by the end of the year?
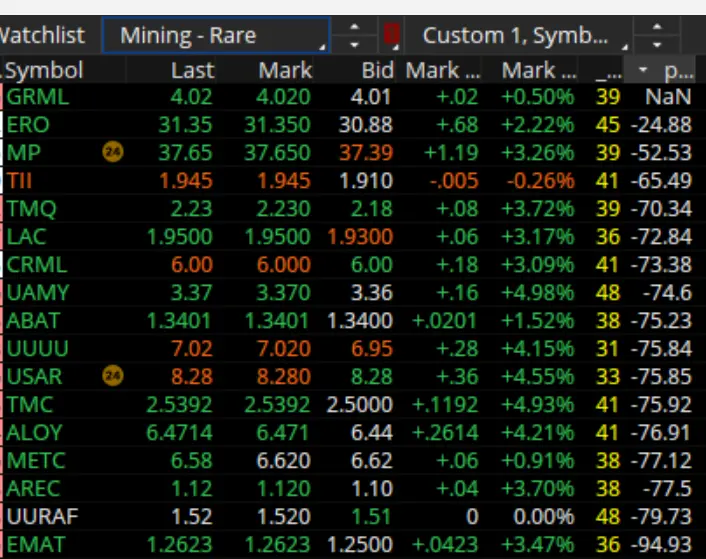
$CRML $MP $USAR Ummm… Seems like all REE’s are catching an upward bid today. The market is waking up that 2027 is right around the corner and real things are coming to fruition. Go Longs!