$GRAB at $2.75, while the analyst consensus shown sits at $6.
That’s 118% potential upside. Even the lowest target of $4 sits around 45% above the share price.
Targets aren’t guarantees, but that’s a gap worth looking into.
Are you interested at these prices?
@corleoneinvests It tells me investors are waiting for more or that there are uncertainties among investors. That’s when I start digging to find out more.
$MRVL
A brilliant acquisition or an expensive mistake?
Marvell is reportedly close to acquiring Lumentum ($LITE), and the market is being cautious.
The strategic logic is certainly there.
Lumentum supplies critical optical components used in AI data centers. An acquisition could strengthen Marvell's position in AI infrastructure, secure important components and expand its optical networking business.
BUT THERE IS A CATCH.
A strategically attractive acquisition doesn't necessarily mean it's a good deal for shareholders.
Lumentum has already experienced an enormous rally, and acquiring the company could require substantial financing.
THAT RAISES SOME IMPORTANT QUESTIONS:
How much of a premium will Marvell pay?
Will shareholders face significant dilution?
How much debt would the company need to take on?
Can the long-term benefits justify the acquisition price?
The market's initial reaction suggests investors are taking these risks seriously.
NOW LOOK AT THE CHART
$MRVL is approaching the $205 support zone, an area where buyers have repeatedly stepped in over the past few months.
This is where things get interesting.
We have a historically important demand zone being approached during a period of significant fundamental uncertainty.
A successful defense of $205 could open the door for a recovery toward $$250.
But if buyers fail to show up, the $180 support zone becomes particularly interesting, especially with the 200-day SMA at that area.
And with a potential deal announcement reportedly coming as soon as next week, the timing couldn't be more interesting.
The question isn't just whether $205 will hold.
It's whether investors will see this selloff as an opportunity or whether the potential cost of the acquisition will keep buyers on the sidelines.
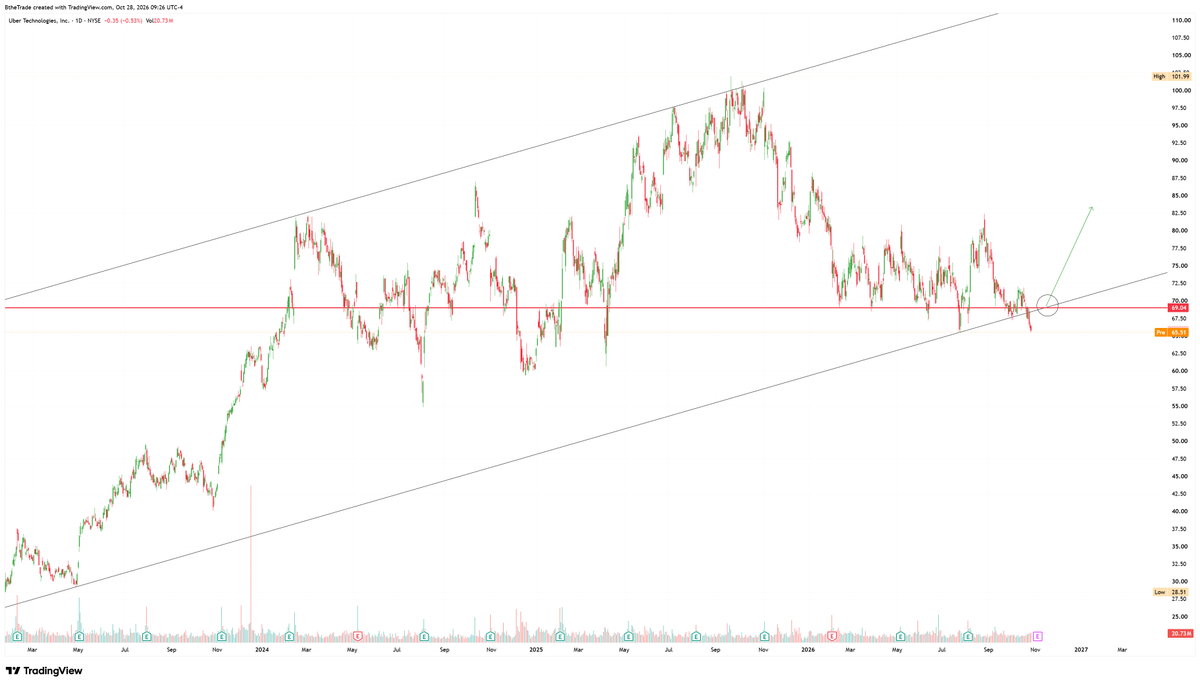
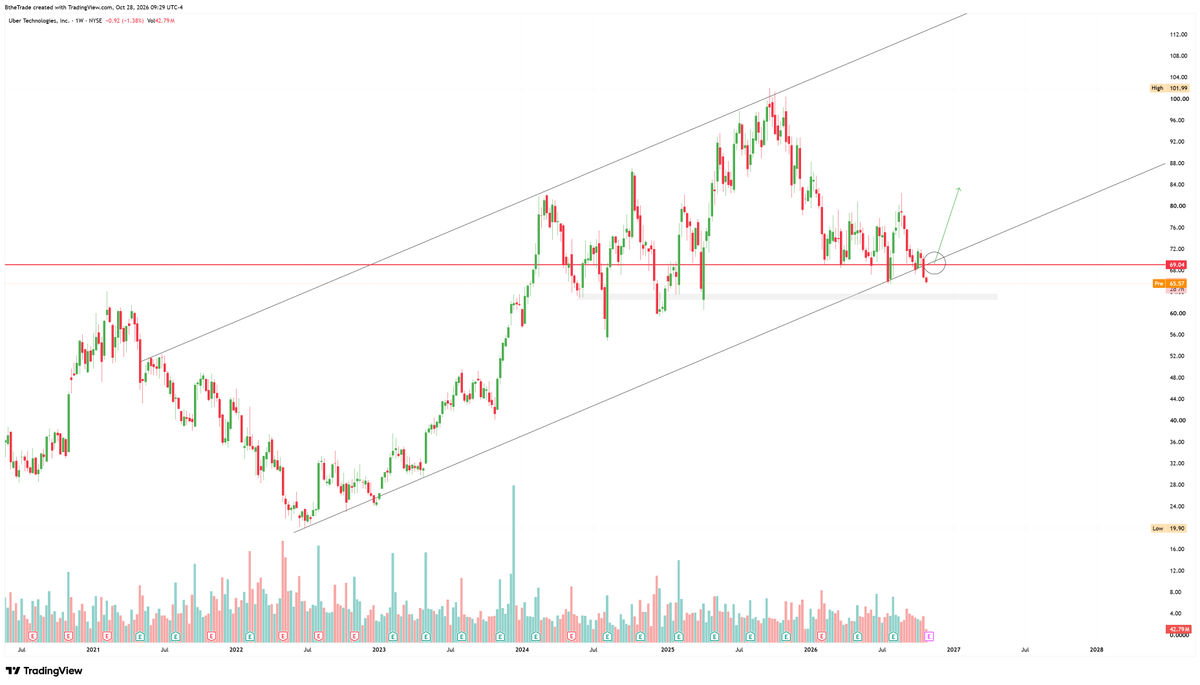
$UBER Multi-year trendline failed on rising volume.
But this could be the most bullish signal for this stock.
IF we see a reclaim of the trendline which aligns importantly with a clear liquidity level - It would be a gift.
$64 is an important reaction level and with earnings coming up, anything can happen, very quickly.
Big news for $ORCL.
Oracle expects to turn free cash flow positive in the second half of FY2028, targeting over $30 BILLION in FY2029.
A very encouraging development considering the concerns surrounding its massive AI infrastructure spending.
The stock jumped as much as 13% on today's investor day announcements, yet remains down 26% YTD.
$ORCL holders are for sure having a blast today!
$ORCL TO THE MOON 🚨
Investor day just delivered BULLISH news for investors:
• Capital spending to peak in FY2027-FY2028
• Positive FCF in second half of FY2028
We are finally seeing spending reductions for the future and the street is LOVING it.
$BULL returning to a very interesting zone here.
That $5.50 area has attracted buyers multiple times this year, producing some significant rallies.
Looking for buyers to show up again. Even if we lose it, a reclaim followed by a successful retest would be worth watching.
Q3 earnings coming up in November.
After 51% revenue growth and a 31.5% adjusted operating margin last quarter, can Webull keep that momentum going?
“Webull might be the most undervalued fintech stock.”
No question in my mind. $BULL
What stands out is the combination: growing revenue, widening margins, and the opportunity to build a much larger global business. International expansion and a broader product lineup give Webull multiple ways to deepen customer relationships and generate more revenue from the platform.
The potential goes beyond adding accounts and attracting deposits. It’s about becoming more useful to existing customers while turning that activity into sustainable earnings.
That’s why the business deserves more attention than the daily chart. Management still needs to translate its progress into value per share, but I believe the market is underestimating both the business today and what it could become. 🤝
I'd be looking at $7 as a potential upside level, but there's a lot that needs to happen before that becomes realistic. Lower TF structure is still bearish, the broader sector remains weak, and earnings are coming up. I'm more interested in seeing buyers step in and the structure shift before talking targets and deadlines on those targets.