$BMN is pleased to provide a construction update on its Etango #Uranium Project in #Namibia 🇳🇦 Early works are tracking in line with budget & schedule 🚧 Spending rate remains conservative, maximising corporate flexibility💰Read the full update here: https://t.co/6cgRD2GmY8 ⚛️ $BNNLF
$BMN CEO Gavin Chamberlain & VP-Corporate Development, Matt Horgan spoke with @CruxInvestor this week. Discussing the progress at the Etango #uranium project, risk mitigation & political stability of #Namibia 🇳🇦 https://t.co/sZAKmSddtM
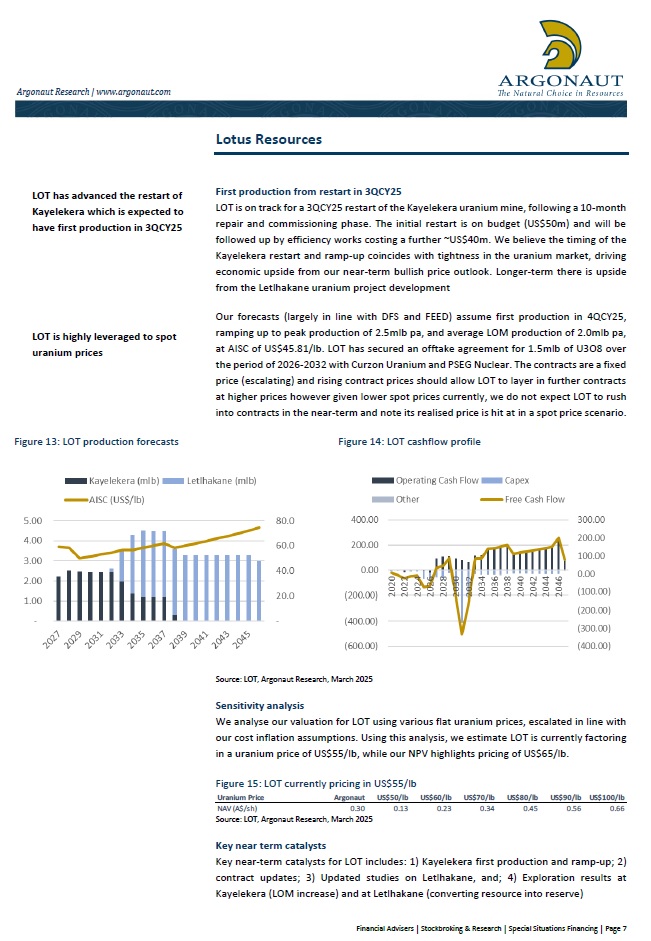
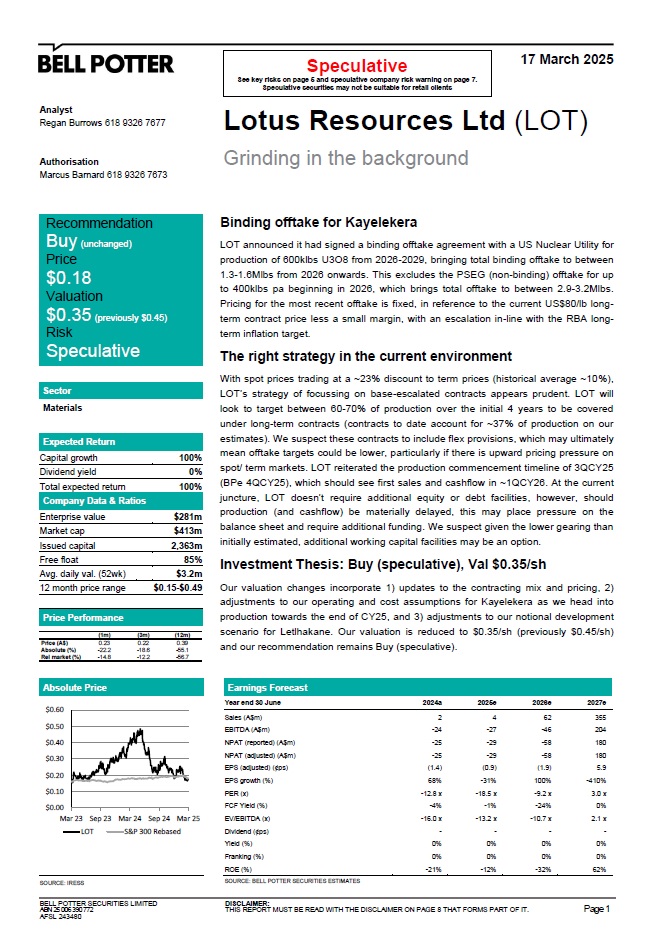
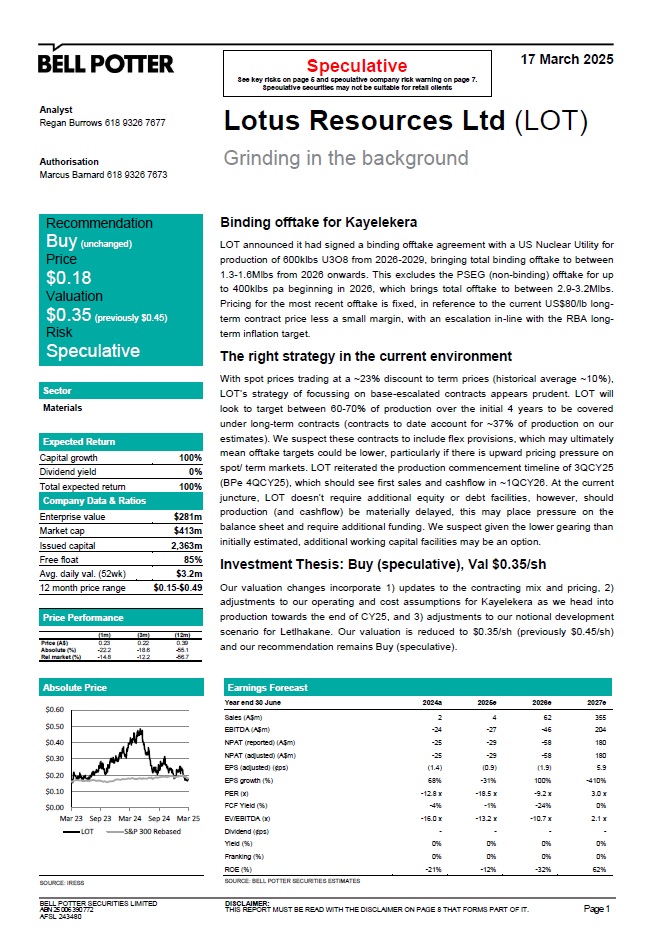
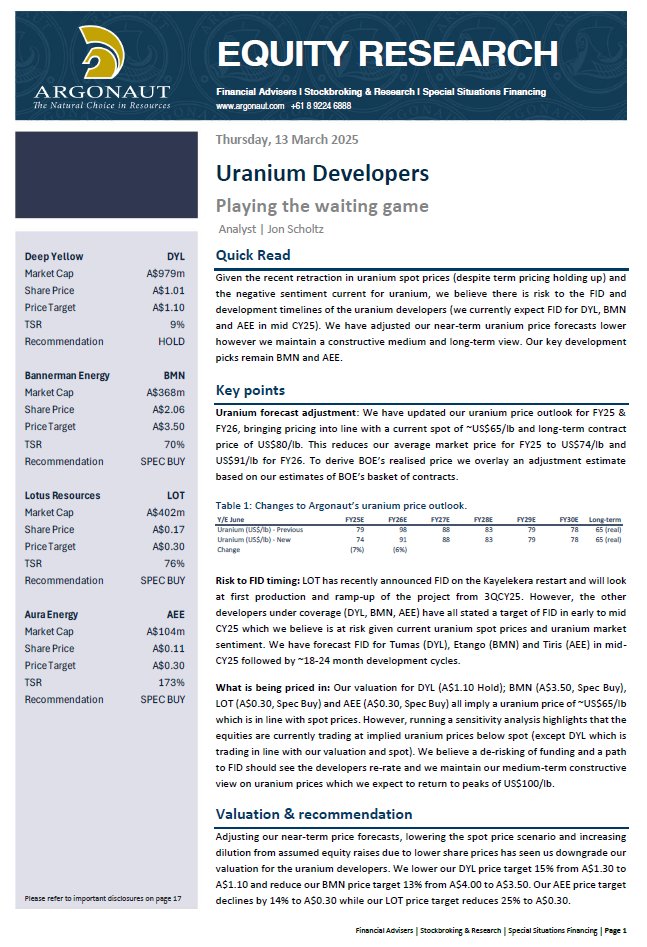
Latest research on #uranium developer @Lotus_Resources $LOT below.
Bell Potter — $0.35/share valuation — "With spot prices trading at a ~23% discount to term prices (historical average ~10%), LOT's strategy of focusing on base-escalated contracts appears prudent."
Argonaut (part of broader sector report) — $0.30/share target — "We believe the timing of the Kayelekera restart and ramp-up coincides with tightness in the uranium market, driving economic upside from our near-term bullish price outlook. Longer-term there is upside from the Letlhakane uranium project development."
$FMC.V $FDCFF #uranium
The Thelon Basin, home to over 50 uranium targets and located adjacent to Orano’s 127M pound Kiggavik deposit, is quickly emerging as a world-class uranium district. $FMC exploration efforts continue to uncover signs of significant mineralization…1/3
Updated Scoping Study for our Letlhakane #Uranium Project in Botswana: https://t.co/1Qf8f55mKh
The Study has confirmed the project’s potential to become a significant uranium operation and complements production at our Kayelekera Uranium Project in Malawi, which is on track to restart in Q3CY25. Lotus $LOT aims to become a globally significant U3O8 producer when combining both assets.
Our Managing Director Greg Bittar commented: “Our updated Scoping Study validates Letlhakane’s merits as our second uranium project that can meet the longer-term supply shortfall. In a strong long-term uranium price environment, which experts have forecast, Letlhakane has a potential production life of 10 years. Coupled with Kayelekera, where we aim to restart production in Q3CY25, this positions Lotus as a ~5.5Mlb per annum producer, potentially making it one of the largest uranium producers on the ASX.
Our optimisation programs have delivered promising results to potentially decrease the cash cost from US$41/lb to US$35/lb for this selected case. We also recognise there is further mineral resources not yet included in the production schedule that could be incorporated in the future, namely ~23Mlb uranium contained within Indicated Resources and 46Mlbs in Inferred Resources.”
@AfricanLonghorn Yeah for such a solid company I forgot buying in 2017 when it surged big time the years after it's a big drop for just changing CEO, it could be a big red flag that's why I sold Vimy once and then it surged big time so buy more I say? Or hold your shorts 🤪😬🍀
Full speed ahead: Latest Petra Capital report on #uranium developer @Lotus_Resources $LOT below, with a Buy + $0.28/share price target.
"The refurbishment of the Kayelekera Project is well
underway, targeting first production in Sep. Q’25 and
first revenue in Mar Q’26," analyst Colin Mclelland writes. "Lotus ended Dec. Q’24 with cash of A$132.8M, and has since signed term sheets for an additional US$38.5M in debt facilities. LOT has secured additional offtake from existing partner PSEG. Our NPV suggests upside approaching 55% at current depressed prices. Market ratings highlight the potential upside as LOT makes the transition from brownfield developer to producer, regardless of investor sentiment towards the sector. Maintain BUY." ⬇️