What if regulatory intelligence didn't have to be this chaotic?
At ComtIQ, we turn complex regulatory proceedings into actionable intelligence — uncovering the arguments, stakeholders, risks, and opportunities that matter for business decisions.
38 proposed rules close for public comment between Nov 18 and Nov 24. Closing first
FCC, Television Broadcasting Services Des Moines, Iowa (Nov 18)
EPA, Air Quality Plan; Arizona; Pinal County Air Quality… (Nov 18)
#PublicComment
@cfo The perk threshold going from $10K to $150K is going to be the most quoted line in this whole release. Comment file just opened, we'll be watching who shows up 👀
Two SEC proposals, one puzzle 🧩 May's filer status rule decides WHO still has to disclose executive pay. This one decides WHAT they disclose. We already went through the 206 filings on the first. Comment file on this one just opened. Our calls on the first one are public: https://t.co/Njs0R60mdv
@claudinecassar 404(b) is the loudest fight in the file, no doubt. The quiet one: almost nobody defended the 5-year seasoning period, on either side. That's our pick for what changes first.
@leadlagreport The plot twist, the May filer status proposal would already drop say-on-pay and CD&A for ~81% of public companies. So these two are going to be read side by side for a while 👀
@AllinAI_US Fun detail from the comment file: almost everyone likes the two-tier part, even the people who hate everything else. The $2B number is where the real fight is. We think it survives, but we wouldn't bet the house on it 😅
The SEC wants to move ~81% of public companies into its lighter reporting tier. 206 filings later, everyone has an opinion!! So do we!!
We put ours in writing, with odds and dates. Here's where we think the final rule lands 👇
1. Final rule adopted by June 30, 2027: LIKELY (55-80%) This is the centerpiece of the Chairman's public company agenda and nobody on the Commission is pushing back.
2. Two filer tiers survive: VERY LIKELY (80-95%) Large accelerated filers and everyone else. Even letters that hate the rest of the proposal like this part.
3. The $2B threshold stays: LIKELY (55-80%), low confidence The record leans against it. Plenty of commenters pitch $1B, an inflation adjustment or a revenue test. But $2B is the headline number, and agencies don't count letters like votes. We could be wrong here, which is why we flag it.
4. The 5-year seasoning period gets trimmed: LIKELY (55-80%) The one thing both camps agree on. Supporters and critics of the rule pushed back on 60 months. 5. Rule withdrawn or re-proposed by end of 2027: VERY UNLIKELY (5-20%)
Every call is logged with a date and scored hit or miss when the rule comes out. No edits after the fact. Think we're off? Make your own forecast and we'll score you the same way.
This is a substantial rewrite of Item 402 (S7-2026-39). Moving to a principles-based, materiality-focused framework while cutting NEOs to CEO and CFO and simplifying the tables will generate coordinated comments from investors, compensation consultants, and issuers.
We’ll be reading the full record to see which arguments can actually move the final rule. Comments are still open.
This is a substantial rewrite of Item 402 (S7-2026-39). Moving to a principles-based, materiality-focused framework while cutting NEOs to CEO and CFO and simplifying the tables will generate coordinated comments from investors, compensation consultants, and issuers.
We’ll be reading the full record to see which arguments can actually move the final rule. Comments are still open.
The $329M figure is the kind of number that drives comments. Limiting mandatory tables to CEO and CFO under S7-2026-39 will produce clear camps: those arguing the change reduces transparency on the broader leadership team’s incentives, and those arguing the current five-person approach adds noise without proportional materiality.
We’ll be watching which arguments show up in the docket and which ones the SEC will find hardest to set aside when it writes the final rule
S7-2026-39 is one of the bigger Item 402 rewrites in years. Narrowing NEOs to CEO and CFO, collapsing the tables, and lifting the perks threshold to $150k will draw organized comments from both sides, investor groups focused on pay-versus-performance and pay ratio visibility, and corporate counsel focused on materiality and burden.
We’ll be reading the record as it comes in. The arguments hardest for the SEC to dismiss usually aren’t in the form letters; they’re in the detailed filings that address what remains material for shareholders under a principles-based approach. Comments are still open.
Whether an agency finishes a rule or lets it sit is often clearer once you see which arguments in the comment record are hardest to dismiss and how organized the campaigns are. Midterms don’t stop the process, but the content of the record does shape the final text and the litigation risk.
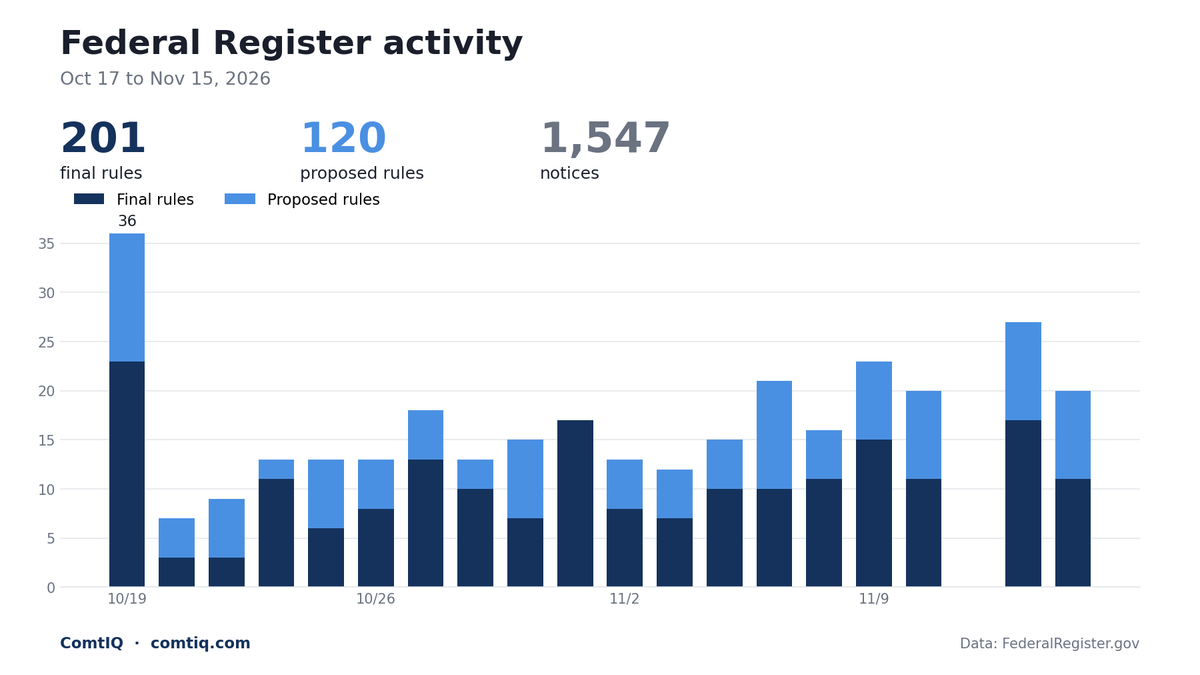
Federal Register, last 30 days (Oct 17 to Nov 15)
201 final rules
120 proposed rules
1,547 notices
Busiest day for rules was Oct 19, with 36.
#FederalRegister#Rulemaking