honest take - we’re not completely sure. as we go deeper with our customers more and more blue sky opens.
where we’ve decided to focus -
1) bring ai to some of the biggest banks in mexico,
2) help them automate complex and very manual underwriting workflows so they can serve more borrowers,
3) help them navigate financial regulations for ai with good system design (on-prem, data residency, iso/soc-2),
4) design new financial products with bank, insurance and capital market partners that serve an under-financed market and move our business to an ai outcome/services model
5) leverage the distribution of our bank customers and our growing network to match the right borrower to the right form of capital.
tldr we’re building new financial infrastructure powered by agents that works with existing financial institutions and helps them leap frog manual processes and archaic tech.
and we’re doing this where there is incredible pain across the ecosystem (from banks to borrowers to capital partners) and thus a ton of room to run
I repurposed our data pipeline at Hamlet, which is normally used to analyze public meetings, into a way to analyze all of Jensen Huang's long form interviews since 2021 (that I could find).
Really interesting stuff - there are definite trends over time across a wide variety of subjects ranging from AI Safety to how much he talks about the United States, and competition.
Enjoy!
agree too. we’re building in enterprise and see a similar philosophy leading to experiences that are landing more and more customers. chase the magic i guess? @karine_hsu@FarzaTV 🪄🦄
really agree with this product philosophy -
things are moving so fast, building consumer in 2026 really means just trying stuff, chasing curiosities, and shipping magical experiences :)
@DarioAmodei i saw a recent interview where you shared your concerns about ai not diffusing equally geographically and serious advantages accruing to those closest to ai like in sf and what this means for the world. you should consider investing in startups like ours @rizalaihq that are squarely focused on brining ai to some of the most important enterprises/institutions in emerging markets (banks and insurers) that with ai will expand financial access considerably. we’ll take employee daf contributions or @AnthropicAI credits too 🙏😂
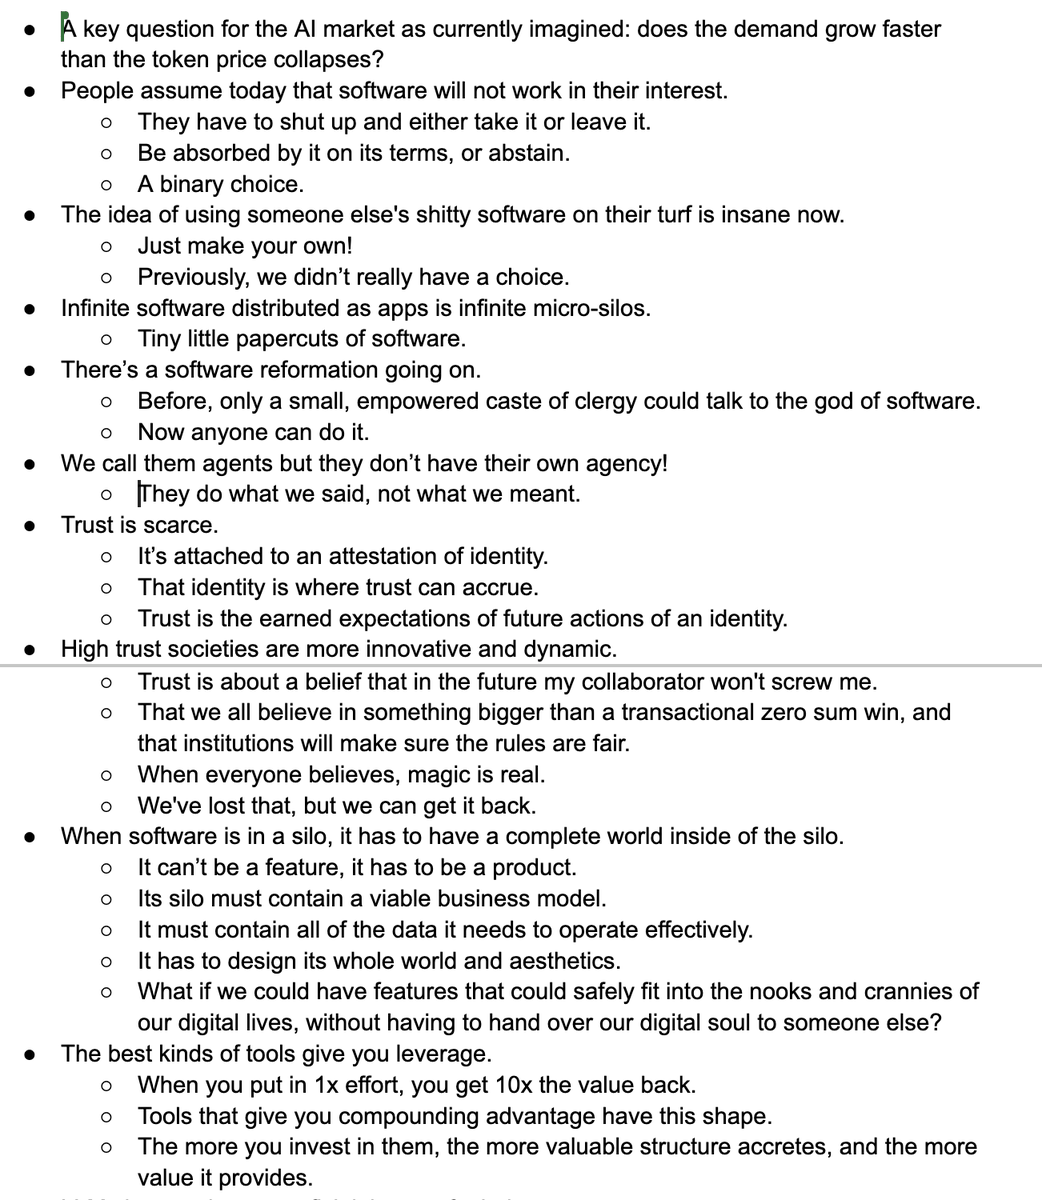
I just published my weekly reflections: https://t.co/aJyKZp7PTh
Infinite papercuts. Absorb or abstain. The Software Reformation. Trust as earned expectation. AI Spandrels. Having to believe to see. Arm's length software. Social vibecoding. The edge of criticality.
i had a conversation with astra tonight while rocking my 2 month old to sleep. it turned into an investor memo of sorts. here’s the transcript
https://t.co/52htMop8U7 via @LinkedIn
Marc Andreessen says the gap between what AI-native startups and incumbents think AI can do is "the widest he's ever seen."
His exact words: "The AI-native early stage startups have just a completely different view on what they can do with AI than the typical incumbents in almost any industry."
Not slightly different. Completely different.
That's the actual risk for large companies right now. It's not slow adoption — it's a fundamental miscalibration of what AI is capable of. The startups competing against them haven't made that mistake.
The asymmetry compounds fast. Incumbents build roadmaps around a floor. Startups build businesses around a ceiling. By the time the floor catches up to the ceiling, the market has already moved.
@abishekv like and subscribe! love what you guys are building at @MonacoGTM. ended up not being able to beta test because we’re live in mexico but soon…
i think we’re going to see a pretty radical change in how software companies are staffed over the next 3 years..
for the last 20 years, the most expensive thing in a software company was building the software. so we built entire organizations around engineering capacity.
PMs figure out what to build. designers design it. engineers build it. sales sells it. CS handles the customer.
AI is going to completely upend this..
1/ the distinction between PM and engineer will start to disappear. PMs who can’t build and engineers who don’t understand customers will both struggle.
2/ the best engineers will spend a lot more time with customers. understanding the problem, building the solution, seeing if it actually works.. without 5 layers of handoffs.
3/ the value of customer understanding will go up dramatically. not because AI can’t talk to customers, but because building 10 features is becoming easier than figuring out which 1 actually matters.
4/ distribution becomes even more important. when 100 companies can build roughly the same thing, the one that knows how to reach customers and earn their trust wins.
my bet is that the best software companies in 3 years will look very different.. far fewer handoffs, much smaller teams, and people who own problems end to end.
we spent 20 years organizing software companies around the scarcity of engineering.
that scarcity is going away.. but the org charts haven’t caught up.
very true. so far i’ve found being honest with myself and my successes and failures and especially where i can improve and how i can improve has been super powerful
https://t.co/3QFmTv5dCd
honest take - we’re not completely sure. as we go deeper with our customers more and more blue sky opens.
where we’ve decided to focus -
1) bring ai to some of the biggest banks in mexico,
2) help them automate complex and very manual underwriting workflows so they can serve more borrowers,
3) help them navigate financial regulations for ai with good system design (on-prem, data residency, iso/soc-2),
4) design new financial products with bank, insurance and capital market partners that serve an under-financed market and move our business to an ai outcome/services model
5) leverage the distribution of our bank customers and our growing network to match the right borrower to the right form of capital.
tldr we’re building new financial infrastructure powered by agents that works with existing financial institutions and helps them leap frog manual processes and archaic tech.
and we’re doing this where there is incredible pain across the ecosystem (from banks to borrowers to capital partners) and thus a ton of room to run
a few founder friends have encouraged me to start building in public. as someone who isn’t social media native nor do i have a tik tok account, don’t use ig, barely know how to tweet, and still struggle with emojis, definitely strong founder market fit ;)
but if it means bringing more people into the boat of the most important startup you’ve never heard about, let’s go 💪🚀
behind every company there’s a person, a family and a dream. and lots of thankless hard work and sacrifice.
i am reminded of this daily.
my mother in law moved halfway around the world to help my wife and i take care of our newborn and two year old, and give me time back to focus on rizal. she speaks little english and left her husband at home because he’s too old to travel. apart from us and a neighbor she knows no one here. morning walks and our weekend trip to costco is her time outside the house.
but every day she wakes up early, helps me get our toddler off to school, and makes lunch and dinner for the family while also watching our newborn when my wife naps in the afternoon.
rizal wouldn’t be possible without bà (grandma). behind every business there’s a bà.
I canceled a bunch of non-critical VC relationship meetings I had scheduled for December and January. I think I should have done it sooner.
Last week I had a bunch of these catch-up meetings, and I kept thinking, what am I doing here?
E.g., We're not raising right now. I like these people and enjoy talking to them, I learn things, I build relationships that will help down the line, but it's just not mission critical.
Someone put it to me this way: having meetings is a VC's job. It's their KPI. Fundraising is only my job at certain points in time.
I think I just need to get better at saying no to people I like :)
https://t.co/KTnYaGX5PS
from our customers: “can you help us set up ai at our bank?” … “absolutely”
the majority of mexico’s banking industry (usd$880b) is struggling to set up ai, especially ai that is cnbv compliant.
we’ve spent the last two years building trust with some of the largest banks in latam and mexico, and have helped underwrite usd$250m. we also have the support of the central bank’s fira organization and a killer wedge product that shrinks weeks of underwriting workflows into minutes
our business in one sentence: we bring regulator-approved ai and new financial products to banks and insurers and make money on these financial products and implementation fees.
“so what do you guys do?” as a first time, early stage founder i inferred that i needed a smart-sounding answer that hit a bunch of on-trend terms popular in investor circles. and as i consulted chatgpt these pitches strayed further from my voice and vision.
so i revisited from first principles what matters in a pitch or any story. know your audience.
and started listening to investors i thought were smart talk about their books, life etc in interviews. i’ve consumed probably a hundred plus hours of this content over the last year.
my take away - great businesses are easy to understand and don’t need any fancy words.
and sharp investors at seed stage are backing the founders and team. so be authentic