For compliance purposes, I’ll no longer be posting.
DMs open if you want to stay in touch, chat ideas, short theses that hinge on SBC/D&A accounting, best Lil Wayne mixtapes, etc.
+Obligatory blurry pic of the dog
PRMB
Look, I’ve never done sales for Primo-
But I’m having a hard time believing “ABC Financial Institution” is deeply concerned about critical vendor risk from the guy who refills the break room water cooler.
PRMB
Didn’t hit the soft guide of +ve customer adds in December, but at this px (8x EBITDA), (improving) directionality is probably what matters
H1 likely will have added integration spend (SAP & WMS), so hope is that’s offset w/ improvement elsewhere-
E.g.: truck loading recovering from horrible 80% efficiency (?) to the standard 99% that aids in realizing route density, not having to deal with angry, churning customers, etc
So, mgmt’s story / street algo is back to very modest +ve topline in ‘26 on volume recovery/minimial px + easy comps w/ slight margin improvement
Ideally, integration is less of a headwind & mkt looks out to ‘27 on normalized LSD growth (x-sell, other advantages of scale, Foss makes good & now able to take px) w/ more margin upside
FCF’s always been the issue here (high capex + leverage =bad conversion), but leverage is surprisingly inoffensive now @ 3x & can see a more palatable 2.5x by EoY ‘26.
+A promise of the tie up was less capex intensity (scale adv + PRMW stops doing dumb things like building nat gas fleets)
Regardless, trajectory & out year picture continues to improve:
Rerate ~$1.5B ‘26 EBITDA to 9x (I believe legacy PRMW traded around here or higher? Despite being a worse biz) >>
$25 stock, 30% upside & potential for ~20% CAGR in ‘27+ w/ cash gen, bbk, & value accrual to eqy
Bonus: comp coming market w/ Nestle’s water biz. Latest rumor was €5B @ 10x €500M segment EBITDA
BJRI
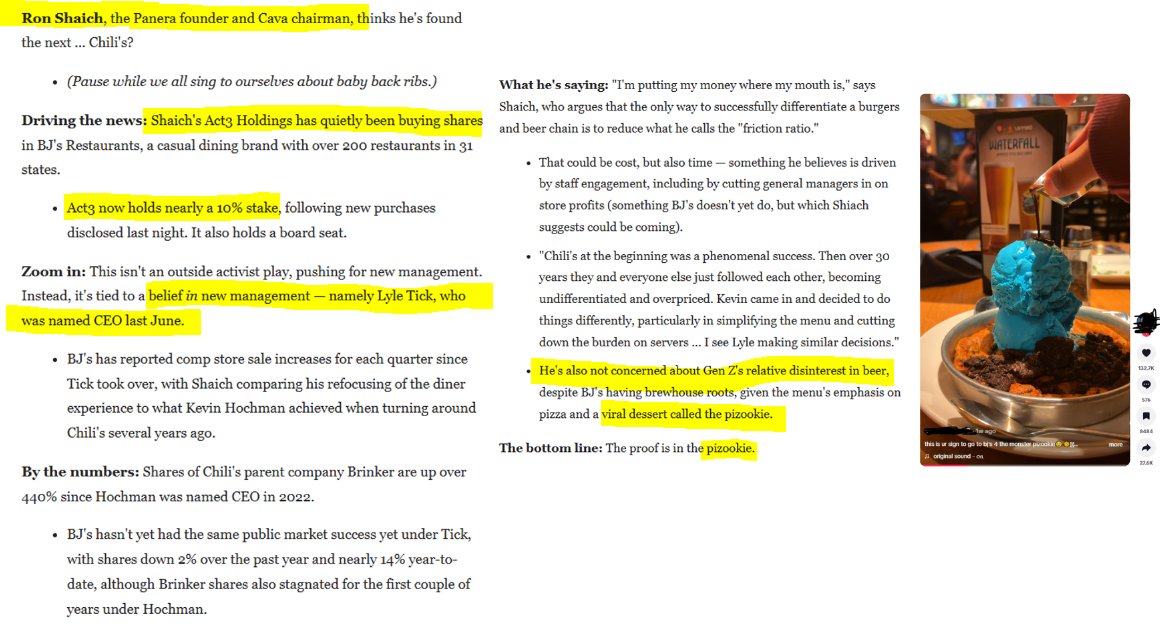
Nice call out by Axios the other day on Shaich's large & growing stake
Shaich's been involved/a rep of his has had a director's seat since at least 2020 & I'm sure helped pick Tick
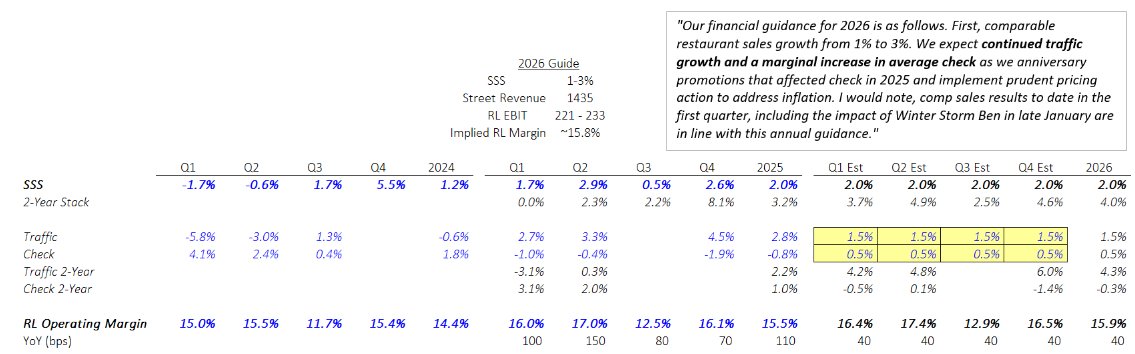
Eyeballing comps- decent & improved in '25, guiding for more of the same in '26, & largely traffic driven. If the guide holds >> accelerating comps on a 2 yr basis.
(Check decline seems mostly a mix issue- blame the growth of the late night crowd- pricing is steady to slightly up)
RL margins up 100 bps over the period, implied guide for another 40 - 50 in '26. So, not jamming promos for traffic / or can at least manage costs
And, most importantly (see: Chili's mozzarella cheese pull craze)-
BJRI has a semi-viral social media hit in its Pizookie dessert.
@stoic_point Unrelated- what do you think (or have heard from the company) mature gross/EBITDA margins are?
I’m assuming the previous mgmt’s 60%+/10-15% are probably stale.
Or waiting till June investor day for a real update?
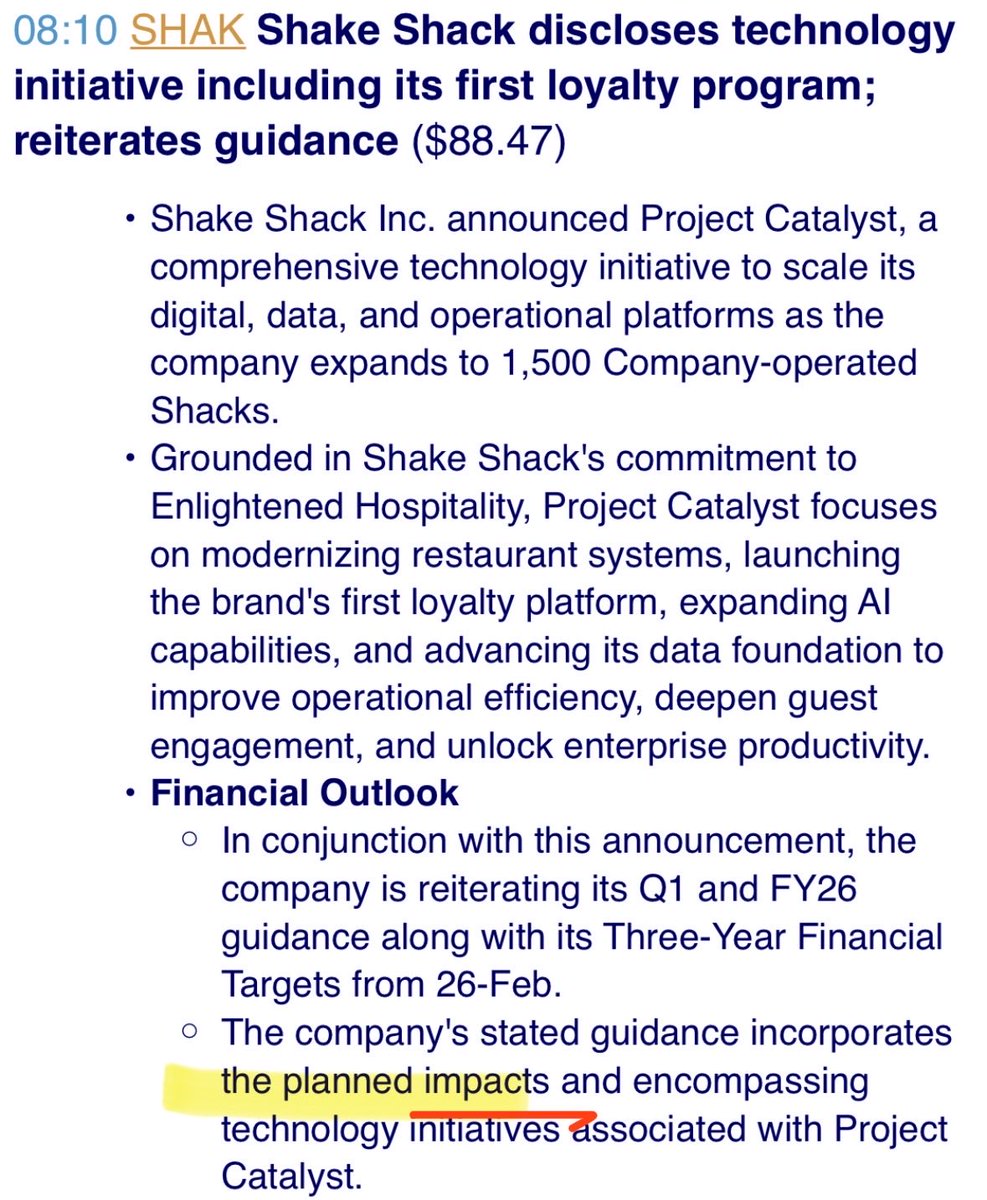
SHAK
Hmm
Skimming the presser, this has some ERP-overhaul adjacencies (read: the difficulty is always underestimated & generally tough for the stock)
Conversely, based on the language, were they tracking to nicely beat sans the costs of this upgrade program?
@west4thstreet Hang on now. In RPAY’s defense-
Failed shop of the co, aggressive bbk + delevering didn’t help the stock, co-founder left, CFO turnover, new cash bonuses…
The only thing left* on their bingo card is big, dumb M&A
(*Doing the hard thing & actually fixing the biz doesn’t count)
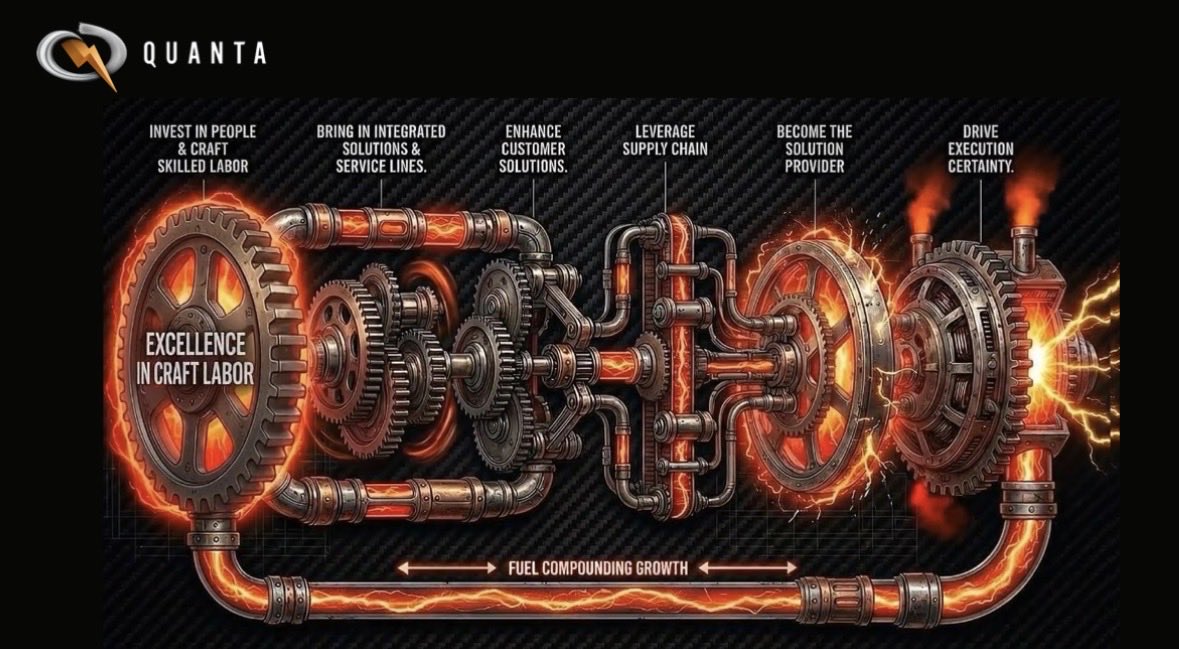
PWR
Investor day decks are already too long as is-
Polite request to IR teams not to pad them further w/ AI slop.
(Unless this is 4D chess: AI image query >> create demand >> more work & $ for Quanta >> capitalize that $ at X multiple >> generate shareholder value)
Probably several SS notes w/ similar "GCC Rebuilding Winners" lists, but here's another (mostly US) following 2 min of research
KBR's funny- theoretically both MTS (hardening work) & STS (gas, ammonia) segments/splitCos could/should benefit-
Obvi the stock px/multiple disagrees
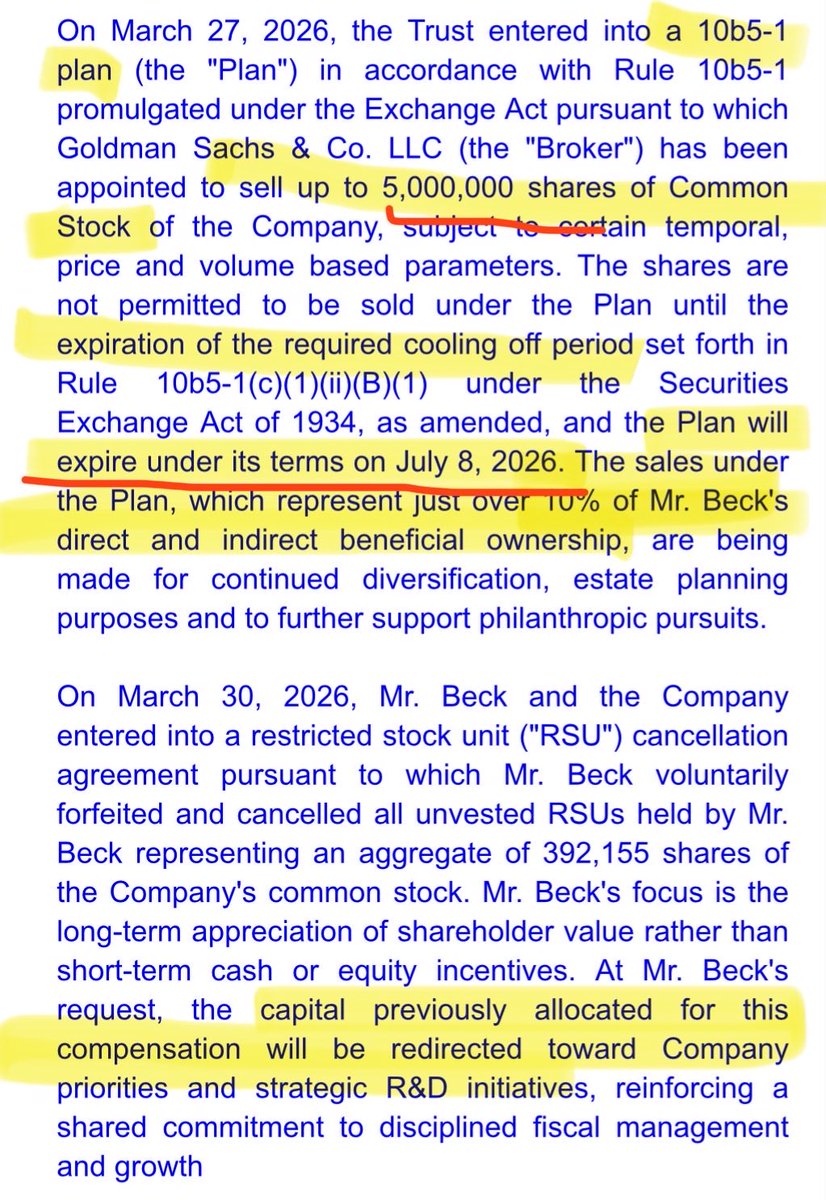
The other RocketCo
The 8-K: Beck’s giving up his base & bonus ($1.8M) plus ~$24M in RSUs
Asks to instead spend this $ on R&D
How nice.
The 13D: Beck will also be selling ~$300M of stock in a two week period starting late June
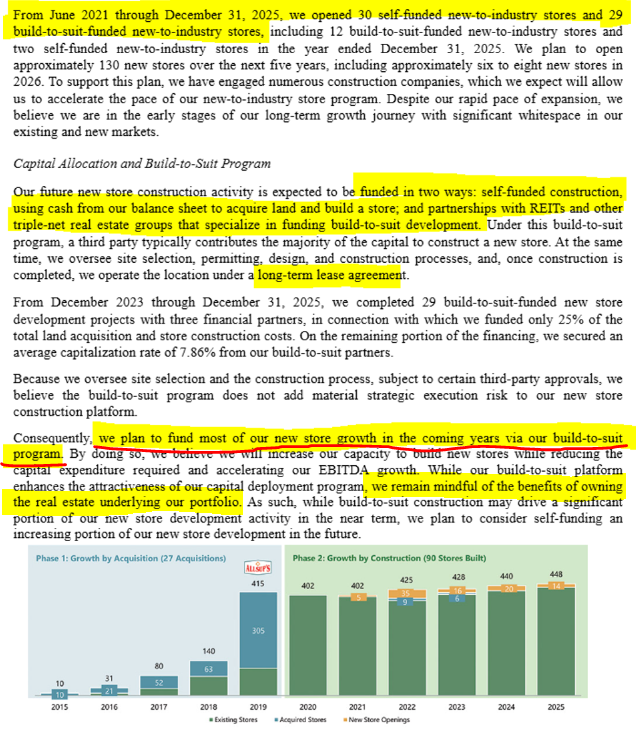
Yesway (YSWY)
Refiled its S-1
Tough time to go public...
Unless you're a value-oriented c-store (see MUSA stock MTD) that offers "destination" deep fried burritos (Eater: "one of the best gas station snacks in America") & has a quasi-cult following to the point that some people get tattoos of the store's logo
Also- anemic store growth since they last disclosed unit numbers:
403 stores in June '21 >> 419 in December '25 (net of an in-process divesture of 29 locations)
Apparently the plan now is to really accelerate growth & open 130 units over the next 5 years (ramping in '27, so ~30/yr) mostly thru a "build-to-suit" model + NNN
So:
1) Can they pull this off (i.e., actually expand organically)?
2) A lease-first approach (at least for now!) is an interesting departure from their current majority-owned model (65% of units) & MUSA (~75% owned) + CASY (all)
TLDR: I hope this doesn't trade day 1 with a silly CASY-level multiple
@atelicinvest My goal is to find a CEO that knows his biz so well that he can explain it to me (an idiot) in such a clear, concise, & informative way that I now believe I know the biz better than him
Then I can focus on what really matters: inventing narratives for 2% intraday stock px moves
MTN
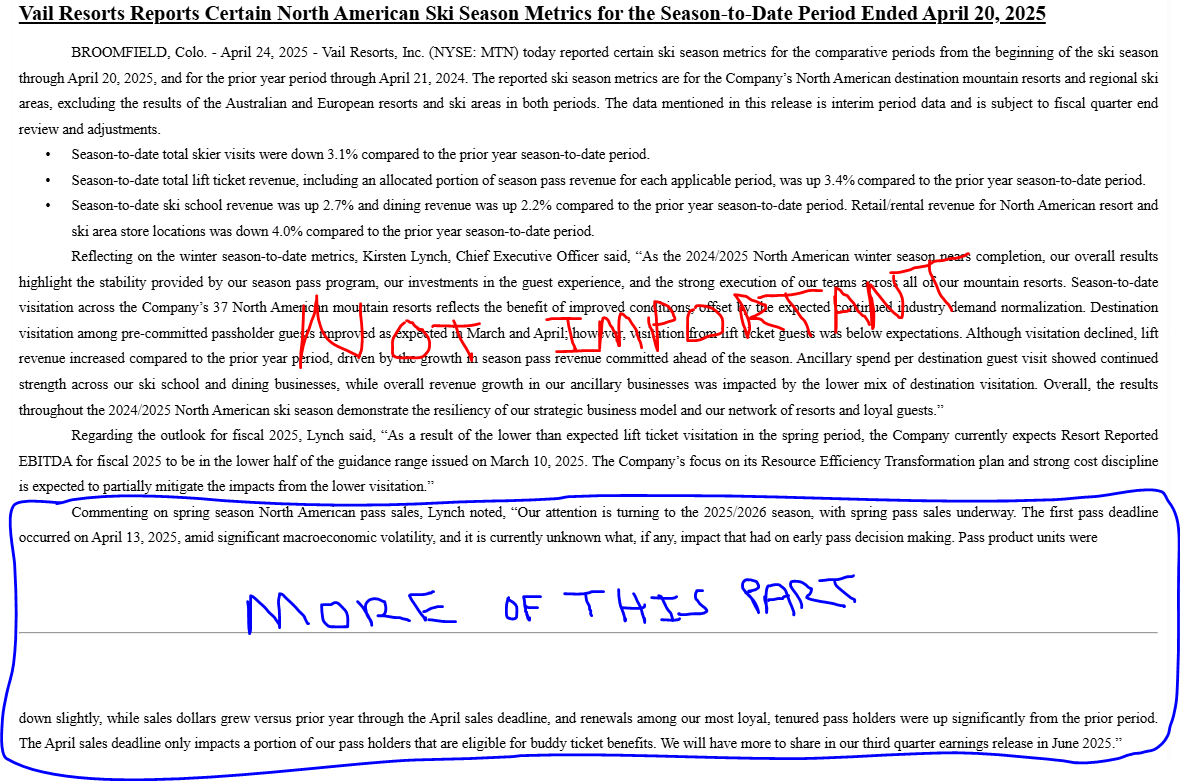
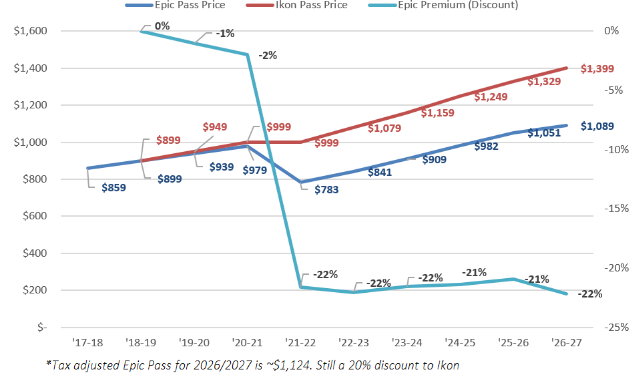
Vail typically provides an end of the season update in late April (as FY Q3 earnings aren't until early June)
Given it's:
- Katz's first April release as CEO since 2021
- This past season has been such a bust (weather) & is irrelevant for the stock
- The pass offerings for the 2026/2027 season have seen the most meaningful change in years (mostly the young adult pass, but also first full yr of Friend passes, + a slightly lower px hike)
& passes will have been on sale for ~7 weeks-
*If* early pass sales are promising (read: less awful than the 2025/2026 on-mountain data), why not provide a bit more color/commentary/numbers around units, comparison to prior years, what products are resonating, etc. etc.?
Turnarounds take time & seasonality makes progressive fixes even slower/harder to see. Added transparency & update frequency can offset this some.
It's also just a presser w/o a call, meaning it's hardly a new obligation (unlike a formal KPI) & is something that's easy to simply not publish in subsequent years if/when the stock's not so depressed (& there are not calls for a breakup/asset sales)
CHEF
Incrementally positive for Chef’s Warehouse if this:
A Suggests SYY’s focus is (still) on sheer scale
B. Ties up SYY’s attention, integration/M&A efforts, & balance sheet- preventing any sizable fine-dining deals or investments
@RyeNotBerben@atelicinvest They still have a bunch of FI calculators with front ends that are older than the average Perplexity user?
OAS1?
Also like half the mtge suite- built for a mkt that hasn’t existed since 2008.
ALIT
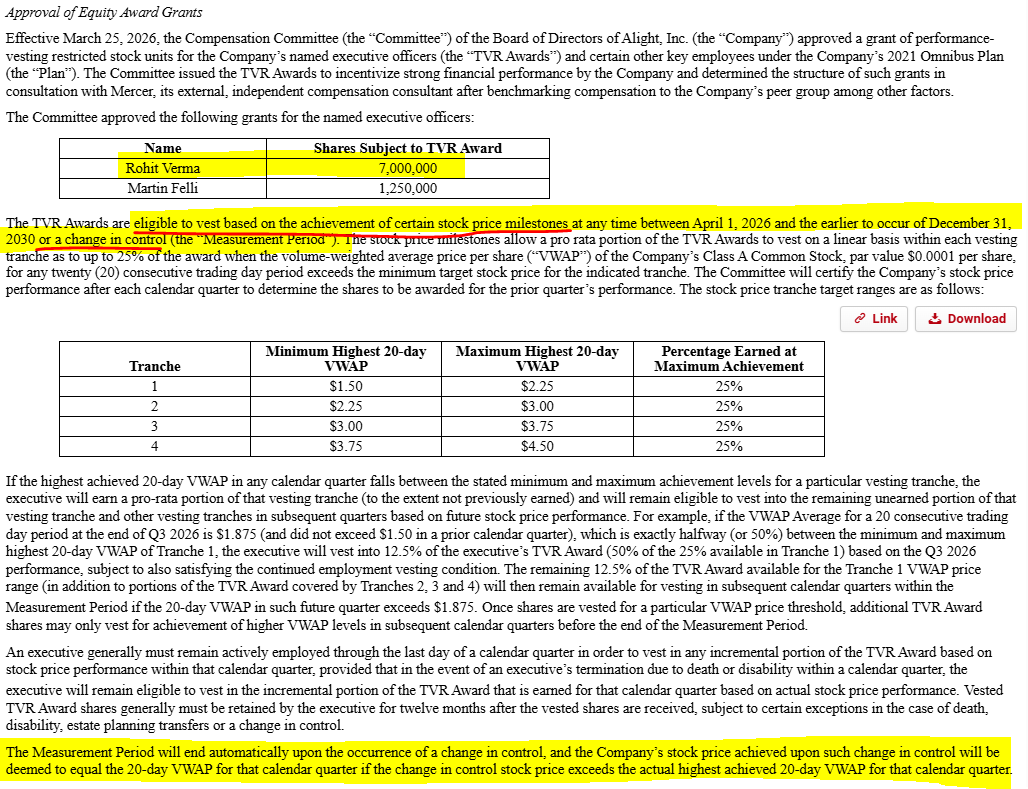
Interesting very OTM comp package:
Incentive comp tranches only begin vesting at a stock px ~3x higher than today's
At the max achievement ($4.50/share), CEO stands to make >$31M
Shareholders would also see an >8x in under 5 years so, uh, think they'd be pretty happy too.
For context, this CEO started Jan 1, his comp package value w/ the stock px at the time (excl. sign on & 1 time bonuses) was ~$5.3M/yr (@ ~$2/share)
ALIT's stock has since tanked, so his annual comp is now ~$3M (bad!)
Point being this is A. meaningful $ for the CEO & B. even at the lowest end & longest time to vest, shareholders would do well (~25% 4.5yr IRR)
Kicker: this also applies in a CiC scenario >>
e.g., CEO sells for $2.25/share?
That's ~$4M from this alone, & an all in $20M - 25M payday w/ accelerated vesting.
The bad part? Literally everything else: 3x levered busted Foley deSPAC w/ revolving exec door + declining sales & EBITDA
MMED
Tax free spin exemption period doesn’t expire until ~September ‘28 (2 yrs post split + 6mo for MDT’s planned full divestiture)
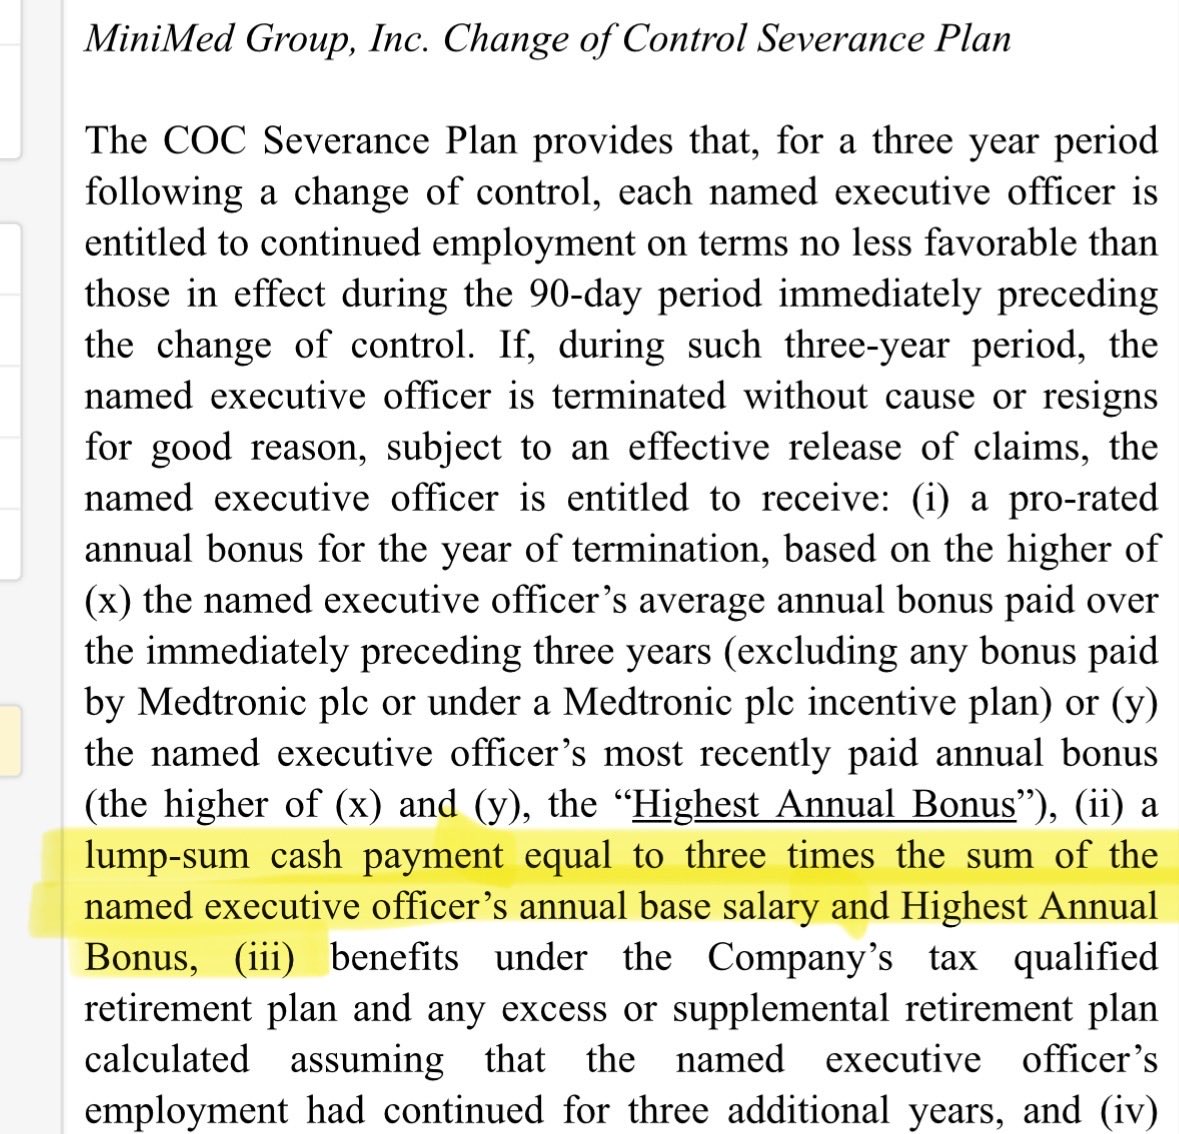
But file this away as quite generous CiC severance agreement:
3x base & bonus + prorated “highest” bonus (& for all NEOs, not just CEO)