I am heartbroken.
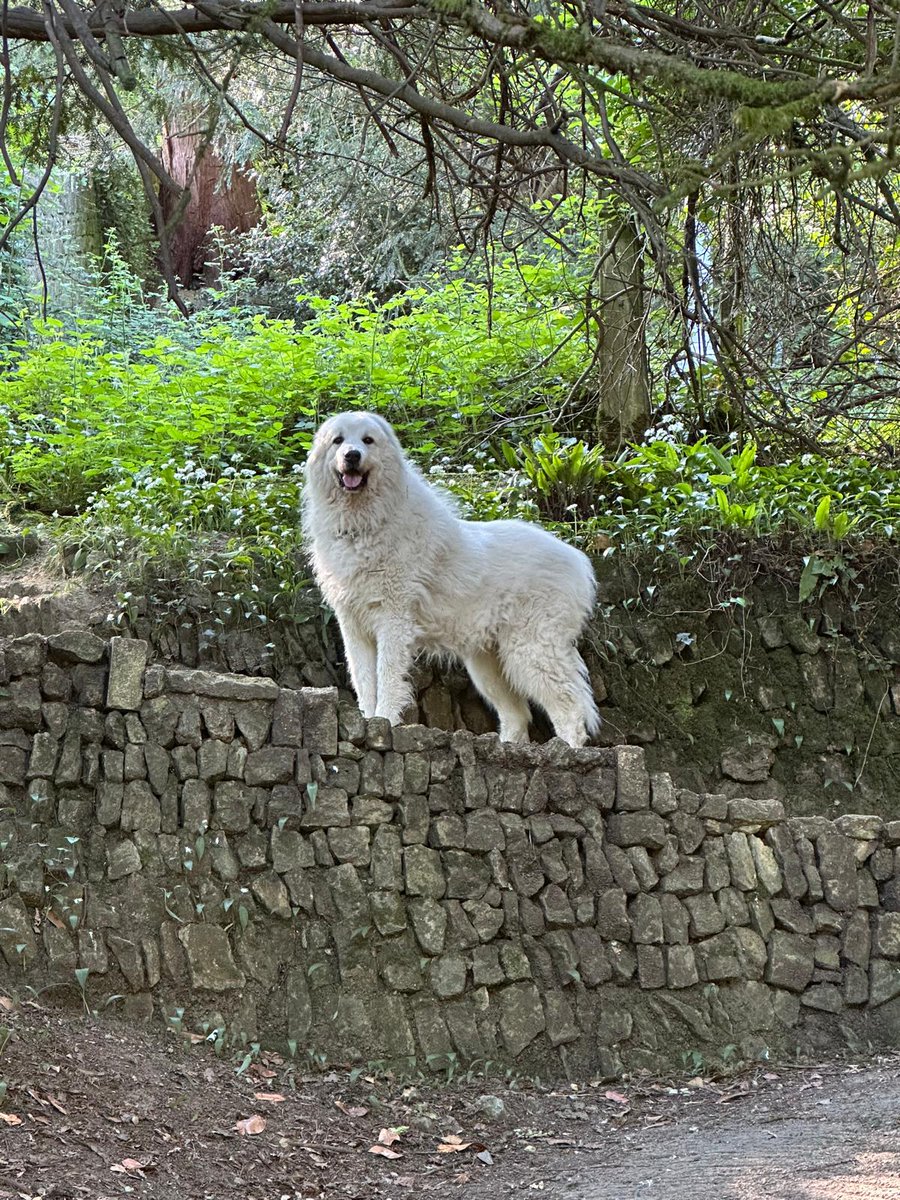
Our beautiful Achilles passed away in the early hours of Friday morning, aged nine and a half.
His health had declined rapidly in recent months, and he had been struggling to keep food down for a few weeks.
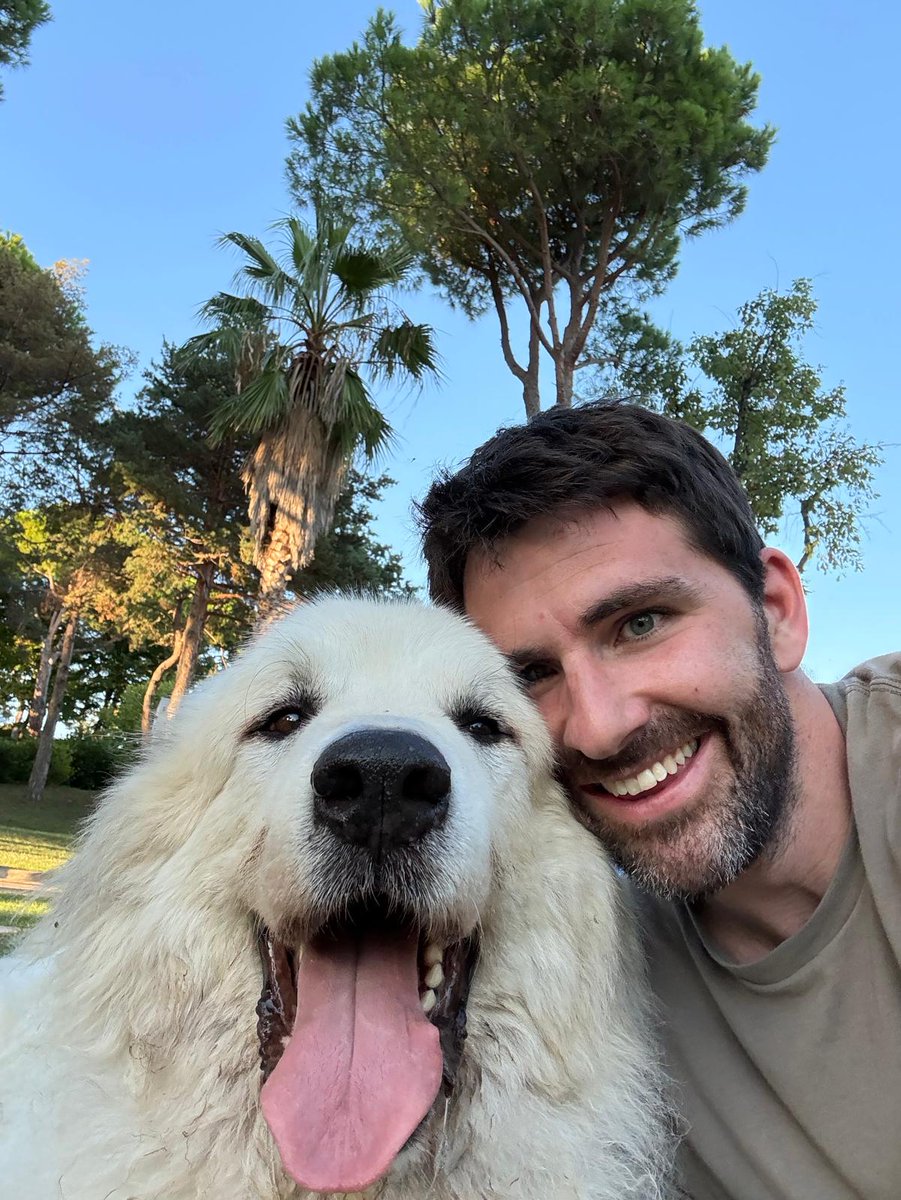
We’ve had a long family getaway to Italy booked for many months – we’re staying in the very south of the country for six weeks. So Achilles and I set off on a 3-day road trip starting at 4am on Tuesday morning from Bath, and our journey took us across England to the Channel Tunnel, and then through France, Switzerland and down the spine of Italy. We stopped many times, enjoyed the spectacular views and countryside together, and as ever I talked to him constantly. [The selfie of us below is from Wednesday night, at our second hotel (near San Marino).]
However on Thursday, Achilles’ already fragile health deteriorated even further. We got to the villa, I unpacked the car and had some time to chill out with him in the garden, and then went to pick up my wife and kids from the airport, who’d flown out that afternoon to meet us. When we all got back to the villa, he was overjoyed to see them. But then within an hour, he began spiralling. We ensured our daughter said a big goodnight and goodbye to him.
And it seemed to me that once Achilles knew that the family were reunited and the children both asleep, he could finally face the pain. It was then an agonizing few hours, before we were able to find a 24-hour vet about half an hour away, and we were able to get him in the car. An x-ray revealed his stomach was knotted and in a mess. They offered to perform surgery, but I told them to put him to sleep there and then. I was with him throughout until the very end, looking into his eyes, always talking to him.
His actions on that final night summed up his noble character. He accompanied me on our mega road trip, he fought through the pain until the family were all reunited, and then only succumbed to it after the children had gone to bed.
Achilles was born in April 2016, the very week I quit my job in the City and became a self-employed trader, working from home full time. I collected him 10 weeks later, and he’s been at my side ever since. He was with me as a single man in my late 20s – the two of us lived alone together for a long while. He witnessed me meet the gorgeous woman who would become my wife, and he was there to welcome our two children into the world with us.
One of my great friends wrote to me over the weekend that Achilles was “a colossus, in every sense” – which I think was a beautiful description.
He was a hothead in his youth, but mellowed with the passing years. Fiercely independent, but equally loyal to the family. A formidable guardian with his physical presence and immense strength, but a gentle giant who let children climb all over him.
He became a legend on Wandsworth Common for five years, then Barnes Common for three, and finally in Bathwick Meadows, in his last 18 months (and of course, all the local pubs in those areas!). It would be unusual for us to go on a walk without anyone commenting on him or stopping us to ask questions about him – his size, beauty and gentle temperament. My mother wrote to me over the weekend, “I wonder how many thousands of photos were taken of Achilles by strangers from all over the world, throughout his life?”
We have too many hilarious anecdotes of Achilles to count, but I have already started writing them all down the past three days, to share with our children one day.
There’s a huge emptiness in our lives that I cannot imagine ever being filled. I’ve lost my best friend, and our children their older brother and protector.
But through the grief, I feel such gratitude that I had the honor of raising and spending the most important decade of my life with such a magnificent soul.
Thank you for everything, Achilles. You lit up the world and brought joy to all who had the pleasure of meeting you, even seeing you from afar. I count myself blessed to have had you as my companion for so long.
Rest peacefully, my beautiful boy.
Baller of an update today from #MKA's and $CTH's joint venture, HyProMag USA:
1) Improvement in economics
Of the 1,552 tonnes per annum of NdFeB product that will be manufactured at the Texas facility, 941 tonnes (or c.61%) will be finished magnets, with the balance being co-products (swarf, etc.). This compares well to the November 2024 feasibility study (updated in March 2025), which estimated NdFeB production of 1,557 tpa, but only 750 t of that (or c.48%) being finished magnets.
As a result, the NPV of this first hub in Texas has increased by 32%, from $593m to $780m, at forecast prices.
Operating costs have crept up by 14%, to $22.3/kg; but even at current NdFeB pricing of $56.8/kg, that will still yield an EBITDA margin of c.61%.
Some context here around this margin, with regards to HyProMag's publicly listed peers.
There is only one pure-play rare earth magnet maker listed on Western exchanges, namely USA Rare Earth $USAR. In its Registration Statement filed in February this year, it included forecasts for its proposed Stillwater magnet production facility. See image attached.
For 2027, its implied gross selling price for NdFeB magnets is $185.3/kg. Its cost of sales is $113.1/kg.
Today, HyProMag USA has stated that its all-in-sustaining cost for a kilogram of NdFeB product is $22.3/kg.
Even at a lowly selling price of $57/kg, it'd be making an EBITDA margin of >60%.
The quality of these two plants under development are simply incomparable. HyProMag's Texas facility completely destroys USAR's Stillwater plant, on every financial metric.
The reason for this is due to HyProMag having exceptionally low cost feedstock, owing to its patented recycling technology. [USAR has no recycling tech to speak of and therefore must buy its input materials from conventional upstream sources - at least until its greenfield deposit is brought online.]
Which brings us onto the second key item of MKA's update today:
2) Strategic review to explore US listing
HyProMag USA is now exploring going for a US listing.
This is hugely positive news for MKA and CTH shareholders.
USAR listed on NASDAQ earlier this year at a valuation of almost $900m. Its mkt cap has risen to $2.3bn (and spiked to almost $5bn, jus two months ago).
HyProMag USA has repeatedly stated that it could build and operate as many as 6-7 of its magnet recycling / remanufacturing hubs across the USA. Today, we now know that just one of these hubs commands an NPV of $780m.
As a direct competitor to HyProMag USA, USAR's significant mkt cap will play a key role in driving HyProMag's valuation (both in the advisers' pre-listing work and pitching to investors; and latterly with the investment community, once the stock listed).
I had personally envisaged all of the HyProMag group companies being consolidated under one roof and then listed as one business on NASDAQ; but now I see that the strategy announced today could build greater value for shareholders.
It's reasonable to assume that due to far superior margins, unique access to input materials, and national scalability, HyProMag USA will eventually enjoy a higher mkt cap than USAR.
MKA will retain a c.80% equity interest in the non-US HyProMag business "in-house". In the long-term, this could eventually be a global business with a dozen hubs spread across 6-7 nations.
Were HyP USA to command a sky-high mkt cap on NASDAQ, then the larger, ex-US business (under the MKA roof) would also more likely enjoy a much loftier valuation through the clear read-across.
......
By next Christmas, MKA could own a 70-80% equity stake in NASDAQ-listed $MKAR; and a 30-35% stake in NASDAQ-listed HyProMag USA. It's simple to see that - given the very punchy valuations enjoyed by the rare earths peer group listed in the US - those combined equity stakes could be valued at in excess of $1bn, $1.5bn, possibly even $2bn.
That would enable MKA to rapidly build the ex-US HyProMag business worldwide, with very significant financial firepower behind it.
The UK market has once again not appreciated the importance of MKA's RNS today. It will, eventually...!
Another milestone for @MkangoResources#MKA, in HyProMag USA securing a long-term lease for its first magnet recycling / remanufacturing site.
This will be a significant operation: the most up-to-date numbers in the public domain suggest that this first facility in Dallas-Fort Worth, Texas, will produce 1,557 tonnes per annum of NdFeB magnets and associated products, for 40 years.
The forecast average selling price across the period is estimated to be $95/kg, and the average EBITDA margin, 66%.
That points to EBITDA of $98m per annum on revenue $148m pa.
The NPV for this single plant is estimated to be in the region of $650m, although management has stated that an updated (and upgraded) NPV is likely to be announced in the (very) near term.
Mkango also reiterates today that they are still targeting commissioning of this first plant in mid-2027.
HyProMag is presently carrying out a scoping study to build two more very similar plants in Nevada and South Carolina; and has repeated its bullish long-term aim of eventually having 6 or 7 of these plants operating across the USA.
Capex for the first plant in Texas is presently estimated to be $132m, of which $92m, or c.70%, has already been (practically) secured in the form of a Letter of Interest from the US Governments' EXIM Bank to provide a low cost loan for that amount.
Mkango's c.40% share of HyProMag USA's first plant in Texas is $260m, or 56p per share. This isn't a greenfield deposit in some far-flung corner of the world, but an infrastructure project on US soil that happens to be of vital importance in the now multiple geopolitical battles ongoing between the US, China, Japan and the EU.
Rare earth permanent magnets are the lifeblood of the future economy. All of the reasonably-advanced rare earth deposits in the word - if brought into production - could still not meet the NdPr and DyTb demand for the bull case scenario of humanoid robot global rollout over the next 2-3 decades.
Low cost recycling of NdFeB magnets is therefore an absolute requisite for said future economy.
HyProMag is the lowest cost technology. The global leader in magnet recycling.
As such, I believe that Mkango should already be trading at >75% of the NPV of the proposed HyProMag plants. It is incredibly difficult to imagine a scenario in which these facilities are not developed and constructed at rapid pace - not just across the US, but also in Europe and Asia (and possibly further down the line in Central and South America, and Africa).
Bear in mind that Mkango also already has majority ownership (currently 80%) of a smaller HyProMag plant now operating in the UK, and 72% of a plant coming online in Germany next quarter.
And of course, it is listing its upstream assets (the Songwe Hill rare earths mine and Pulawy separation plant) on Nasdaq next quarter, at a valuation of circa 86p per MKA share.
Mkango's closest peer - USA Rare Earth $USAR - currently trades on NASDAQ with a mkt cap $2.3bn. Its assets are inferior to Mkango's on almost every metric.
The valuation disconnect and investment opp. are so incredibly clear; and the near-term catalysts to wake the market from its slumber, very many.
All IMO, DYOR, etc.
https://t.co/fPhiw9uk5r
TRUMP ADMINISTRATION SHIFTS FOCUS TO ROBOTICS
Yet another powerful tailwind for the rare earths industry, given that there are 2-4 kg of NdFeB magnets in each humanoid robot.
Magnet makers - $MP $USAR #MKA $MKA.v $CTH $NEO being the only options listed on ex-China exchanges - should be one of the top pick-and-shovel plays for this potentially world-changing nascent industry.
@MylesMcNulty I share my real-time TRADE alert (entry & exit points) on WhatsApp, free to join ✅
➡️Copy search input Reply “555” to WhatsApp: +13024879995
Here’s the link:https://t.co/xVbTPWjaBX