US CPI in one hour. Derive's 13 Nov $BTC options price a move of about ±2.9% by Friday. The straddle math around CPI broken down:
Long the BTC $74K call and put, 13 Nov expiry
Cost: ~$2.1K per BTC (40.7% IV)
Break-evens: $71.9K / $76.1K
Max loss: the premium, if BTC settles at $74K
24h after the print, per 1 BTC:
Flat, IV unchanged: −$0.4K
Flat, IV down 5 pts: −$0.6K
±2%: −$0.4K to +$0.1K
±4%: +$0.7K to +$1.2K
A 2% reaction barely covers the decay. The straddle needs something closer to 4%, and fast.
Skew leans cautious: 25-delta puts on the 13 Nov expiry trade about 6 vol points over 25-delta calls. The market is paying up for downside protection into the number.
ℹ️ Black-Scholes estimates from Derive's live surface, not quotes. Not financial advice.
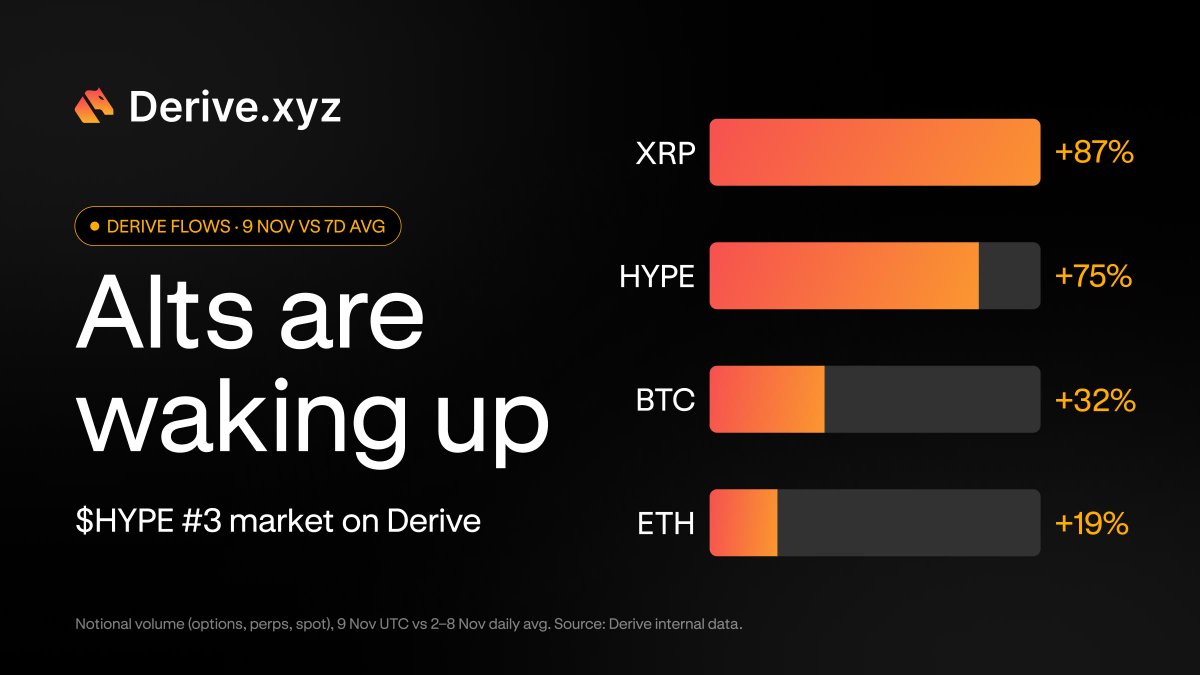
Alt options are waking up on Derive.
XRP volume +87% vs its 7-day average. $HYPE +75%, now our #3 market after BTC and ETH.
SOL saw +20k Nov 27 $90 calls sold, +2.7m notional, and just starting.