@luigidemeo They're both counterparty risk but would be priced differently
Medium to long term, I think issuer-sponsored will be the dominant model. Layering additional broker/intermediary risk doesn’t feel like the right foundation for this next era of capital markets
@luigidemeo Sure but not in the same way
Normal US brokerage accounts hold securities for you within a regulated custody framework. SIPC also provides some protection against missing customer securities/cash if issuers fail
I’ve been yelling this into the void for months.
Most tokenized “stocks” are hopium and hot air. They are not the shares. They are not issued by the company. They are not redeemable for the actual equity.
You do not own $AMC, you do not vote, you do not get a claim on the business.
You bought economic exposure from an offshore affiliate that slapped someone else’s ticker on a derivative and hoped nobody would read the fine print.
That is NOT tokenization. That is selling people a wrapper of snake juice.
This is the collision I said was coming the second platforms started minting US equities without the issuer in the room, but legal is no fun so no one really listens.
If it isn’t the stock, can’t be redeemed for the stock, and the company is publicly furious it exists… you did not buy $AMC. You bought nothing with a logo on it.
This is going to be a windfall.
Tokenized stocks are the future, but this industry loves making its own job harder
You don't convince issuers or TradFi to upgrade to new windows by throwing bricks through the old ones
imo slower pace is fine
The worst outcome is an intermediary tokenizes securities without issuer buy-in, blowing up, and setting the space back by a decade (FTX but for RWAs)
fwiw I don't think it'll take decades since transfer agents are already moving (Computershare via Securitize and Equiniti). We now need a catalyst for shareholders to move their holdings
Largely agree. The caveat is the claim that blockchain removes counterparty risk
To actually do that with netting, everyone must pre-fund a smart contract with their max exposure for the period, which is a massive capital cost
If you don't pre-fund, counterparty risk returns. And the moment that risk is back, you'll need something like an NSCC for tokenized securities
@jserna@Securitize@DouroLabs@FINRA Moving to T+0 is not a tech problem though. As your letter states in a footnote, DTC can do T+0
The challenge is market resistance due to higher costs—like the capital cost of fully collateralized trading and loss of netting
@brxckinridge Even with a broker, prediction markets are all-or-nothing. Outcomes can flip instantly, so solvent brokers will demand full cash upfront
Hedge funds can lower collateral by balancing opposite trades. A small business hedging a single risk won't get those discounts
As on-ramp friction disappears, DeFi yields will have to compete directly with TradFi risk-adjusted rates
Non-US capital has a different calculus, but for anyone with access to US markets, the case for DeFi yields just isn't there imo
Maybe that changes when risk-free rates drop again
How much of that $30B is US capital with TradFi access?
Agreed you won’t get full bond yields if you exit early due to rate risk. But Aave carries credit risk (bad debt) alongside smart contract risk. A 6-year track record doesn't eliminate tail risk, as we saw with rsETH
Not a knock on Aave, but taking on layered risk for yield that merely matches the risk-free rate and trails AAA corporate debt is a tough trade-off
If you have access to US markets, earning dollar yield in DeFi makes no sense
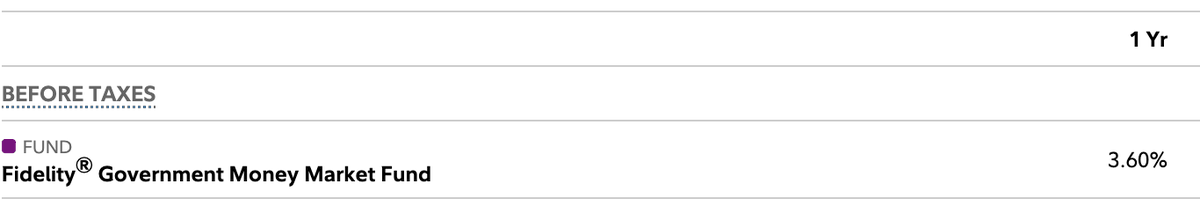
Over the past year, Aave on Ethereum paid 3.68% on USDC. Fidelity’s SPAXX fund paid 3.60% over the exact same period
@luigidemeo Fair point. But even setting aside the risk-free rate, DeFi yields sit below AAA corporate bonds (5.76% today, 2.14% in 2020)
I’m not sure what the exact DeFi premium should be, but no rational US allocator would take on smart contract risk to earn less than safe corporate debt
I’m not sure why some stablecoin advocates compare stablecoin yields to bank savings accounts. The proper benchmark would be a money market fund in an insured brokerage account
An extra 0.08% yield is a terrible trade-off for smart contract risk
Strange flex for a federal exchange
Kalshi prints no money. If New York gained $200 million, traders in the other 49 states lost $200 million
By your own logic, why shouldn't every other state ban you?
Kalshi CEO Tarek Mansour: "Well you're going to have a lot of pissed off New Yorkers if we got shut down in New York."
New Yorkers have made $200 million trading on Kalshi. That's impossible on a sportsbook, where the house always wins, and they ban the winners.
LATEST: An industry group for transfer agents is urging the SEC to favor issuer-sponsored tokenized shares over third-party stock tokens as it writes rules for moving U.S. equities onto blockchains.
Read the full piece by @sndr_krisztian on CoinDesk
I don't buy this prediction market hedge argument
Risking $10M to make $10M if the Clarity Act doesn't pass is just a 2x payout
If you actually want to hedge a crypto downside, IBIT puts give you much higher leverage for a fraction of the capital
The firm that bet $10M against the Clarity Act actually wants it to pass.
Galaxy's Gil Wassermann on how @arca used a prediction market to hedge their crypto portfolio against the risk of Clarity failing.