Why do retirees own bonds if stocks have delivered higher long-term returns?
Consider a retiree who stepped away in 2000 with an all-stock portfolio and a standard 4% annual withdrawal rate. Because the market suffered declines early on (the market dropped in 2000, 2001 and 2002), that retiree would have been forced into selling into a declining market. The result: The portfolio would have been depleted to nearly zero within 25 years. At a 4.5% withdrawal rate, the funds ran out in 20 years.
Outside of 1929, 1969, and 2000, an all-stock portfolio succeeded in 91% of rolling 25-year periods.
But, in my view, retirees hold bonds precisely because they cannot afford to gamble on being in the unlucky 9%.
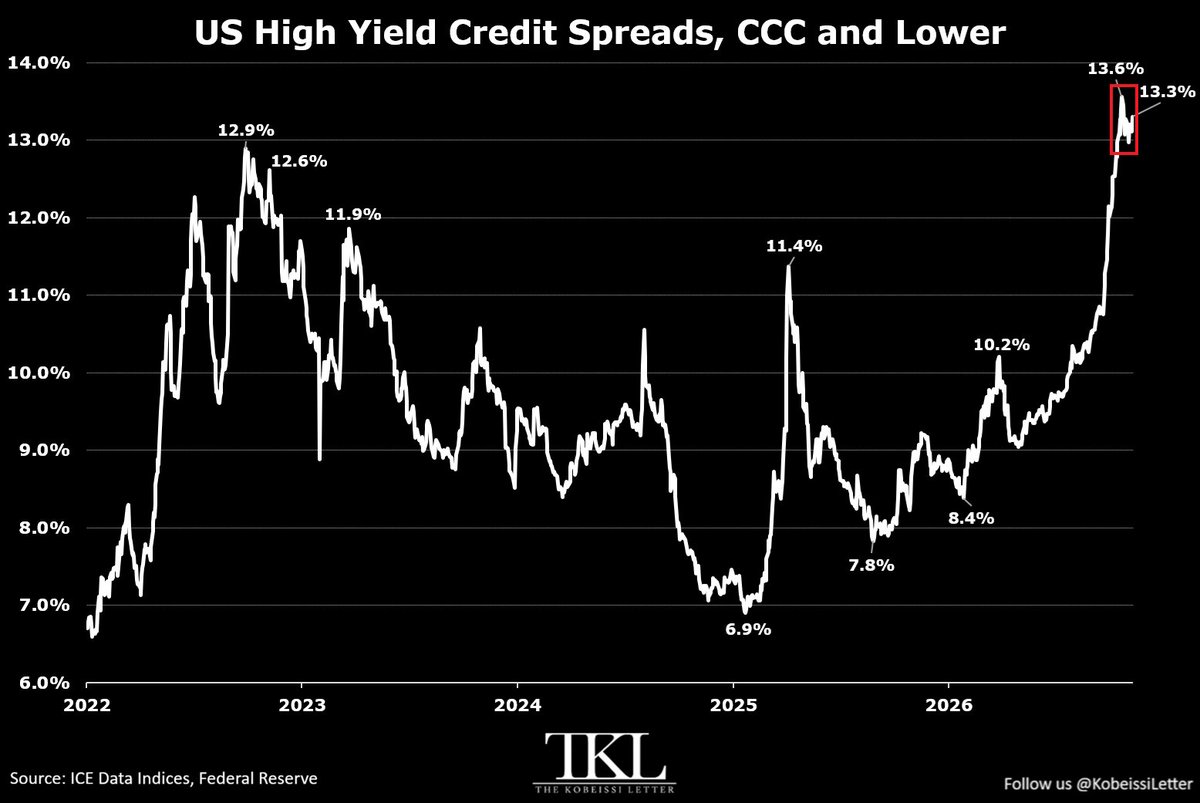
US credit stress is intensifying among the weakest-quality borrowers:
Spreads on CCC-rated and lower US corporate bonds are up to 13.3%, near the highest since the 2020 pandemic.
Since January 2026, this figure has surged +490 basis points.
As a result, these spreads have now surpassed the 2022 bear market peak of 12.9%.
For perspective, during the 2020 February-March surge, this metric peaked at 18.8%.
Meanwhile, the spread differential between CCC- and BBB-rated corporate debt has widened to ~1,200 basis points, its widest level in at least 5 years.
This means investors are demanding ~12 percentage points more in compensation to hold the lowest-rated debt rather than first-notch investment-grade corporate bonds.
Cracks are spreading quickly through the lowest-quality credit.
Thanks to a deposit-insurance scheme, more than 1.8m people have begun getting their money back after Ueno’s collapse. But the impact on Paraguay’s economy will take time to become clear https://t.co/PCc5vZDsW1
About half of U.S. college students who have taken one econ course never take another one. Should introductory economics focus on math-heavy models — or on how core concepts can help students understand the world? A blog post including insights from educators and other experts explores the question #EconEdMonth #TeachEcon https://t.co/GtjUeftjqP
Do you know these inflation terms: headline, core, trend, median, trimmed mean and sticky price? Visit the FRED Blog to be sure https://t.co/vrQi0zLEvk
Last weekend, I read Domar’s classic 1944 paper “The ‘Burden of the Debt’ and the National Income.”
As is often the case, I was familiar with the basic result by the time I was an undergrad: you can run a permanent government deficit and still keep the public debt-to-output ratio constant under certain conditions on the real interest rate, the economy’s real growth rate, and the primary surplus. In fact, you can even reduce the public debt-to-output ratio asymptotically to zero and still run a government deficit every year.
But I had never read the original paper. The language is often difficult to follow (yes, leaving the formal model in the appendix makes everything much harder; you’ve got to love math!). Yet the insight per paragraph is truly outstanding. Domar was an incredible economist.
Nowadays, I spend most of my days thinking about how public debt interacts with AI and fertility. Both forces put the fiscal path of many Western European countries in a very difficult position: AI will push up the real interest rate more than the growth rate, and falling fertility will lower the growth rate. In Domar’s terms, the gap between the real interest rate and the growth rate moves in the wrong direction. I truly do not see how France or Spain can avoid a debt crisis over the next decade unless they undertake serious reforms.
To wrap up: read Domar’s 1970 paper “The Causes of Slavery or Serfdom: A Hypothesis” as well. That is a heck of a paper, a true classic. Someone should write a scholarly study of Domar as an economist. If you are working on the history of economic thought and searching for a topic, Domar is low-hanging fruit.
Anthropic retracts
According to Reuters, the AI company first sent a copy of a filing that showed Anthropic aimed to sell about 867 million shares in a price range of $70 to $80 per share, then followed up with an email saying details about the pricing were inaccurate.
Anthropic in the second email said it would update the filing later.
There is now a record $1.3 trillion in total credit card debt in the US - at an average interest rate of 21%. This is the #1 wealth killer in America by a landslide.
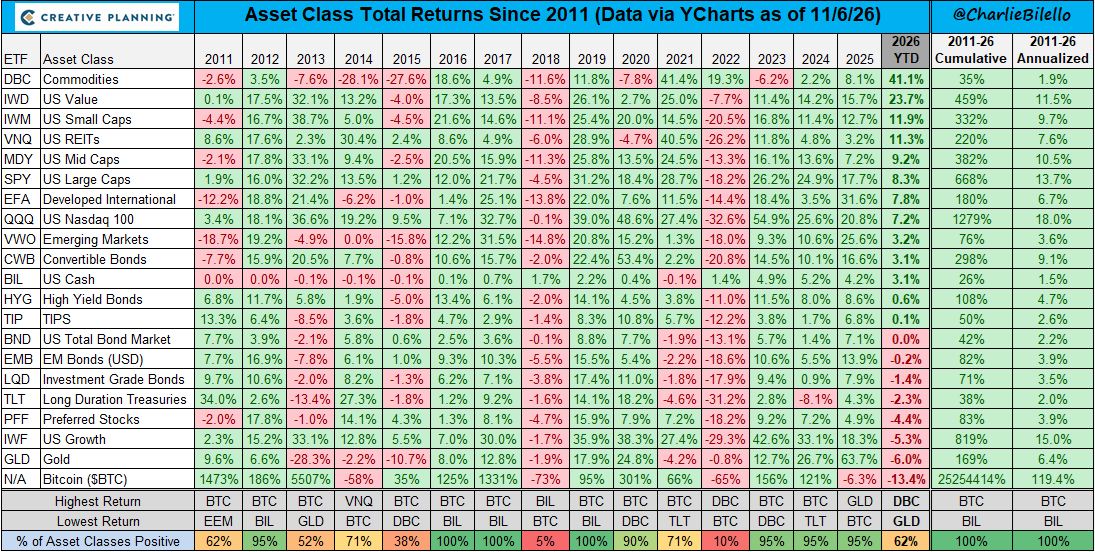
Bitcoin (-13%) and Gold (-6%) are the two worst performing major assets so far in 2026. This is something we haven't seen before in any calendar year.
https://t.co/l5IYmkf6Ih