My projected annual dividend income (PADI) is currently at $89,693.85. 💰
That’s $7,474 a month in dividends without selling a single share.
But here’s something I will NEVER neglect while building passive income…
GROWTH.
Chasing the highest yields can absolutely crush your portfolio. A 12% yield means nothing if your investment loses 30% of its value.
I want dividend growth, capital appreciation, AND consistent income.
Then I layer options premiums on top to accelerate the entire process.
Dividends + Growth + Options = Financial Freedom.
That’s the system. And it works.
Happy Dividend Day! 💰
$TXN and $AXP just dropped another $156.75 into my account this morning!
Two quality companies that I’m happy to own for the long haul.
They grow their businesses, increase their dividends, and pay me just for being a shareholder.
No selling shares. No timing the market. Just ownership turning into income.
This is how you build a dividend snowball! 🚀
Next release ✨
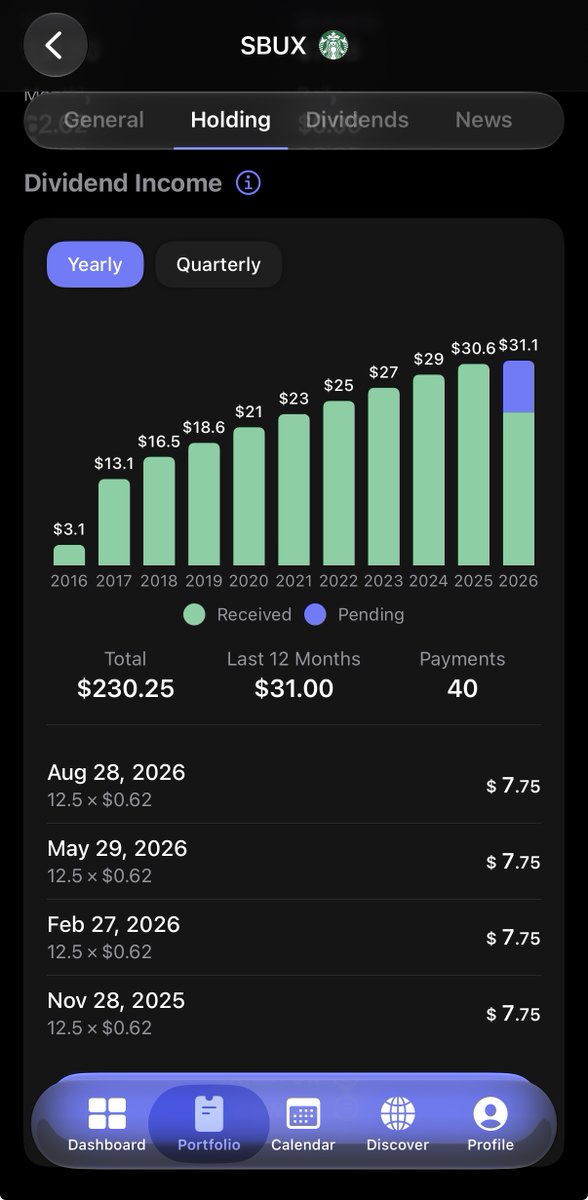
Open a holding and see the dividends it has paid you.
Yearly or quarterly 📊 This year’s bar stacks what you’ve already received with what’s still pending or estimated.
#dividends#divtracker
So what does the portfolio that helped me retire at 40 actually look like? 👀💰
I just shared my $83K annual dividend breakdown…
Now let’s look UNDER THE HOOD! 🔥
🚀 GROWTH
$SPY, $QQQ, $SCHG, $PLTR
🌎 INTERNATIONAL
$SCHF, $OVF
💰 DIVIDEND GROWTH
$SCHD
💵 INCOME GENERATION
$SPYI, $QQQI, $GPIX, $GPIQ, $IWMI, $OVL
🛡️ DEFENSIVE
$SGOV, $JPC
My strategy is SIMPLE:
📈 Growth builds tomorrow’s wealth.
💵 Income funds today’s lifestyle.
🌎 International exposure diversifies my investments.
🛡️ Defensive holdings help weather market volatility.
The portfolio yield me enough to enjoy financial freedom TODAY.
And keeps building wealth for an even better tomorrow!
That’s how I approach early retirement. 📈🌴🍺
It’s been a LONG time since I shared a dividend update! 💰
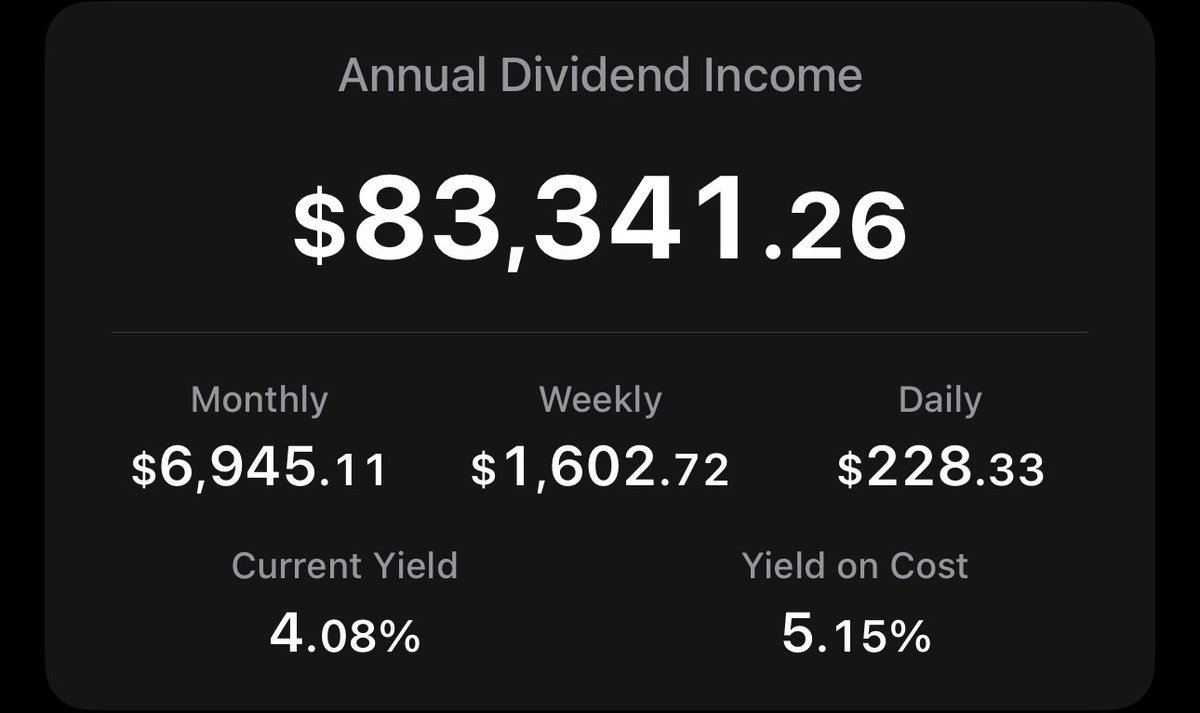
Here’s what the dividends that helped me RETIRE AT 40 look like today!
📈 $83,341 annually
💵 $6,945 monthly
📅 $1,603 weekly
🔥 4.08% portfolio yield
And here’s what might surprise you…
Most of my portfolio is STILL focused on GROWTH!
A couple of years before retiring, I started building an income sleeve to generate cash flow WITHOUT selling shares.
Today, dividends, interests and REIT income fund my lifestyle.
Options trading? That’s just the TURBOCHARGER! 🚀
It accelerates wealth building, but my retirement doesn’t depend on it.
Meanwhile, my growth investments keep compounding!
So what does a portfolio that helped me RETIRE AT 40 and now generates $83K in annual dividends look like?
I’ll show you NEXT! 👀📈🌴🍺
My Roth IRA investment strategy is centered around one objective: building long-term wealth through a combination of capital appreciation and sustainable dividend growth. 📈
I’m strategically blending high-quality dividend stocks and ETFs like $SCHD and $MO with growth-oriented investments such as $NVDA, $META, $TSM, $QQQ, and $FIX.
The goal is to create a portfolio where growth investments drive capital appreciation while dividend-paying holdings provide income, reinvestment opportunities, and long-term compounding potential.
I’m not chasing the highest yields or trying to predict every market movement. I’m focused on owning quality businesses, maintaining exposure to innovative industries, and allowing time and compounding to do the heavy lifting.
With retirement still years away, I believe there’s tremendous value in balancing aggressive growth opportunities with established dividend-paying investments.
Growth builds wealth. Dividends help compound it. Patience allows both strategies to work together.
Investing is a marathon, not a sprint.💰
Happy $O and $MAIN dividend day!
In an uncertain market, there’s something beautiful about seeing those monthly dividends continue to hit.
$O: $214.48
$MAIN: $77.00
That’s $291.48 in income without selling a single share.
Markets will go up. Markets will go down. The dividends keep coming.
This is why I love building multiple streams of income.
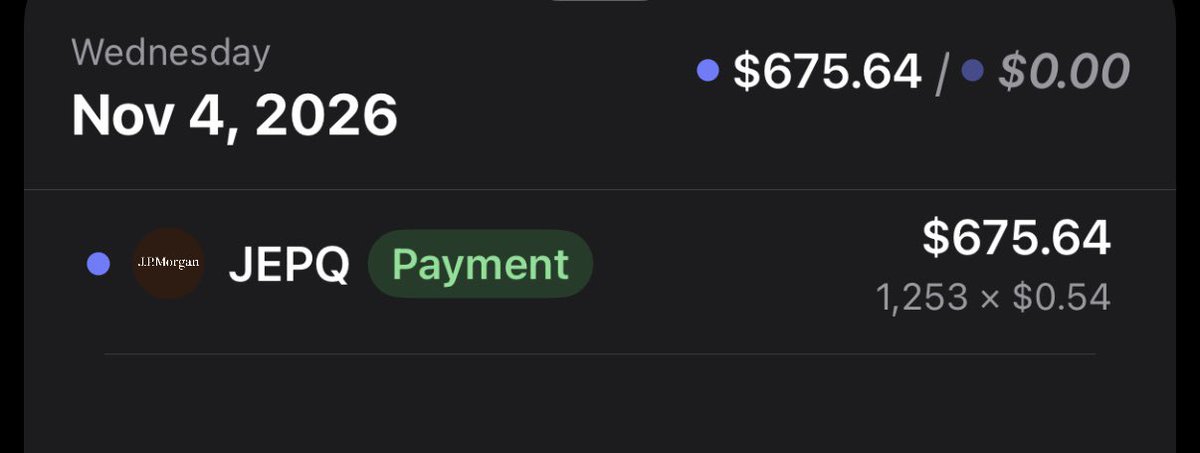
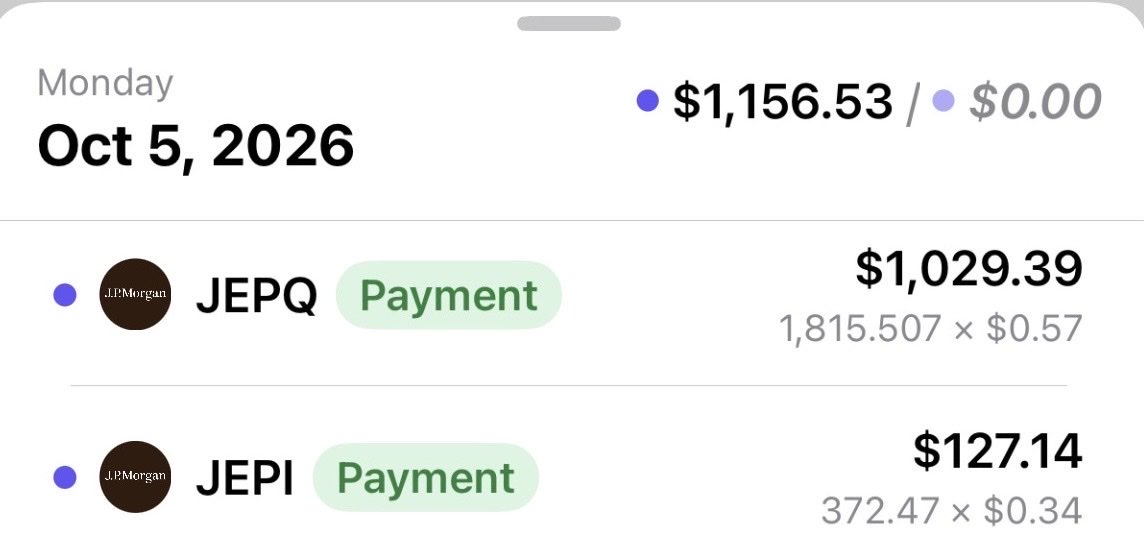
Happy $JEPI and $JEPQ dividend day!
$JEPQ: $1,029.39
$JEPI: $127.14
$1,156.53 hitting the account today.
And every dollar is getting DRIP’d right back into more shares.
Buy assets.
Collect income.
Reinvest the income.
Let the snowball keep growing.
What a way to finish off the month.
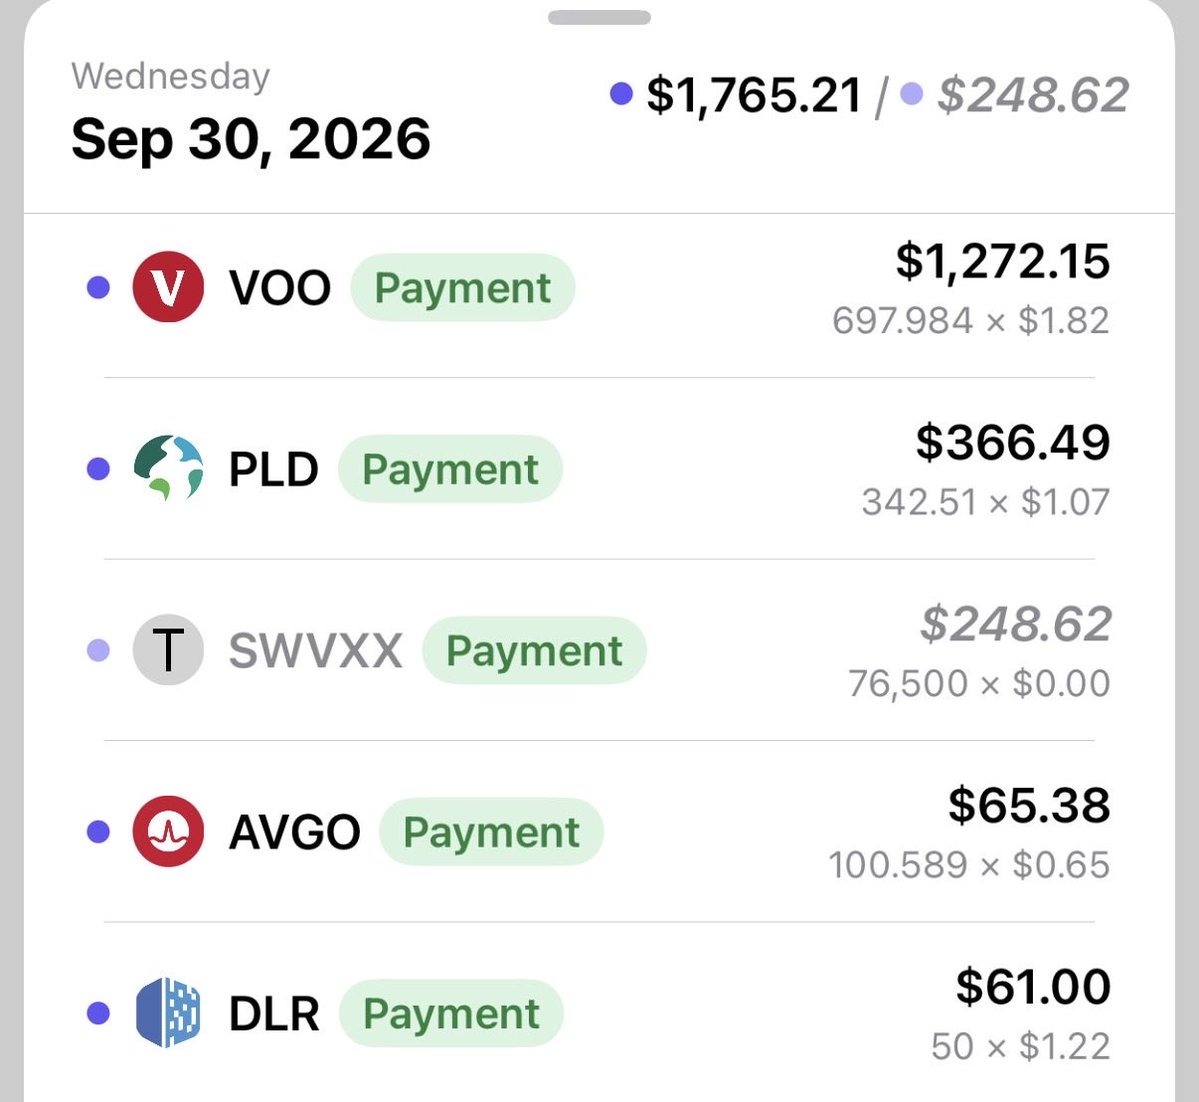
Over $2,000 in dividends and distributions hitting the account today:
$VOO: $1,272.15
$PLD: $366.49
$SWVXX: $248.62
$AVGO: $65.38
$DLR: $61.00
Total: $2,013.64
Led by $VOO, my favorite ETF, with over $1,270 by itself.
And this officially caps off an $11,000+ dividend month.
No selling shares. No extra work. Just owning assets, collecting income and letting it compound.
Dividends + options income continue to fund a life I once thought was impossible.
I set a goal this year to reach $100,000 in annual dividend income.
I started January at $79,935.
Today I’m at $94,627.
That’s now $7,885 per month. $1,820 per week. $259 per day.
That $259 per day is powerful because it comes whether I’m golfing, spending time with my family, sleeping, or doing absolutely nothing.
The goal isn’t to chase the highest yield possible just to hit $100K. I’m focused on growth and sustainable yields so my income doesn’t come at the expense of the long term health of my portfolio.
Dividend growth increases the income. Options income funds more shares. Those shares create more dividends. Then I repeat.
10 years ago I never imagined dividends and options income could fund a life where I don’t have to go to work.
That’s financial freedom.
$5,373 to go
In 2022, I was making around $2,500 a year in dividends.
That was it.
Then I decided I wanted to build a real passive income machine.
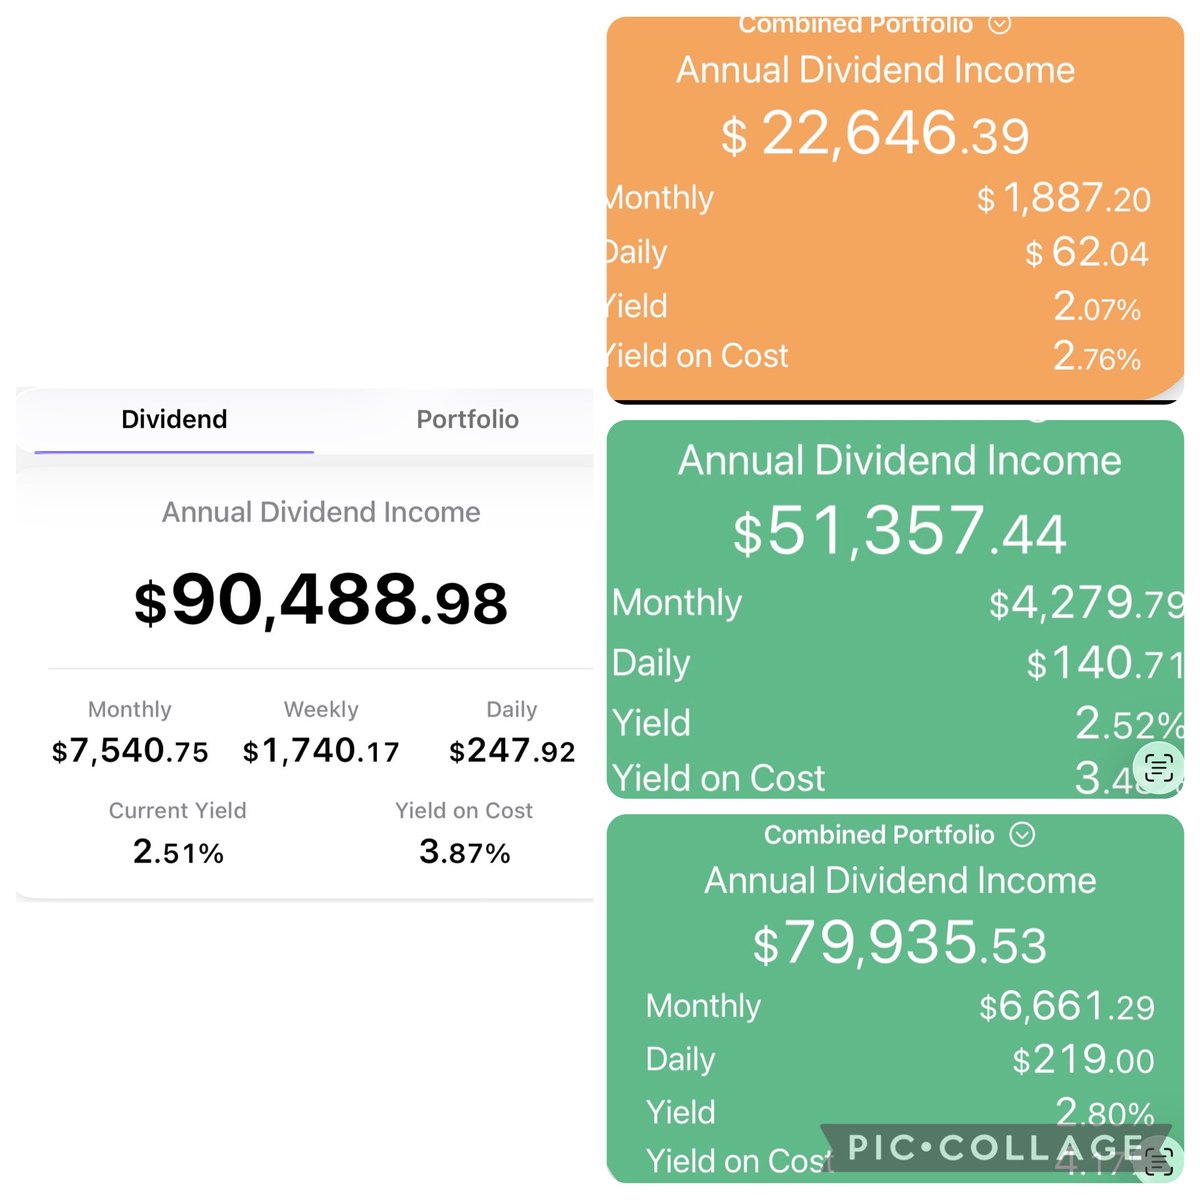
January 2023: $22,646/year
January 2024: $51,357/year
January 2026: $79,935/year
Today: $90,488/year
There was no magic get rich quick strategy.
No chasing ridiculous yields. No high yield bullshit. No shortcut.
It started small. I kept investing. I kept reinvesting. I kept adding. And slowly, the snowball started doing more and more of the work for me.
Now it generates over $7,500 a month without me having to clock in for it.
But the biggest point isn’t my number.
Don’t compare your Chapter 2 to someone else’s Chapter 20.
If you’re making $500 a year right now, build it to $1,000. Then $2,500. Then $5,000.
Your only competition is the number you had last year.
Keep building. The snowball doesn’t care where you started.
Happy Dividend Day 💰
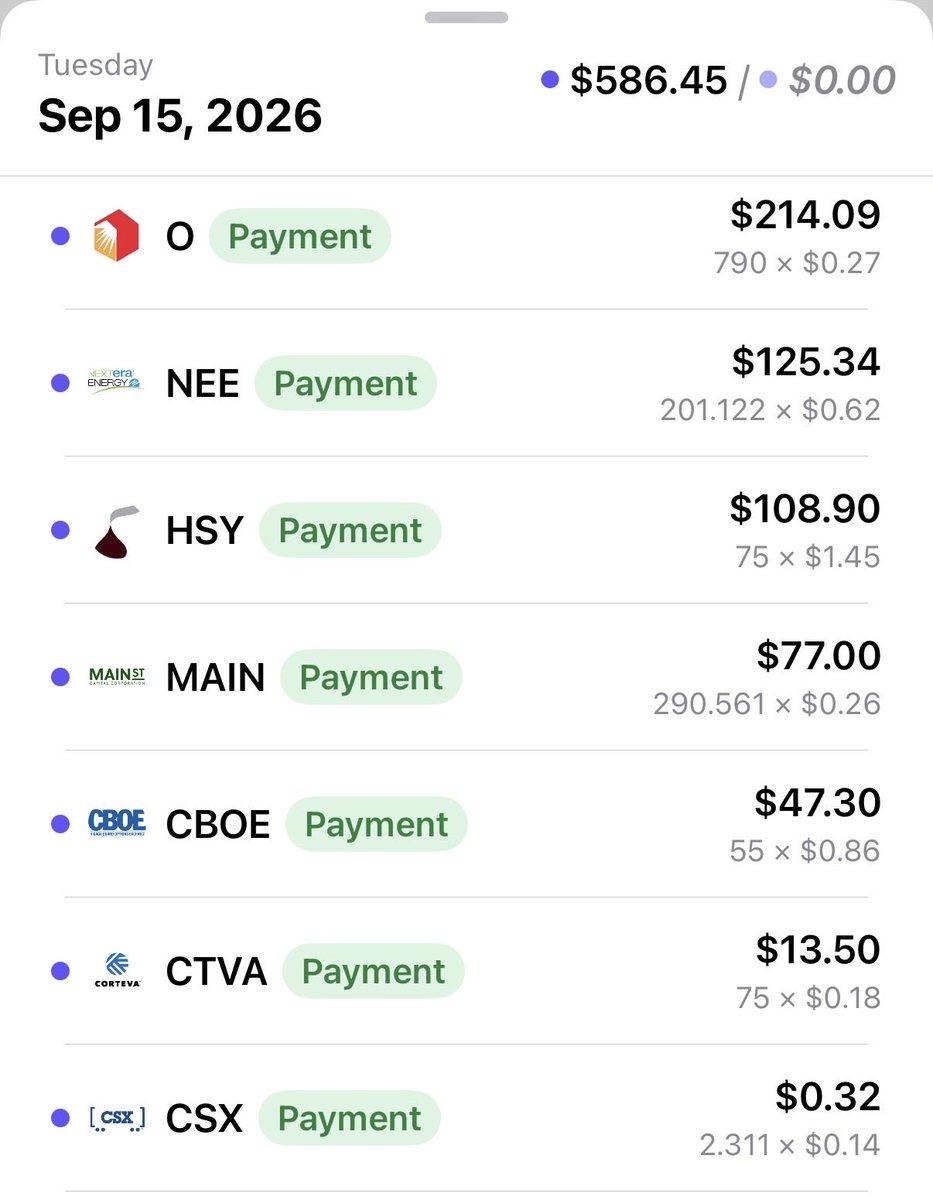
$586.45 hitting the account today for doing absolutely nothing.
$O: $214.09
$NEE: $125.34
$HSY: $108.90
$MAIN: $77.00
$CBOE: $47.30
$CTVA: $13.50
$CSX: $0.32
This is why I love dividends.
Buy great companies.
Hold them.
Reinvest the dividends.
Let the income compound.
Eventually, your money starts working harder than you do.
Dividend Milestone Unlocked! 💰📈
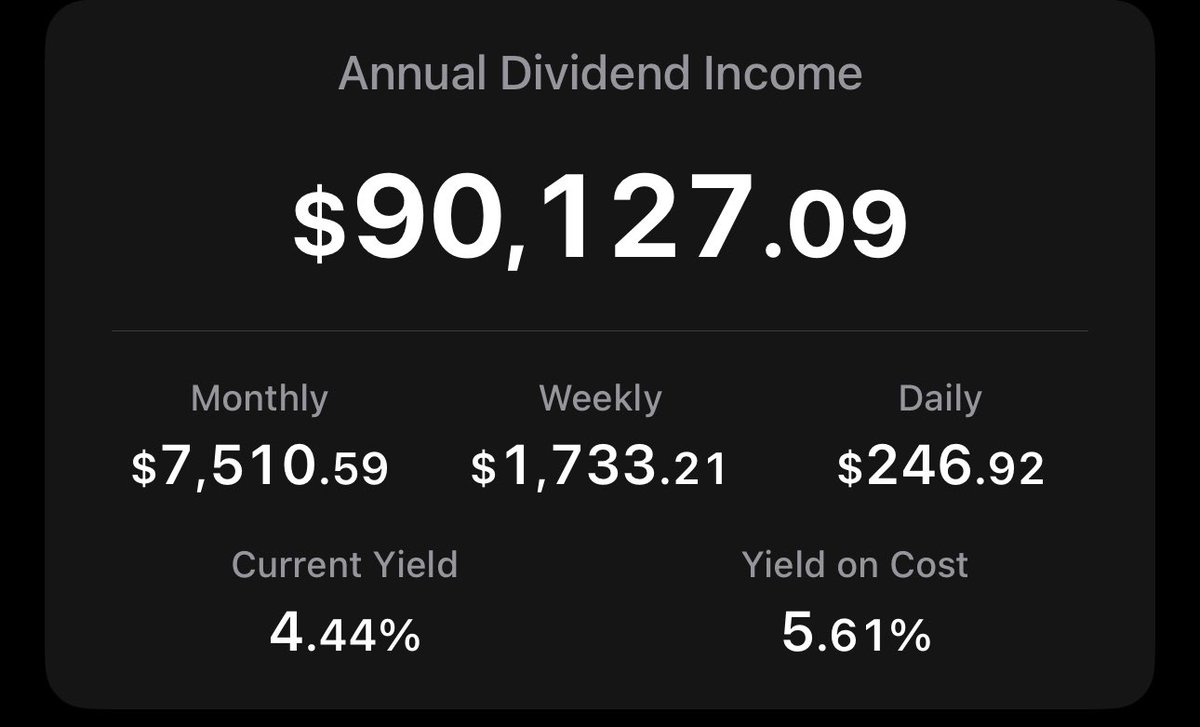
$90,127 in projected annual dividend income.
I publicly set a goal of reaching $100,000/year in dividends…
And we’re officially 90% of the way there. 🎯
That’s now:
💰 $7,511/month
💰 $1,733/week
💰 $247/day
And I’m still adding shares every single week.
I’m not interested in chasing yield just to hit the number faster. I want to keep balancing income with long-term portfolio growth.
Next stop:
$100,000/year. 💯
Less than $10K to go.
The income engine keeps rolling. 📈🌴🍺
☀️ Sunday Morning Portfolio Update ⛏️📈
My mini portfolio hit a high around $72K this year and is currently sitting at $69,203.
YTD: +21.14% | +$12,077 🟢
Hard to believe this journey started 4 years ago with just $550.
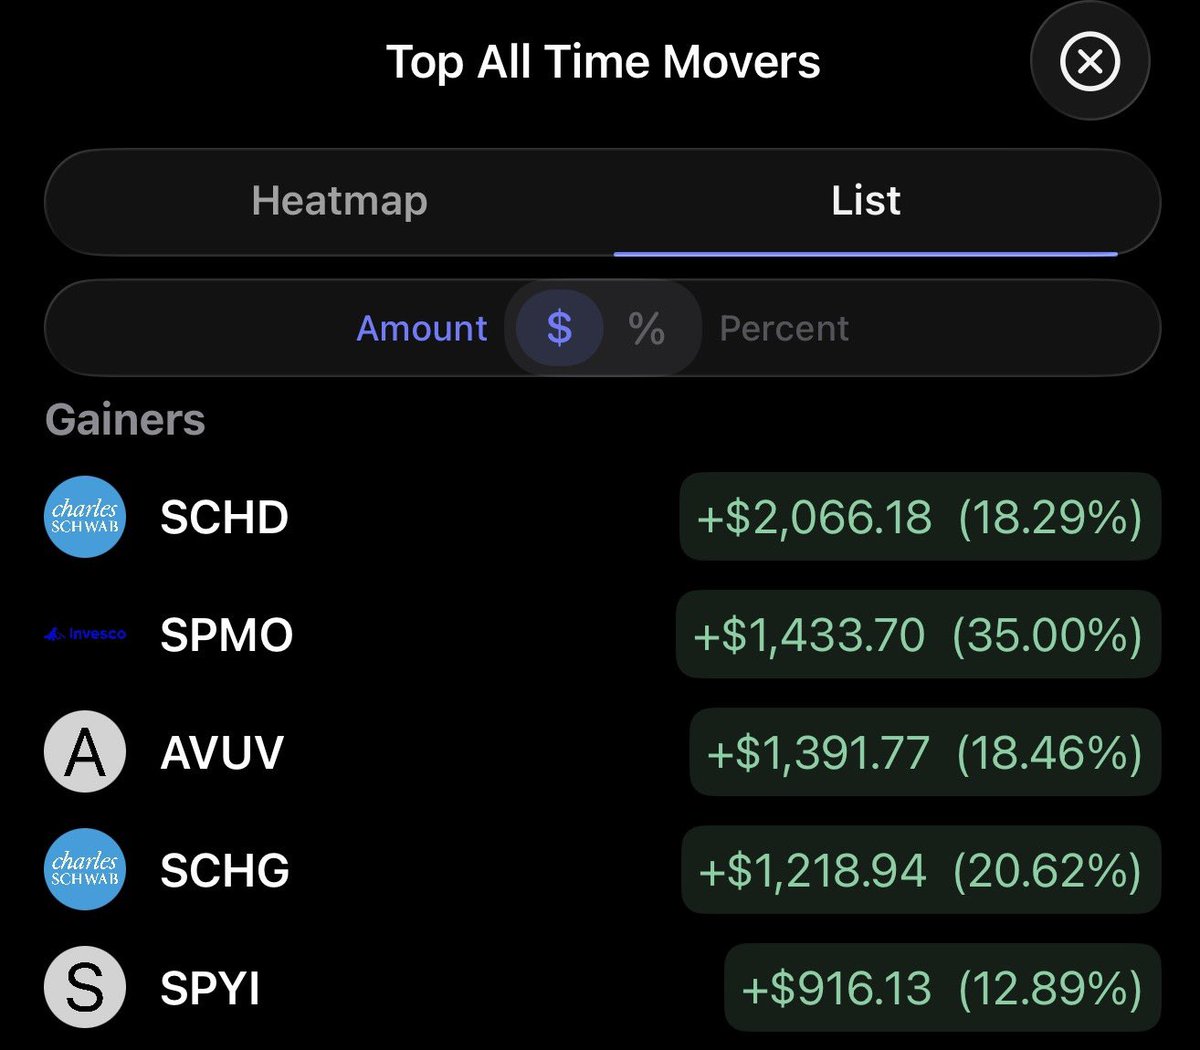
My top 5 all-time movers have done some serious heavy lifting:
$SCHD +$2,066
$SPMO +$1,434
$AVUV +$1,392
$SCHG +$1,219
$SPYI +$916
Dividends keep rolling in, the portfolio keeps compounding, and the long-term plan keeps doing its job.
Not at the yearly high, but I definitely can’t complain.
Keep mining. Keep investing. ⛏️💰
#DividendInvesting #Investing #PortfolioUpdate