Grafton Secures Exclusive Option from Newmont on the Poseidon and Jabali Gold Projects in Chile.
Grafton Resources has entered into an exclusive option agreement with Minera Newmont Chile Limitada to acquire 100% of the Poseidon Au-Ag-Cu Project (Valparaíso Region) and the Jabali Gold Project (Aysén Region).
Poseidon sits adjacent to our Alicahue Gold-Copper Project, creating a contiguous 14,383-hectare land package with district-scale epithermal potential.
Poseidon
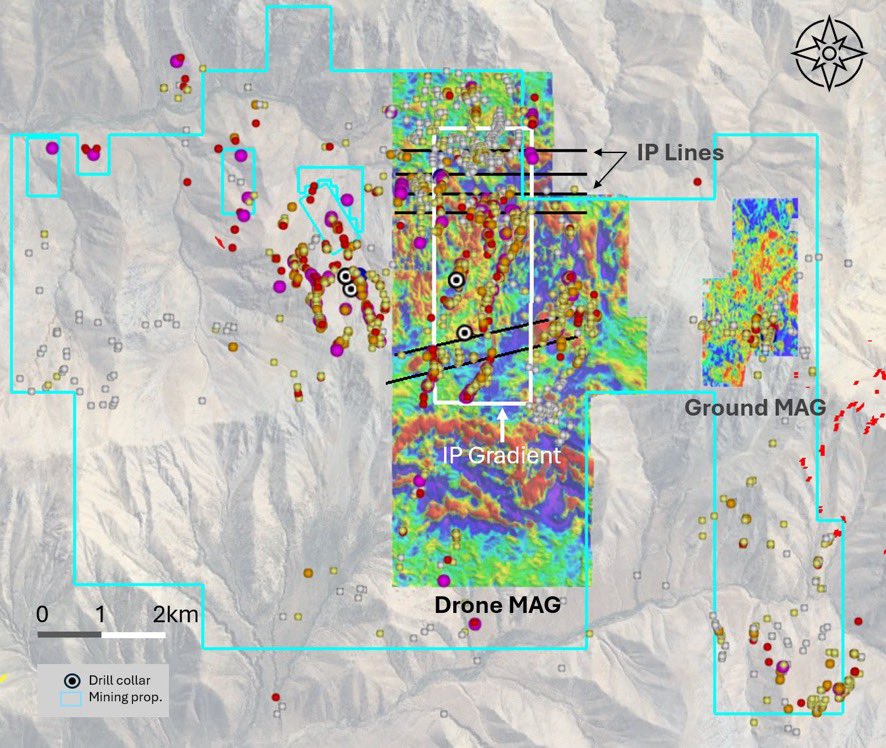
🔘 Rock chips up to 234 g/t Au and 1,500 g/t Ag at surface (within 2,350 samples)
🔘 >15 km of potential gold-bearing vein strike with multiple anomalous outcrops
🔘 ~10 km of road access; near-term drill targets
Jabali (separate southern asset)
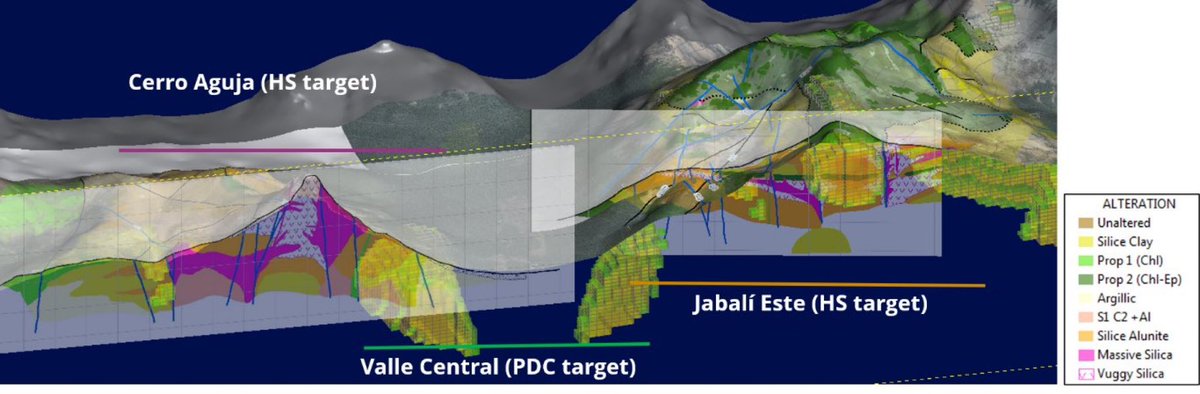
🔘 7 km × 3.5 km high-sulfidation alteration footprint (Cerro Aguja and Jabali Este)
🔘 228.9 km², entirely undrilled
🔘 Drill-preparation infrastructure largely completed
Chairman Campbell Smyth: “I am extremely excited to announce a pivotal transaction for Grafton that gives the Company access to an exceptional exploration portfolio. Poseidon and Alicahue together represent a district scale epithermal vein cluster with gold-silver-copper mineralization potential. Jabali has high sulfidation mineralization that can be tested quickly. We look forward to moving quickly on work programs on both assets.”
This strengthens the Chile portfolio: a consolidated Alicahue–Poseidon district in Valparaíso, plus a standalone high potential target at Jabali.
$GFT.CN $GFTFF #JuniorMining #Gold #Copper #Chile
$GFT.CN $GFTFF Grafton Secures Exclusive Option from Newmont on the Poseidon and Jabali Gold Projects in Chile.
Grafton Resources has entered into an exclusive option agreement with Minera Newmont Chile Limitada to acquire 100% of the Poseidon Au-Ag-Cu Project (Valparaíso Region) and the Jabali Gold Project (Aysén Region).
Poseidon sits adjacent to our Alicahue Gold-Copper Project, creating a contiguous 14,383-hectare land package with district-scale epithermal potential.
Poseidon
🔘 Rock chips up to 234 g/t Au and 1,500 g/t Ag at surface (within 2,350 samples)
🔘 >15 km of potential gold-bearing vein strike with multiple anomalous outcrops
🔘 ~10 km of road access; near-term drill targets
Jabali (separate southern asset)
🔘 7 km × 3.5 km high-sulfidation alteration footprint (Cerro Aguja and Jabali Este)
🔘 228.9 km², entirely undrilled
🔘 Drill-preparation infrastructure largely completed
Chairman Campbell Smyth: “I am extremely excited to announce a pivotal transaction for Grafton that gives the Company access to an exceptional exploration portfolio. Poseidon and Alicahue together represent a district scale epithermal vein cluster with gold-silver-copper mineralization potential. Jabali has high sulfidation mineralization that can be tested quickly. We look forward to moving quickly on work programs on both assets.”
This strengthens the Chile portfolio: a consolidated Alicahue–Poseidon district in Valparaíso, plus a standalone high potential target at Jabali.
https://t.co/mWS0YHNPAd
#ad
$DBGI Digital Brands Group Delivers 221% Revenue Growth While Cutting Marketing Spend by 78%
AUSTIN, Texas, September 24, 2026--(BUSINESS WIRE)--Digital Brands Group, Inc. ("DBG" or the "Company") (NASDAQ: DBGI), a publicly traded company specializing in apparel and e-commerce, today announced significant growth and improved marketing efficiency across its collegiate licensing brand, AVO (https://t.co/agpurwN99m).
From August 1 through September 11, 2026, AVO generated a 221% year-over-year increase in revenue while reducing digital marketing expenditures by 78% compared with the same period last year. During the period, AVO also achieved a 3.65x return on ad spend (ROAS).
The results reflect accelerating revenue growth alongside significantly improved capital efficiency.
Key Performance Highlights
•221% year-over-year revenue growth from August 1 through September 11, 2026
•78% reduction in digital marketing spendcompared with the same period in 2025
•3.65x ROAS, demonstrating improved efficiency of marketing investment
•442% increase in weekly net revenue from Week 1 to Week 6 among universities launched in 2026
•For universities launched during 2026, weekly net revenue increased 442% from Week 1, representing the week of August 1, through Week 6, representing the week of September 5.
Read full release: https://t.co/N5FJhsuLqV
Good morning ☕
Futures are red and duration-sensitive after Wednesday’s yield shock. Nasdaq is taking the brunt; the Dow is holding up better.
$SPY $TSLA $AMZN $GOOGL $QQQ $HOOD $NVDA $AAPL $MFST $AMD $META $PLTR $CAR $BYND $OPEN $RKLB $ASTS $MVRL $QCOM $SPCX
Good morning ☕🦀🇺🇸
Thursday, September 24 — pre-market (~6:50 AM ET)
Futures are red and duration-sensitive after Wednesday’s yield shock. Nasdaq is taking the brunt; the Dow is holding up better. Small caps already got tagged yesterday.
Futures
•S&P 500: 7,728.50 (−44, −0.57%)
•Nasdaq 100: 30,473 (−292, −0.95%)
•Dow: 51,733 (−140, −0.27%)
•Russell 2000: ~2,849 (−11, −0.4%)
Wednesday close
•S&P 500 7,706 (−0.75%)
•Nasdaq Composite 26,936 (−1.13%)
•Dow ~51,512–51,523 (−0.66% to −0.70%)
•Russell 2000 2,839 (−1.77%)
Four-day winning streak snapped. Mega-cap growth and chips led the slide (Nvidia, Alphabet, Amazon, AMD, Micron). Cybersecurity held up — $PANW and $CRWD both finished ~+5%.
What’s driving the tape
1. Bonds are the story.
10-year yield printed ~5.12–5.14%, highest since 2007. 5-year cleared 5% (first time since 2006). 2-year ~4.90–4.95%. Hot activity data (flash PMI / S&P barometer) plus energy inflation pushed October hike odds to ~68% on FedWatch, up from ~49% a week ago. Fed Gov. Barr kept a hawkish tone. That’s a direct hit on long-duration tech after this week’s record run.
2. Oil / Hormuz still two-sided. Wednesday: Brent settled ~$103.08 (+3.9%), WTI ~$92.16 after Pezeshkian told the UN Iran would “never surrender,” while still talking diplomacy. Overnight oil chopped — early dip on “open to talks,” then bid back. Latest prints: WTI ~$93, Brent still ~$102–104. Hormuz remains closed pending Iran’s conditions. Diesel/export-ban chatter is an extra wild card; White House denied a 90-day diesel ban, Energy Sec. Wright has been mixed. EIA already showed a +3.0M crude build. Energy is the inflation pass-through the bond market is pricing.
3. Trump–Xi is today’s event risk. Xi is in Washington. Treasury Sec. Bessent said the trade truce is extended to Jan. 10. Agenda: AI, critical minerals, and the Iran war. Tech CEOs join for dinner. Markets want a calm headline; they will fade any tariff/AI-export surprise. Asia mixed: Nikkei +0.8%, Hang Seng −0.5% to −1%. Europe modestly lower.
Cross-asset
•Gold futures ~$4,260 (−0.6%) — yields and dollar winning
•Silver ~$63.70 (−1.2%)
•DXY ~101.2, USD/JPY ~158.76
•$VIX lifted into the mid-16s overnight
Calendar (ET)
•8:30 Initial claims (prev 196k, exp ~201k), continuing claims, Q2 current account
•10:00 New home sales Aug (exp +1.3% / ~615–650k after a −10.5% prior), building permits final
•Kansas City Fed manufacturing
•1:00 PM 7-year note auction also on the docket — another test of the bid after the weak auction that helped light the yield
spike
Earnings
•Pre-open: Darden $DRI — cons. $2.05 EPS / $3.21B. Casual-dining traffic vs ticket is the consumer tell.
•After close: Costco $COST — cons. ~$6.55 EPS / ~$94.9B. Comp sales already known (~+6.7% ex-gas/FX); focus is membership, renewal, margins, and guidance. Options imply ~±3.2%. Also: $UEC, $BB, $SCHL.
Setup into the open
Bias is lower, yield-led, not a clean risk-off washout. NQ is the weakest link; energy and short-duration names have a relative bid if oil stays firm. Claims at 8:30 can move the front end; a hot print keeps the 10-year bidless and keeps pressure on multiples. A soft print is the only clean path to a futures bounce before the Trump–Xi headlines.
Watch:
1.10-year holding 5.10%
2.WTI around $92–94 / any Hormuz headline
3.NQ vs ES spread (tech still the duration punchbag)
4.COST after the close for the consumer read
Not investment advice — just the tape as of ~6:50 AM ET.
First Breach just flew its drone prototype untethered.
First Breach (NASDAQ: $FBDT) announced the first free-flight test of its proprietary U.S.-made drone prototype. The aircraft operated its airframe, propulsion, and core systems without a tether — a step the company calls the point where a test article becomes a vehicle.
The flight used commercial electronics while First Breach and partner Hellbender continue work on a proprietary flight controller (now running Betaflight). Next: integrate that controller and keep testing toward initial prototypes in Q4 2026 and production scale-up in Q2 2027.
Current proof-of-concept specs
🌏4-rotor Class 1 platform
🌏2.2 kg all-up weight, ~500 g payload
🌏2 km range, ~10 min endurance
🌏50 km/h cruise / 120 km/h max
🌏GNSS + visual-inertial nav, 900 MHz MAVLink
🌏Field-assemble in under 10 minutes
The company is targeting more than 2,500 drones per week at scale, with First Breach owning the platform and IP and Hellbender supporting engineering and domestic component manufacturing.
CEO Jeffrey Low: “Every step we take on this program is a step toward owning the full stack… here in the United States.”
Source: First Breach press release, Sept. 23, 2026.
Not investment advice. See disclosure https://t.co/eYkI2YiijJ
$FBDT First Breach Completes First Untethered Flight of Proprietary Drone Prototype, Advancing American-Made Unmanned Systems Program
Untethered flight validates airframe and vehicle systems as First Breach moves toward completion of initial prototypes in Q4 2026.
Company reaffirms target of scaling production in Q2 2027, supported by its strategic agreement with Hellbender for engineering, design, and domestic component manufacturing.
HAGERSTOWN, MD / ACCESS Newswire / September 23, 2026 / First Breach Inc.(NASDAQ:FBDT) ("First Breach" or the "Company"), an American-made defense technologies company focused on vertically integrated ammunition production and next-generation unmanned aerial systems, today announced the successful completion of the first untethered flight of its proprietary drone prototype. The Company also reported progress on its proprietary flight controller, developed under its strategic agreement with Hellbender, Inc., as it works toward completing initial prototypes in the fourth quarter of 2026.
Building on the first flight announced on August 25, 2026, the latest milestone demonstrated operation of the prototype's airframe, propulsion, and core vehicle systems in free flight without a physical tether. The aircraft flew using commercial flight electronics while development of the Company's proprietary controller proceeded in parallel. Integrating that controller into the aircraft for further testing is the next development step.
"Untethered flight is the point where a drone stops being a test article and starts being a vehicle," said Jeffrey Low, Co-Founder and Chief Executive Officer of First Breach. "Every step we take on this program is a step toward owning the full stack, meaning the airframe, the electronics, and the manufacturing, here in the United States. This flight is a visible marker of that progress."
Read full release: https://t.co/CkCTBkTaH5
Communicated-Disclaimer: https://t.co/74d53ruqxi
$BLLB is focused on hospitality / lifestyle, crypto, and AI. The live brand is MORE — Las Vegas nightlife, dining, and events.
$SPY $TSLA $AMZN $GOOGL $QQQ $HOOD $NVDA $AAPL $MFST $AMD $META $PLTR $CAR $BYND $OPEN $RKLB $ASTS $MVRL $QCOM $SPCX
$BLLB is a nano-cap OTC stock. It trades around $0.0012–$0.0013 as of late September 21 data. Market cap is roughly $1.3–1.6 million. Outstanding shares are about 1.38 billion, with 5 billion authorized.
What the company is:
Current OTC profile and press releases frame it as a holding company focused on hospitality / lifestyle, crypto, and AI. The live brand is MORE — Las Vegas nightlife, dining, and events with token-gated access via $MORE and the https://t.co/WHry3z5nhA reservation site. Peter Klamka is listed as CEO/President. Address is Boca Raton; contact and brand activity point to Las Vegas.
Recent company updates
•Aug. 20, 2026 — Shareholder update (OTC disclosure).
•May 13, 2026 — Expansion, new venue partnerships, upcoming membership tier.
•April 14, 2026 — MORE hosted a WrestleMania pregame and PowerSlap after-after party at Forty Deuce.
•March 4, 2026 — Partnership with Forty Deuce at Mandalay Bay.
•Nov. 2025 — Launch of https://t.co/WHry3z5nhA (wallet-verified, token-gated bookings) and listing of MORE Coin on Biconomy.
Financial snapshots that circulate show ~$1.0 million TTM revenue and a small reported profit, but those figures look dated relative to the current MORE / token story and should not be treated as current operating results.
Copper spot hit a new all time high yesterday, while Fitzroy minerals continues to advance its copper story. It continues to evolve with responsible disclosures from the company’s management.
If you follow me, then you know that I’ve been here for years. I’m affiliated with the company and invested.
I stress, as always, that this is not investment advice. Please see disclosures. $FTZ.V $FTZFF
$FTZ.V $FTZFF Fitzroy Minerals Reports Copper Recoveries of up to 82.6% from Mini-Column Testing, With Preliminary Larger-Scale Results Trending Higher, at the Buen Retiro Copper Project, Chile
VANCOUVER, BC - September 23, 2026 (NEWMEDIAWIRE) - Fitzroy Minerals Inc. (TSXV: FTZ, OTCQX: FTZFF, FSE: C3Y)("Fitzroy" or the "Company") is pleased to announce results from the initial phase of metallurgical test work completed by SGS Laboratories ("SGS") at the Buen Retiro Copper Project, Copiapo, Chile ("Buen Retiro" or the "Project"). The test program is evaluating the response of the Project's three principal geometallurgical units ("UGM" or "Units") to heap-leach processing, to support the Company's planned Heap Leach Development Plan. The distinct units, based on mineralogy and grade are high-grade oxide, low-grade oxide, and Mixed. Mini-column testing, the first stage of column-based testing, is now complete, while larger-scale 1-metre column tests are ongoing and are already trending above the mini-column results.
Read full release: https://t.co/m69fguhqKK
Good morning ☕🦀🇺🇸
Pre-market — Wednesday, September 23, 2026
Futures are essentially flat after a split session. Nasdaq printed a second straight record close on AI/semis; the Dow lagged on financials. Oil is the main pressure valve this morning.
Tone: digesting yesterday’s Nasdaq high, softer crude, and two diplomatic events (UN Iran talks + Trump–Xi tomorrow).
Yesterday’s cash close
•Nasdaq Composite: +0.45% to 27,244 — new intraday and closing record
•S&P 500: flat / -0.01% at ~7,765 (~0.7% off its high)
•Dow: -0.36% to 51,864
•Russell 2000: +0.51%
Tech carried the tape. Financials were the drag. Memory names (MU, SNDK) and SOXX ripped into the close; they’re giving a little of that back pre-market.
Oil, metals, rates, FX
•WTI: ~$89.70–$90.00, down ~0.5–0.8%
•Brent: ~$99.20–$99.35, still pinned just under $100
•Gold: ~$4,315, down ~0.9%
•Silver: down ~2.5–3%
•10-year yield: ~4.96%
•EUR/USD: ~1.142 | USD/JPY: ~157.8
Crude is lower on two supply/diplomacy items: Saudi East–West pipeline restarting after the Sept. 10 attacks, and a multi-hour U.S.–Iran meeting on the UN sidelines that Trump called “very good.” He also said at the UN he faces a “big decision” — deal or “annihilate.” Markets are trading the de-escalation bid, not the rhetoric.
The two headlines that matter today
1Iran / Hormuz / oil — Talks at UNGA. Any leak that looks like a ceasefire or Hormuz reopening would keep crude under $100 and support multiples. A breakdown does the opposite. Saudi pipeline restart is the near-term supply offset.
2Trump–Xi in Washington Thursday — Xi arrives today. Agenda: trade truce, AI rules, rare earths, Taiwan, and the Iran war. Mag7 names tied to that dinner ($NVDA, $AAPL, $AMZN, $META, $TSLA, $GM) are mostly flat-to-slightly green pre-market. Don’t expect a signed deal; watch tone and any AI/export language.
Calendar
•7:00 AM ET — MBA mortgage applications
•9:45 AM ET — S&P Global flash PMIs (Sept)
◦Mfg: 53.5 expected (prior 53.9)
◦Services: ~55.7–56.0 expected (prior 56.5)
◦Still expansion territory; a hot print keeps the “higher for longer / possible extra hike” narrative alive
•10:30 AM ET — EIA crude inventories
Thursday/Friday get heavier: claims, current account, new home sales, durables, UMich final.
Earnings today
Cintas $CTAS, General Mills $GIS, Cracker Barrel $CBRL. Consumer/services names, not mega-cap tech.
Premarket movers worth noting
•$IONQ +12% — real-time quantum error-correction decoder running on a standard CPU; Quantum World Congress starts today (IBM/MSFT keynotes).
•$WOR +15% — beat on revenue/EPS; data-center cooling tank demand.
•$RCL weaker — $3B, 50% stake in Sandals Resorts.
•Memory / SOX complex ($MU, $SNDK, $SOXX, $DRAM ETF) modestly red after a two-day rip.
•$META slightly bid; Connect event tonight.
Setup
Range-bound open unless PMI or EIA surprises. The tape is still split: AI/infra and Nasdaq at highs vs. financials/energy-sensitive Dow. VIX was ~14 yesterday — cheap vol relative to the geopolitics.
Watch list into the open: Brent hold/break of $99–$100, 10-year around 4.96%, PMI vs. 53.5/56.0, and any UN or White House leak on Iran before Xi lands.
Good morning ☕🦀🇺🇸
Tuesday pre-market — Sep 22, 2026 (~7:40 AM ET)
Digesting Monday’s AI melt-up. Futures are basically flat. Oil and the 10-year are the two tapes that still matter.
Futures / Monday close
Monday: Nasdaq Comp +2.26% to 27,122 (first record close since June 2), S&P +1.49% to 7,764.70 (within ~0.4% of the Aug. 13 high), Dow +0.71% to 52,048.83, Russell 2000 +0.52% to 2,875. Nasdaq-100 closed +2.83%.
Overnight futures have chopped around unchanged:
•Dow roughly +0.2% to +0.3%
•S&P 500 flat to +0.1%
•Nasdaq-100 flat to +0.1%
•Russell modestly higher
Reuters had ES/NQ slightly red around 5:30 AM; later prints leaned slightly green. Setup into the open is consolidation, not a gap continuation.
$VIX is still muted around 14.8–14.9.
What drove Monday
This was an AI/consumer-agent tape, not a broad risk-on.
•$META +11.3% after Muse hit #1 on the App Store; analysts framed early download velocity as stronger than ChatGPT’s launch window. Slightly higher again premarket.
•$AMD +~10%, first print above a $1T market cap.
•$INTC +12%, ARM +17%.
•$NVDA +~2% Monday; a touch soft premarket along with TSMC / SK Hynix / memory ETFs.
Premarket Mag7: $GOOGL, $AMZN, $MSFT modestly green; chips mixed-to-soft after the squeeze. Breadth was better than recent sessions but still tech-led.
Oil / geopolitics (the real swing factor)
Crude is the overnight wildcard. Monday’s drop (WTI roughly −3.5%, Brent −3%) took the complex off last week’s spike and put Brent back near / under $100. Early Tuesday prints cluster around:
•WTI ~$92–$94
•Brent ~$98–$101
Direction flipped a few times overnight. Latest U.S. wrap had WTI ~−2.2% near $93.70 and Brent ~−1.5% near $98.85. Treat those as moving numbers.
What’s moving it:
•Iranian official to Reuters: Tehran could reopen Hormuz within 7 days if Washington eases military pressure.
•Trump said he’s open to meeting President Pezeshkian on the UNGA sidelines; Pezeshkian is expected in New York.
•Hormuz flows reported at a 6-month high; Saudi East-West pipeline restarted.
•Offset: new U.S. sanctions aimed at shutting Iranian airlines and targeting facilitators in Egypt, Turkey, and Russia. Houthi strikes on Saudi targets remain in the mix.
Six-month U.S.–Iran conflict is still the oil regime. Diplomacy headlines = lower crude / higher multiples. Fresh sanctions or a closed strait = the opposite.
Trump–Xi is the other event risk. Xi in the U.S. Sep 23–25, leaders’ meeting Thursday in Washington. Bessent called weekend talks with He Lifeng “very successful.” Agenda: trade truce extension, AI, Taiwan, Iran. Chip names will trade every rumor.
Rates / dollar / metals / crypto
•10-year ~4.93%, down about 2 bps. Still the level that capped the summer.
•DXY ~100.3–100.4
•Gold ~$4,350–$4,365, slightly softer
•bitcoin:native ~$86k, off a 7-month high; $HOOD / $COIN / $MSTR / $CRCL −1% to −2% premarket
Fed hiked last week (first hike in three years). CME FedWatch ~58% odds of another 25 bp in October. Today’s speakers: Jefferson, Williams, Barkin (Barkin 1:00 PM). Markets are still pricing “higher for longer” even as oil comes in.
Calendar
•7:45 ICSC weekly retail sales
•8:55 Redbook weekly sales
•10:00 Richmond Fed manufacturing
•1:00 $78B 2-year auction + Fed speakers
•Earnings: $AZO, $THO, $MLKN (before); $KBH, $WOR (after)
•$UNGA opens; Jefferies AI Summit (SF)
Light data day. Tape will trade oil + UNGA chatter + Trump–Xi positioning + Fed speak.
How it sets up
Bull case into the open: oil stays sub-$100, 10-year holds under 5%, META/AMD leadership doesn’t reverse, and UN/Hormuz headlines stay diplomatic. That keeps NQ near records and gives ES a shot at the August high.
Bear case: Iran talks disappoint, crude snaps back through $100, or a hawkish Fed speaker re-steepens the front end. Monday was narrow leadership — chips and META did the work. If those fade and energy rips, breadth dies fast.
Fake outage. $NKE, which owns @Converse, pulled an ad after the crybaby leftist claimed the ad was connected to the hate group, KKK. Absolute B/S.
$SPY $TSLA $AMZN $GOOGL $QQQ $HOOD $NVDA $AAPL $MFST $AMD $META $PLTR $CAR $BYND $OPEN $RKLB $ASTS $MVRL $QCOM $SPCX
Yesterday: custom speed suit, athlete-first Nike.
Today: Converse, which Nike owns, pulls this ad, says they got it wrong, and apologizes.
Same week. Same company.
Just (don’t) do it
$NKE
$NNVC looks like the offload pt from the downtrend on near term 🤔
$BIDU Options trading calls 👀
$ARM - Play of the DAY
$SPY $TSLA $AMZN $GOOGL $QQQ $HOOD $NVDA $AAPL $MFST $AMD $META $PLTR $CAR $BYND $OPEN $RKLB $ASTS $MVRL $QCOM $SPCX
$FBDT First Breach just locked in a 3 year ammo supply and distribution deal with SAS Ammo.
🌏 Monthly purchases of 5.56mm and 9mm start at 3 million rounds in Oct–Dec 2026
🌏 Scale to 5 million rounds/month in Q1 2027
🌏 Then a minimum of 8 million rounds/month from April 2027 onward
🌏 SAS becomes exclusive on those two calibers, buying First Breach’s output from the Hagerstown, MD facility
🌏 Veteran- and law-enforcement-owned distributor with retail and wholesale reach nationwide.
This is the kind of contract that turns expanded U.S. manufacturing capacity into actual scheduled demand instead of “we can make it if someone orders it.”
American-made ammo, defined offtake, and a partner already selling into shooters, ranges, retailers, and LE.
Nasdaq-listed defense name executing on the production story.
Always do your own due diligence. Not investment advice. See disclaimer. https://t.co/xNX7jIZME4 #Ad
$FBDT First Breach Announces Three-Year Ammunition Supply and Distribution Agreement with SAS Ammo
Monthly purchases of 5.56mm and 9mm ammunition scheduled to increase from 3 million to a minimum of 8 million rounds, supporting expanded manufacturing operations
HAGERSTOWN, MD / ACCESS Newswire / September 17, 2026 / First Breach Inc.(NASDAQ:FBDT) ("First Breach" or the "Company"), a U.S. based developer and manufacturer of defense technologies, today announced that it has entered into a three-year ammunition supply and distribution agreement with SAS Ammo ("SAS"), an ammunition retailer and wholesale distributor owned by veterans and law enforcement professionals. The agreement establishes monthly purchasing commitments beginning in October 2026, increasing from 3 million rounds to a minimum of 8 million rounds as First Breach continues to scale its ammunition production and sales.
Based in Martinsburg, West Virginia, SAS serves customers nationwide, including individual shooters, firearm retailers, shooting ranges, instructors and law enforcement agencies. Its retail and wholesale channels provide an opportunity to broaden distribution of First Breach's American-made ammunition.
The agreement covers 5.56mm and 9mm ammunition manufactured at First Breach's ISO 9001:2015 certified facility in Hagerstown, Maryland. Monthly purchase commitments are scheduled as follows:
•October through December 2026:3 million rounds per month, consisting of 2 million 5.56mm rounds and 1 million 9mm rounds.
•January through March 2027: 5 million rounds per month, consisting of 3 million 5.56mm rounds and 2 million 9mm rounds.
•April 2027 through the remainder of the agreement: A minimum of 8 million rounds per month, consisting of at least 5 million 5.56mm rounds and 3 million 9mm rounds.
The agreement provides for SAS to purchase First Breach's entire output of these two calibers, subject to specified purchasing and supply conditions. First Breach will serve as SAS's exclusive supplier of 5.56mm and 9mm ammunition, with provisions allowing alternative sourcing if the Company cannot meet SAS's requirements.
Read Full Release: https://t.co/CUFQc7Z5zH
Disclaimer
https://t.co/74d53ruqxi
$TONE.CN Triple One Metals announces over subscribed financing. They came for $800 K. They took ~$1 Million.
https://t.co/EBMRLcgoey
$SPY $TSLA $AMZN $GOOGL $QQQ $HOOD $NVDA $AAPL $MFST $AMD $META $PLTR $CAR $BYND $OPEN $RKLB $ASTS $MVRL $QCOM $SPCX
$TONE.CN Triple One Metals announces over subscribed financing. They came for $800 K. They took ~$1 Million.
Proceeds: exploration, regulatory, audit, legal, working capital.
The future is bright for the 100% owned Caledonia Brook gold copper ground in Newfoundland.
Crippleback Moosehead corridor, historical 8.95 g/t gold, copper gold model next door lighting up.
This Junior explorer just got funded.
Now the work starts.
Not financial advice. See disclosures
#ad $BHP $JNUG $GOLD $FCX
$TONE.CN TRIPLE ONE METALS INC. – Announces Financing – Oversubscribed
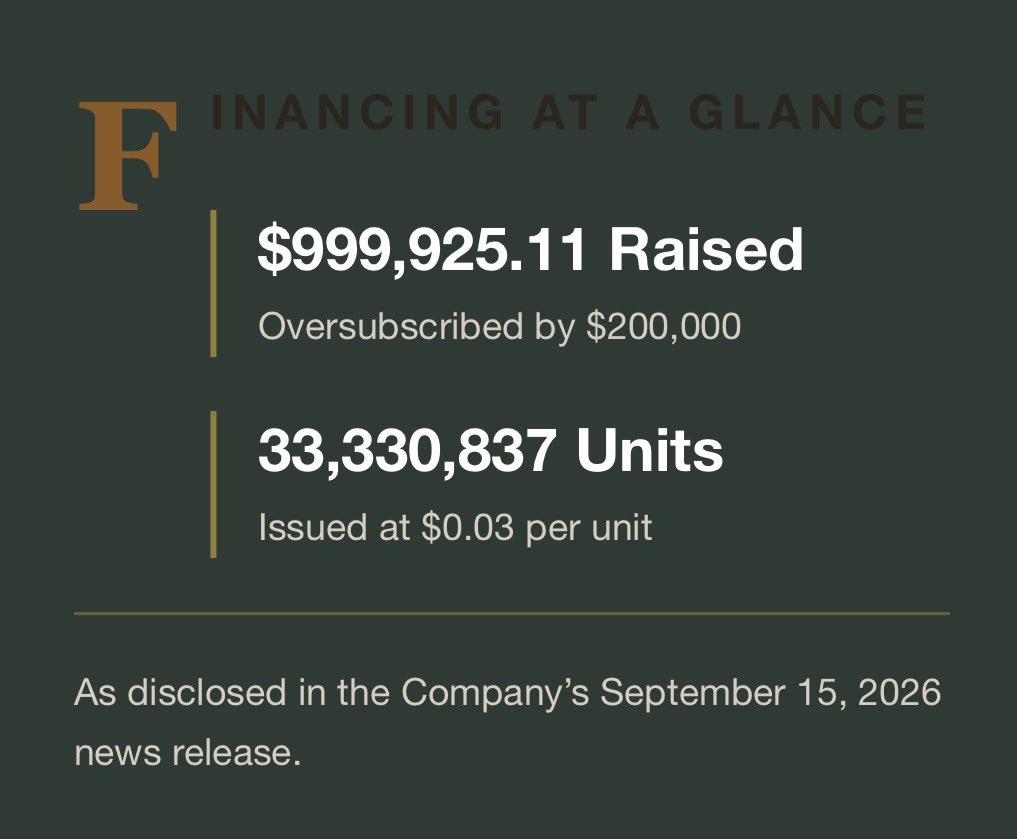
Non-brokered private placement closes at $999,925.11, oversubscribed by $200,000, with proceeds allocated to exploration, regulatory, audit, legal and working capital needs.
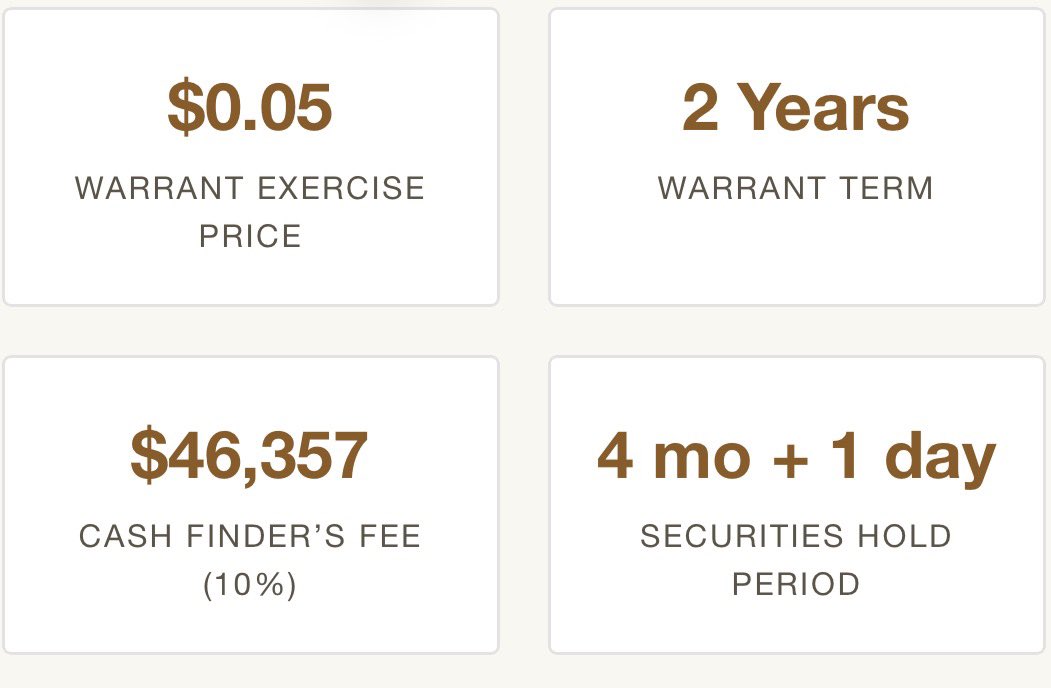
Triple One Metals Inc. (CSE: TONE) (“Triple One” or the “Company”) is pleased to announce that, further to its press release dated September 14, 2026, the Company has been successful in raising $999,925.11 (oversubscribed as to $200,000) and will issue 33,330,837 units at $0.03. Each unit will consist of one common share and one warrant exercisable for two years at $0.05.
The use of proceeds will be for exploration, regulatory, audit fees, legal fees, and working capital. While the Company intends to spend the proceeds from the financing as stated above, there may be circumstances where, for sound business reasons, funds may be reallocated at the discretion of the Board.
A cash finder’s fee of 10%, or $46,357, has been agreed to be paid.
The closing of the financing is subject to receipt of all necessary regulatory approvals, including from the Canadian Securities Exchange. The securities issued under the financing will be subject to a hold period ending four months and one day following the date of issue, in accordance with applicable securities laws.
The Company confirms there are no material facts or material changes related to the Company that have yet to be generally disclosed.
Read full release: https://t.co/QU5vYUmjmH
#ad
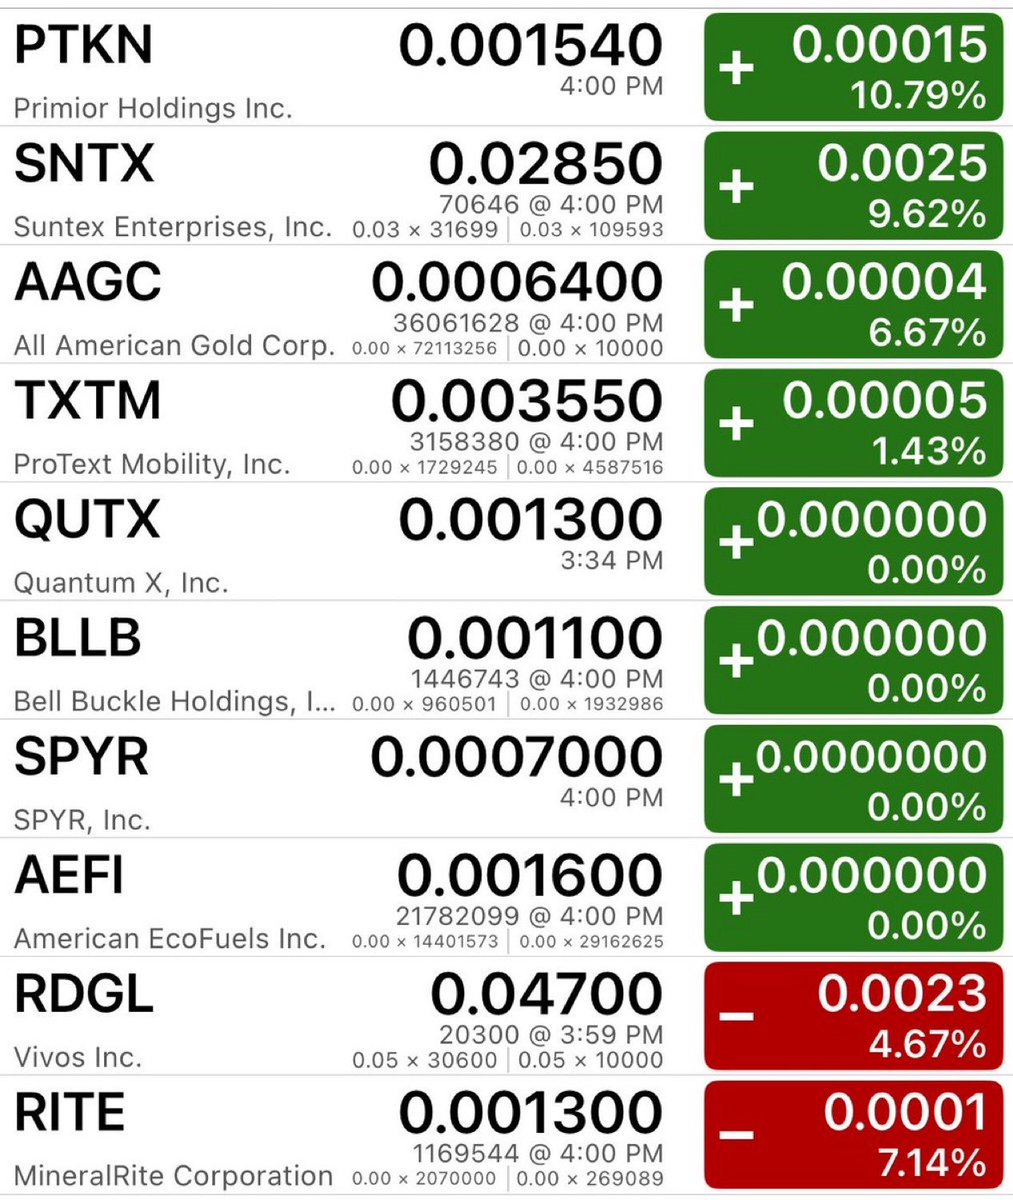
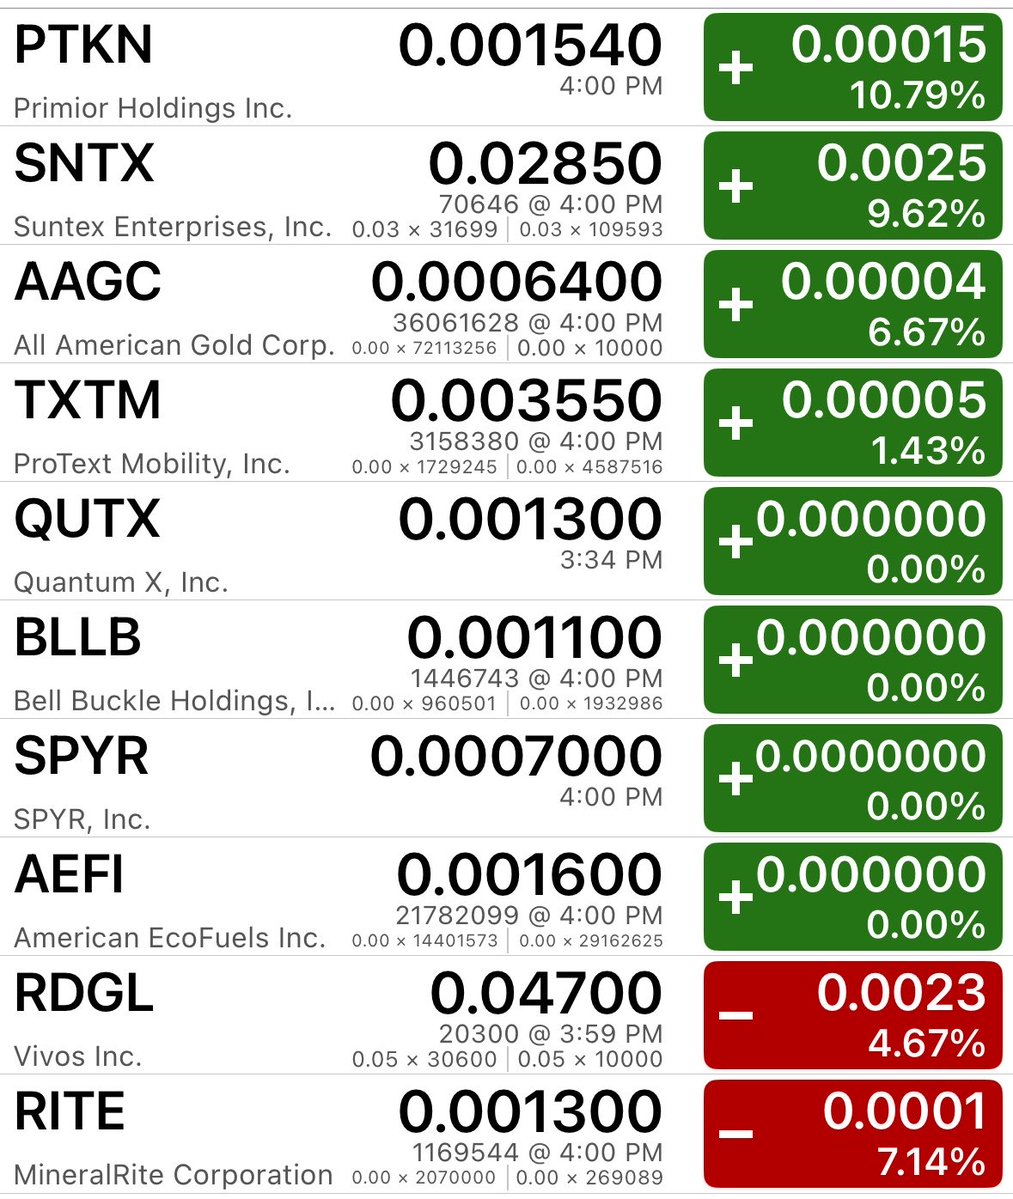
I’ve counted your votes and this is your top 10 mentioned OTC stocks going into this week.
Check back on Saturday to vote for next weeks’ top 10 list. OTC is back!
Top 10 most mentioned tickers:
$PTKN
$SNTX
$AAGC
$TXTM
$QUTX
$BLLB
$SPYR
$AEFI
$RDGL
$RITE
Good morning ☕️🦀🇺🇸
Futures are higher into the Monday bell as oil extends its slide and AI/semis bounce. The tape is still hostage to crude, the 10-year, and Thursday’s Trump–Xi meeting.
What’s driving the bid
1. Oil is coming off. Fourth down day. Brent ~$101.6–102.4, WTI back through $98 and printing as low as ~$97 on some feeds (~2–3% overnight). Weekend Houthi strikes on Saudi/Riyadh did not reverse the selloff.
Traders are pricing:
•More barrels actually moving through Hormuz / recovering Saudi exports (Kpler/JPM flow data)
•Trump saying he’d “probably” meet Iranian President Pezeshkian at UNGA
•China leaning on Tehran to cool Houthi hits on Saudi infrastructure
Brent is still above $100. One pipeline outage or a fresh Hormuz squeeze flips this bid fast. Airlines $DAL, $AAL are +~1% on the crude drop.
2. Yields off the highs. 10-year slipped back under 5% (~4.96%). 2-year ~4.72–4.74%. Friday tagged cycle highs (10-year briefly ~5.04%, highest since 2007). Lower oil = a little less inflation heat into a hawkish Fed. Dollar flat; yen still weak around 157.
3. AI/semis reopening after last week’s scare. “Doomsday” comments from AI execs faded as spend headlines came back.
Premarket:
•$INTC +~5.4–5.5%
•$AMD +~3%
•$MRVL +~2.6%
•$DELL +~2.7–2.9%
•$META +~2.4–2.5%
•$NVDA +~0.9–1%, $AMAT +~2.8%, $AVGO +~1.6%
•$ACN +~6% (Anthropic AI-safety / eval deal)
•$WBD +~7.6%, Paramount Skydance also bid on merger chatter
•Crypto beta: $COIN +~4–5%, $MSTR +~7%
Samsung jumped ~5% in Korea; Kospi +1.6–1.7%. Europe Stoxx 600 +0.7–0.9%. Japan is mostly closed for holidays this week.
4. Diplomacy calendar. Treasury Secretary Bessent called weekend talks with China’s He Lifeng “very successful.” Thursday Trump–Xi in Washington is the week’s event: tariffs/truce extension (current pause runs to November), critical minerals, AI rules, Iran. UNGA in New York all week. US–Denmark Greenland security deal is a side headline — tiny US-listed Greenland names exploded $GLND, $GRML, $CRML
Cross-asset
•Gold: ~$4,355–4,386, off ~0.5–0.9% (real yields still high; 10-year real ended last week ~2.67%, multi-decade)
•$BTC Bitcoin: bid into the low-to-mid $80ks, briefly tagged ~$84k (first since January on some prints); shorts got squeezed
•Dollar: little changed after last week’s post-hike lift
Fed backdrop (still the ceiling)
Last week: +25 bps to 3.75–4.00%, first hike in three years. Futures imply roughly a 50–56% chance of another hike in October; year-end hike is widely treated as base case. Chicago Fed’s Goolsbee speaks today; ~10 officials on the tape this week. Oil staying >$100 keeps the hawkish lean intact.
Today’s calendar — light
•8:30 AM ET: Chicago Fed National Activity Index (August; July was -0.08, consensus around flat/slightly negative)
•Goolsbee remarks
•Later: Lagarde, BoC’s Macklem
•Japan holiday (liquidity thinner in Asia)
Rest of week: Tue Richmond Fed; Wed flash PMIs (US/EZ/UK/Germany); Thu Trump–Xi, current account, new home sales, jobless claims; Fri durables + final UMich. Earnings: $COST, $GIS, $DRI.
How to frame the open
This is a relief bounce, not a clean regime change. Lower oil and a sub-5% 10-year give growth/AI room. The Dow is still the weak link after three down weeks.
Watch:
1Whether WTI holds under $100 into the cash open
210-year — a reclaim of 5.00% kills the bid
3Any headline from UNGA / Iran / Houthis before 9:30
4Whether INTC/AMD/MRVL follow-through or fade last week’s AI scare
Have a good week.