Founded by successful investors, helping fellow investors take concentrated bets in portfolio of stocks with strong PE re-rating potential. SEBI: INH000023597.
Divitiae Investments officially goes LIVE Today!!!!
We opened the waitlist during Diwali. Hundreds joined. Now its time to sign in. Three ready ideas waiting for you and more coming soon!!!
Research-backed.
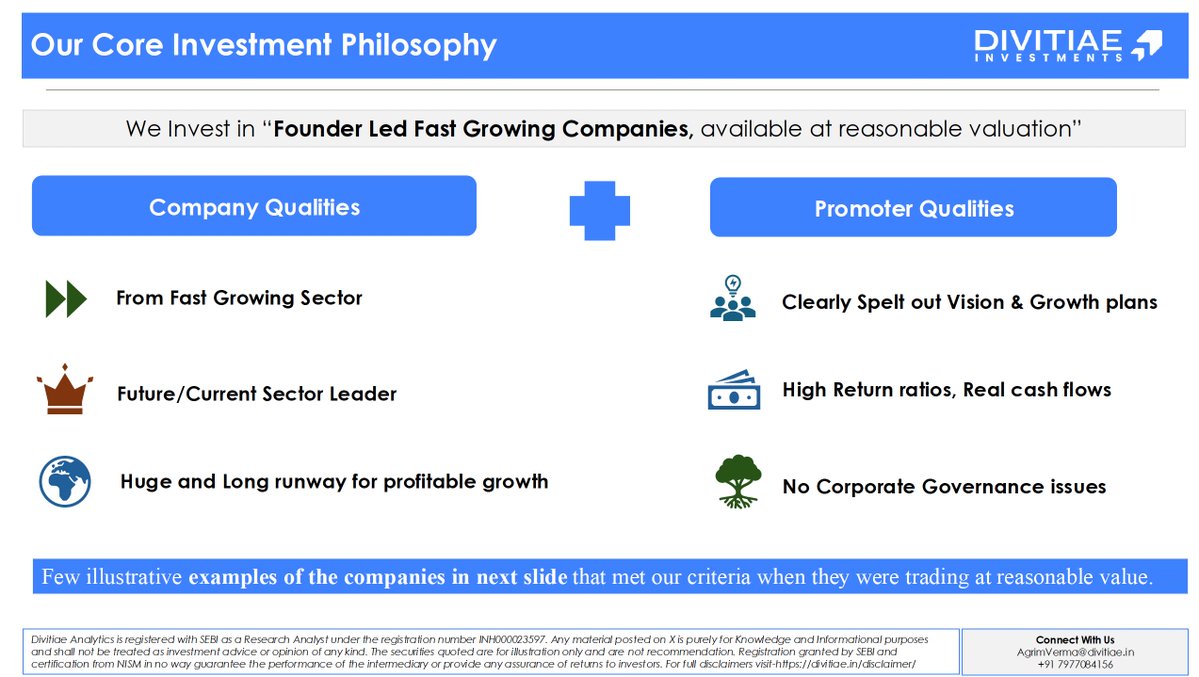
Founder-led fast-grower framework.
Real updates. Real conviction.
Let’s build wealth, the right way.
For Investor, By Investors
Team Divitiae
🚨 Smallcaps are getting cheaper. Are they getting safer?
Nifty Smallcap 100 is down ~12% from its peak, breaking key support.
Weekly RSI near 37 signals weakness—not oversold yet.
#SmallCaps
Markets are testing patience.
This Dussehra, a small gift to my followers.
Wishing you clarity, conviction and wiser investing. 🪔
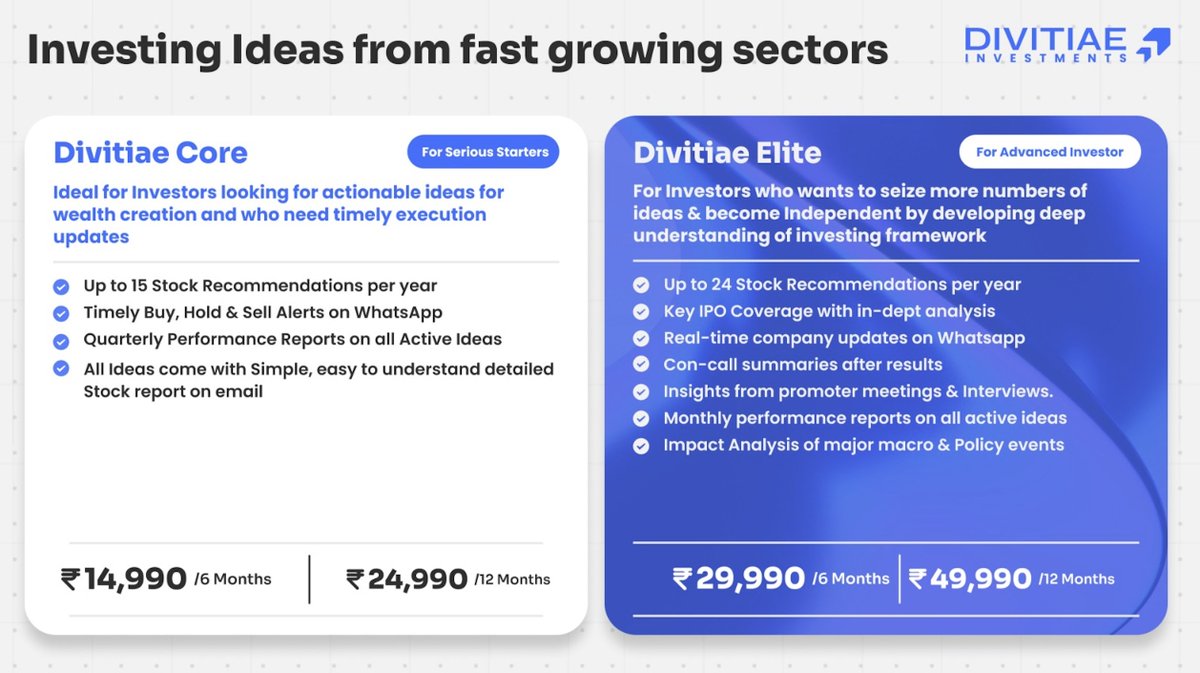
Divitiae festive offers 👇 Code: VIJAYA35
@DivitiaeIn@AimInvestments
Underperformers performed. Outperformers took profit. 😂
Today’s scoreboard:
🇮🇳 Nifty +1.2%
🇹🇼 Taiwan -2%
🇰🇷 Kospi -5%
Reminds me of Onida’s iconic tagline: “Neighbour’s Envy, Owner’s Pride.” 😈
Yes we have a long way to go. But for today let us enjoy this little plot twist! 😊
Cupid 50,000 Cr MCap for Sales of <500 Cr
No moat, no high end tech, no recurring ensure revenue, not a big consumer brand
PE: >350 (no one looks at PE nowadays we know)
We are living in a momentum & story driven market.
Decoding RBI Monetary Policy | 7 October 2026
Divitiae Investments Research Desk
1. The decision
- RBI raised the repo rate, its key lending rate, by 0.25%. The repo rate is now 5.50%, up from 5.25%
- This is the first increase in the repo rate since February 2023
- The decision by RBI's Monetary Policy Committee to raise the rate was unanimous
- RBI also changed its policy stance from "neutral" to "calibrated tightening"
2. What "calibrated tightening" means
- From here, RBI will either raise the repo rate again or keep it at 5.50%
- RBI Governor Sanjay Malhotra said a cut in the repo rate is off the table in the near term
- Each future decision will depend on how the inflation and GDP growth numbers come in
3. Why RBI raised the repo rate
- Retail inflation (CPI) was 4.82% in August 2026. It has been above RBI's 4% target for three months in a row
- Core inflation, which is retail inflation without food and fuel, rose to 4.2% in August 2026. This shows that prices are rising across a wider set of goods and services, not only food and fuel
- Crude oil is trading above $100 a barrel, which raises India's import bill and fuel costs
- The rupee is weak at about 96.4 to the US dollar, which makes imported goods costlier
- India's GDP grew 7.8% in the April to June 2026 quarter. With the economy growing this fast, RBI has room to focus on bringing inflation down
4. RBI's forecasts for FY27 (April 2026 to March 2027)
- Retail inflation (CPI) forecast for FY27: 5.2%, raised from 5.0% in the August 2026 policy
- Retail inflation forecast by quarter: 4.9% for July to September 2026, 6.0% for October to December 2026, and 5.7% for January to March 2027
- Real GDP growth forecast for FY27: 7.1%, raised from 6.7% in the August 2026 policy
- Real GDP growth forecast by quarter: 7.2% for July to September 2026, 6.9% for October to December 2026, and 6.8% for January to March 2027
5. How a repo rate hike affects the economy
- Banks now pay more to borrow from RBI, and they pass this higher cost on to their customers over the next few weeks
- Interest rates on loans go up, both on existing floating-rate loans and on new loans
- Because borrowing costs more, households and companies borrow and spend more carefully. Lower spending brings inflation down over time
- Banks also tend to raise interest rates on fixed deposits, so savers earn more
https://t.co/NT4CI834h0 IMPACT
- The 0.25% hike was widely expected, so the decision itself was not a surprise
- The more important message for the market is that interest rates are unlikely to come down in the near term
- Banks, auto companies and real estate companies are the most sensitive to interest rates, because their sales depend on loans
7. What it means for your money
- Home and car loans: If your loan is on a floating rate, your EMI is likely to rise in the coming weeks. For example, on a ₹50 lakh home loan for 20 years, if the interest rate moves from 8.00% to 8.25%, the EMI goes up by about ₹780 a month
- Fixed deposits: Banks are likely to raise fixed deposit rates. If your fixed deposit is due for renewal, check the new rates before you renew
- Debt mutual funds: Funds that hold long-term bonds can see a small fall in value in the short term when interest rates rise. New money invested in debt funds will earn a higher yield
- Equity: Companies with large borrowings will pay more interest, which reduces their profit. Companies with strong earnings and low debt are better placed
Our view
- This repo rate hike is small, at 0.25%, and the market had expected it
- RBI raised its GDP growth forecast for FY27 at the same time. This tells us RBI is controlling inflation in an economy that is growing well
- We see no reason to change a long-term investment plan because of this decision.
Bottom line
- Loans will get a little costlier and fixed deposits will pay a little more
- The repo rate is likely to stay at 5.50% or higher in the near term
- RBI's outlook for India's GDP growth remains strong, at 7.1% for FY27
Source: RBI monetary policy announcement of 7 October 2026, as reported by Business Standard and other news outlets. SEBI RA No. INH000023597. For information only, not a recommendation.
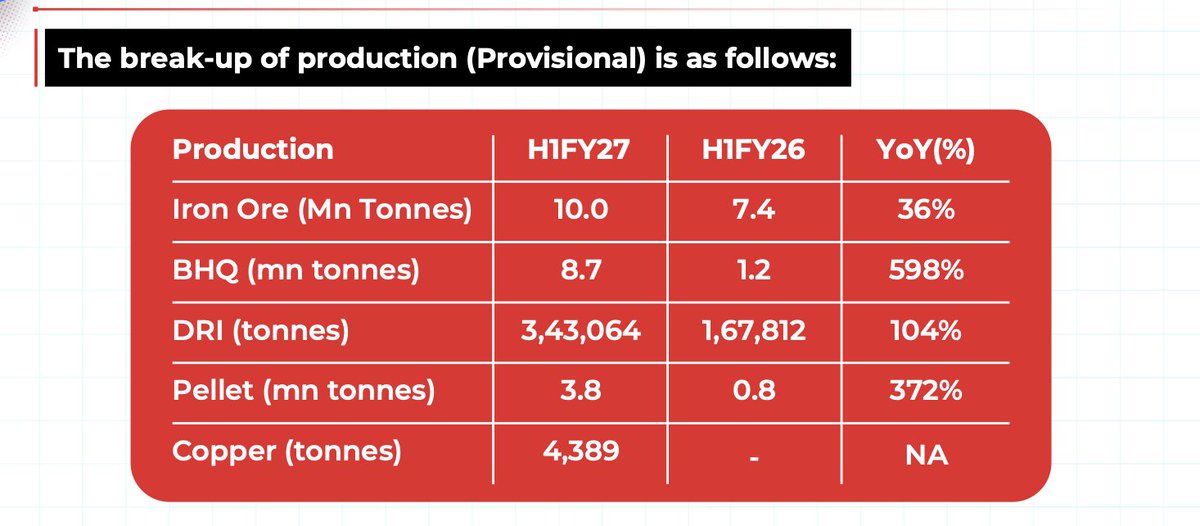
Strong operational performance by Lloyd metals in H1FY27
Iron Ore up 36%
DRI up 104%
Pellet up 372%
Copper is the new thing happening in the company
Disclaimer - Not a recommendation to buy/sell
Strong GST & Credit Growth Data 💚💚
September
Gross GST collections rise 14.7% YoY to ₹2.04 lakh crore
Net GST collections increase 18.1% YoY to ₹1.77 lakh crore
Bank Credit Growth latest data at 18.8% growth