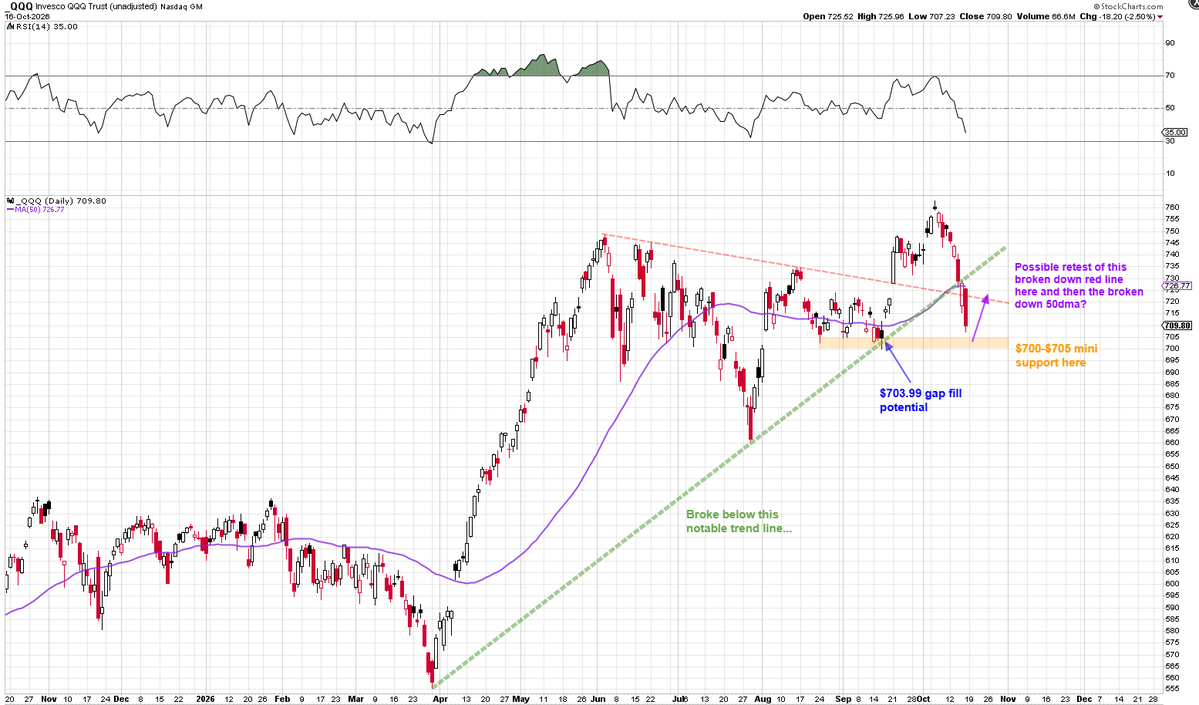
33% rally in $SPY since this breakout. Important to understand the power of large bases.
Best time to buy names are during 20% index draw downs aka recessions.
It’s been a monster opportunity the past 12 months. Since 380 $SPY really.
$SPY
This is what we were looking for the entire time since late July correction. A multi-week consolidation base on top of the 10-month base. We have now broken higher.
Likely setting up for a move to 480 to test top of 2-year base, and once broken out of we see much higher.
@jonbrooks It only takes a small demand to keep pushing that small supply higher or keep it at bay though.
Starter homes may be limited but that in of it self along with aggregate income being lower doesn’t create prices to fall.
Folks simply find solutions and other options.
@nickgerli1 Nick are you able to separate (segment) this data based on homes that are over $600k and the pool of folks with household income of +$200k.
It would more accurately represent the higher tier market that has stayed strong.
We’ve had 13 recessions since World War II, with an average unemployment rate of 7.8%. Most of the time, home prices don’t fall—so the 2008 housing crisis wasn’t a typical cycle.
Too early to say, but seasonality lining up with other factors may lead to some correction in housing.
@LoganMohtashami premature to make that call right Logan? We need see job losses.
This is a notably weak month-over-month nationally aggregated home price print, as expected
U.S. home prices, fell -0.5% in the latest MoM window (compared to the normal +0.1% MoM for that window)
Table via @ResiClub_HQ
Here is a better home value / income ratio.
@LoganMohtashami
Any correlation in your mind that will impact home prices.
Or again pair with this we need job losses to your point. To truly create the catalyst to see home prices fall.
There's only been three home-price bubbles in U.S. history over the last 70 years.
Today, with a Home Price/Income Ratio of 4.33x
Back in 2006, when it hit 4.45x.
And post WW2, when it hit 5.00x.
In the previous two cases, the bubble and lack of affordability didn't last long.
After 2006, prices crashed shortly thereafter, restoring the Home Price/Income to normal levels (below 3.5x).
Meanwhile, after WW2, home prices stopped growing for a decade, while incomes surged 5-10% per year. Pushing the Value/Income Ratio below 3.0x, to its most affordable level ever.
Indicating that there are two sides to the affordability coin: prices, and incomes.
Check Value/Income for your ZIP on Reventure Premium now: https://t.co/hEz5qenRCp
Nationally it’s almost two different home markets.
The strong vs weaker income areas.
This chart may be misleading as its aggregate.
May highlight national structural weakness of buyer. May be oversimplifying tho. @LoganMohtashami
Thoughts on income vs. home price gap.
This might be the most terrifying chart in real estate.
Median household income: $85,000.
Income needed to buy the median-priced home: $123,000.
That's a $38,000 gap - 45% MORE than the median household.
For decades, home prices and incomes moved together.
Then we broke the housing market.
Now we're expecting the next generation to buy homes their incomes can't support.
Who exactly is supposed to buy all these houses?
The math doesn't work. And math always wins.
@LoganMohtashami You’ve mentioned over the years we need to see “x” job losses for home prices to go down.
It is fair to say the job gains the past 12 months have been mis reported, as 8-9 of those months were revised down after the fact.
But to your point we still have not seen the job losses.
The perpetual issue in every day Americans lives…
Currently corporations are in late stage earnings bull market.
Recently it’s become a situation of squeezing costs and that is doing to have a foundation effect on overall health of future earnings.
We are nearing a cliff imo.