15 trades in 33 years. $1 became $22.68.
The golden cross: hold SPY when the 50-day average is above the 200-day, else cash. 9.8% CAGR, worst drawdown 34% vs 55% for buy & hold, 1993-2026.
Backtest: buy & hold still returned more, 10.9% a year.
Code in our Discord, link below.
Routing signals across prop accounts sounds safer than copying.
In my backtest it made 20-30% as much at the same blow-up rate per account. In return, weeks where half the accounts broke fell from 0.60 a year to 0.07.
Sep 2023-Sep 2025, 20 sim 50K accounts, fees + 2 ticks.
Rules: public posts by Quantified Strategies, QuantSeeker, StatsEdge Trading, Price Action Lab and Concretum. We reran them on daily data with costs, 2020 onward.
We call this one Shannon. Full breakdown with every rule goes up in our Discord: https://t.co/Gf3CcL1tgs
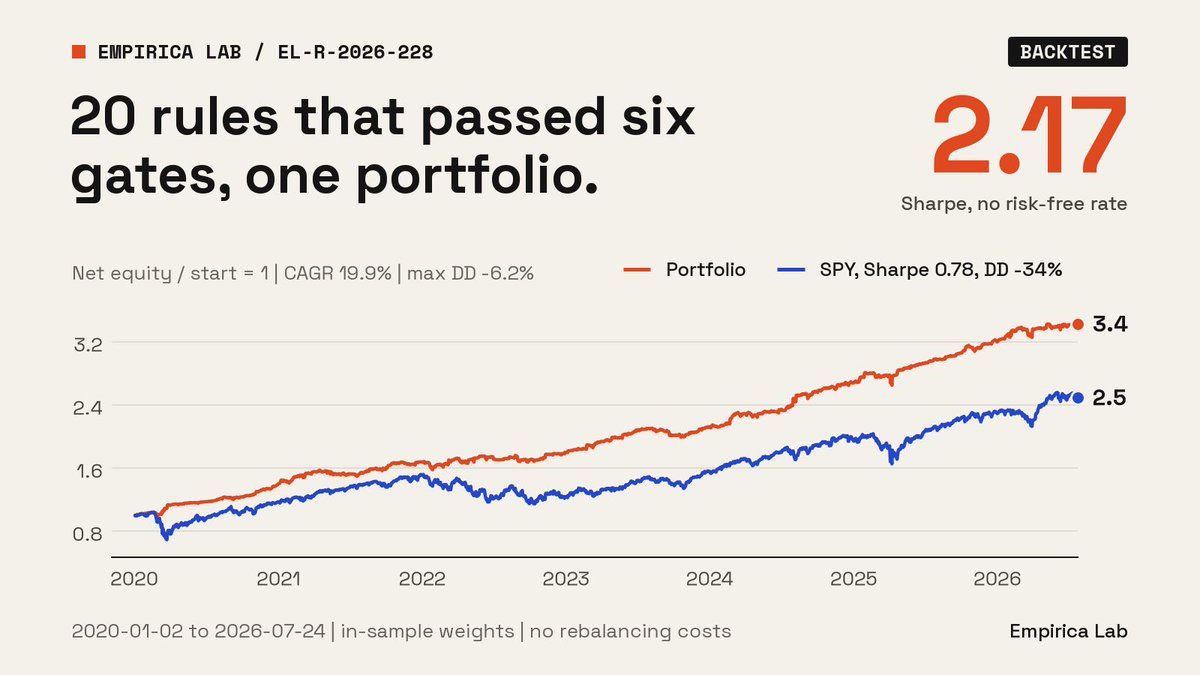
217 rule-market pairs from trading newsletters went through our 10 robustness gates. 20 passed six or more.
Those 20 as one portfolio: Sharpe 2.17, 19.9% a year, max drawdown 6.2%, 14 of 14 half-years up. Jan 2020-Jul 2026.
Backtest. Weights and catches below.
More catches:
- The 20 were picked after seeing their results.
- NVDA, GOOG and MPWR are today's winners. Nobody knew that in 2020.
- Worst day -3.3%, over our own 3% limit.
- Daily rebalancing, no rebalancing costs.
- Alone, only one of the 20 clears Sharpe 1.5.
25x on BTC while sitting out half the days.
Rule: buy a confirmed pivot-high break above the 50-day average, trail the stop after profit. 41% CAGR, May 2017-Aug 2026.
Backtest: holding BTC made 37x, and the rule still drew down 63%.
Code in our Discord, link below.
A calendar beat holding Bitcoin by 32x.
Rule: after each halving, long 546 days, short 273, long 273. No indicators. $1 became $1,190 vs $37 for buy & hold, May 2017-Aug 2026.
Backtest: 3 cycles, a 63% drawdown, no short funding.
Rerun code in our Discord, link below.
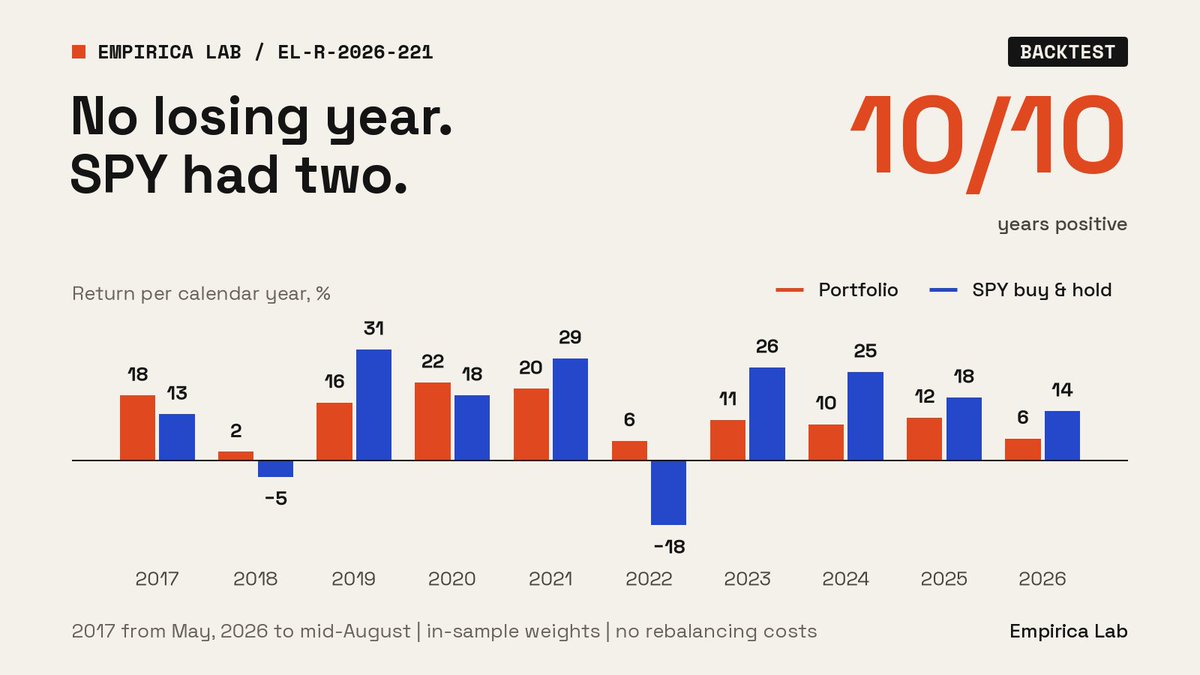
Calendar years: 10 of 10 positive. SPY lost in 2018 and 2022.
The price: it trailed SPY in six of those ten years. 13.3% CAGR vs 15.3% for SPY.
Weights are fit in-sample, no rebalancing costs.
Weights and code for every strategy: https://t.co/Gf3CcL2160
We put our 25-strategy portfolio through the four worst S&P 500 drops since 2017.
COVID crash: SPY -33.7%, portfolio -0.2%.
2022 bear market: SPY -24.5%, portfolio +3.9%.
Worst of the four: -4.4%.
Backtest, in-sample weights. Charts below.
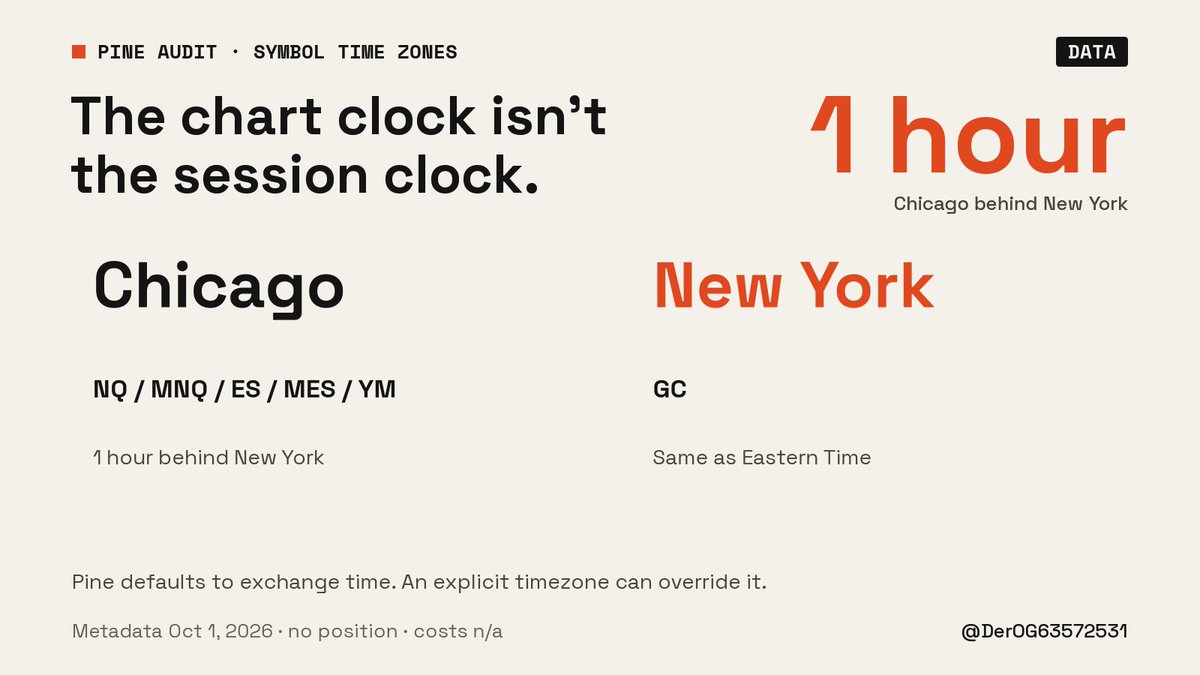
A chart set to New York can still run on Chicago time.
My Oct 1 Pine audit found NQ/MNQ/ES/MES/YM use Chicago exchange time; GC uses New York. Pine defaults to exchange time unless overridden. Changing the chart clock doesn't change the script.
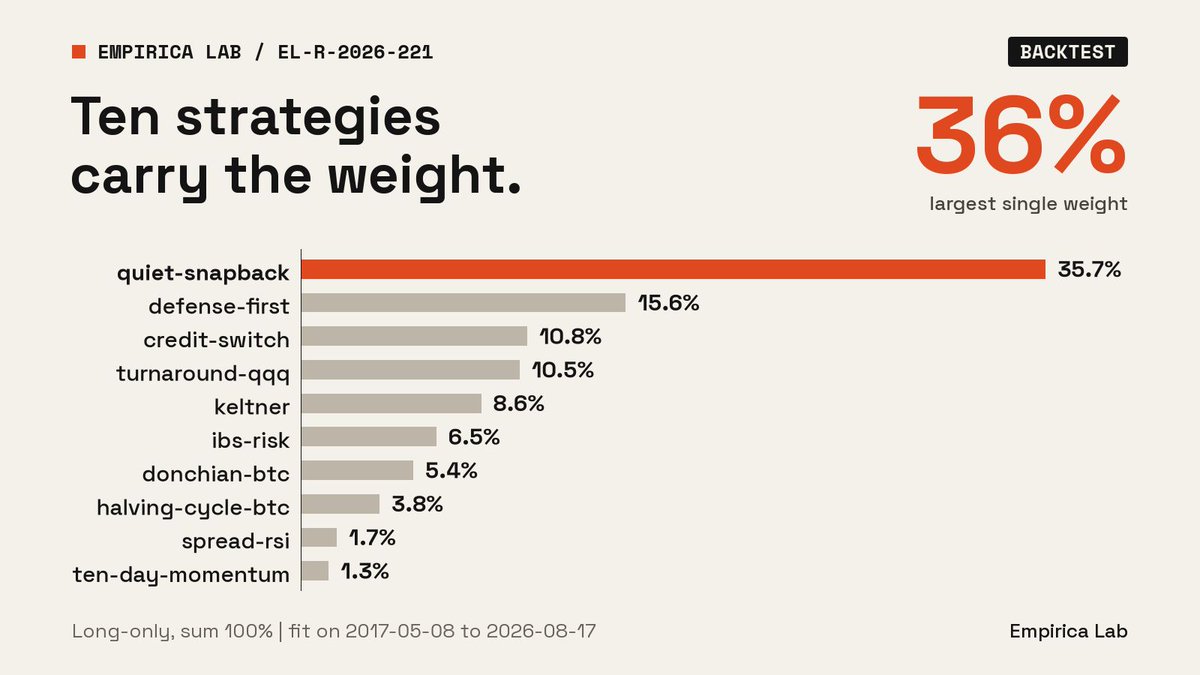
Weights: quiet-snapback 35.7%, defense-first 15.6%, credit-switch 10.8%, turnaround-qqq 10.5%, keltner 8.6%, ibs-risk 6.5%, four others 12.2%.
No risk-free rate, no rebalancing costs. Over T-bills the Sharpe is 2.13.
Code for every strategy: https://t.co/Gf3CcL1tgs
We put the 25 strategies we reran into one portfolio.
Max-Sharpe weights picked 10: Sharpe 2.63, 13.3% CAGR, max DD 4.7%, May 2017-Aug 2026. SPY: 0.86, DD 33.7%.
Catch: weights are fit in-sample. Fit only through Aug 2023, the next 3 years ran 2.25.
Weights below.