All Gas - No Brakes!
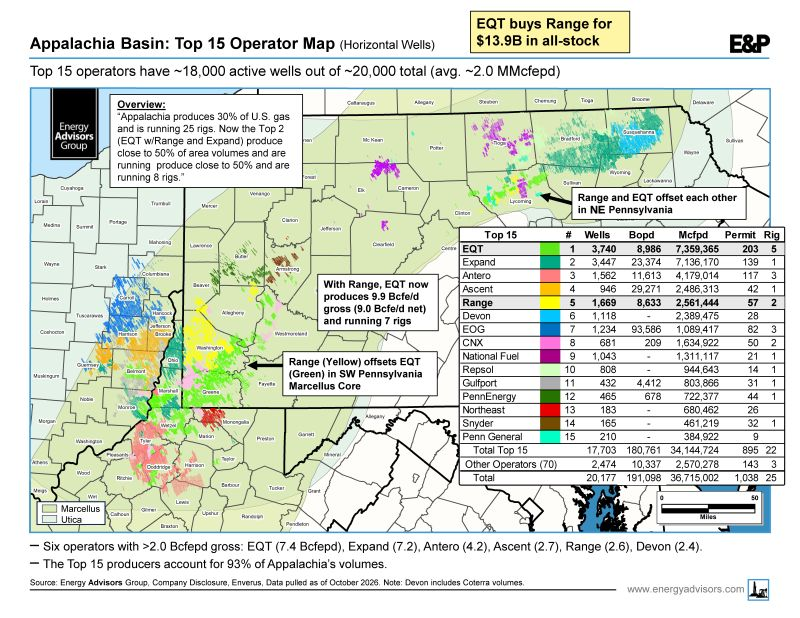
EQT Corporation pays $13.9B for its Appalachia neighbor, Range Resources, at a 20% premium.
In another industry consolidation, EQT agreed to acquire Marcellus pioneer Range Resources for $13.9B ($13.0B in stock plus $0.9B in assumed debt). The deal is the largest upstream pure Appalachia deal on record, surpassing EQT’s prior record $8.2B buy of Rice Energy in June 2017.
Per EQT, Range's assets are some of the highest quality natural gas inventory in North America. EQT projects unlevered FCF breakeven at <$2.00.
Range Resources is largely credited with pioneering the Marcellus in 2004. Range’s geologist Bill Zagorski had a “eureka moment” after seeing Barnett shale success. Challenging conventional wisdom, Range applied a Barnett-style fracture treatment to the existing Renz #1 well in Pennsylvania. It worked. And now here we are.
The market's initial reaction is broadly favorable: Range’s stock closed up 18%, while EQT slipped just 1% on the announcement.
The acquisition metrics bode well for other Appalachia producers. We're watching Devon Energy's (#6 producer) plans for its Marcellus assets post Coterra Energy and National Fuel Gas Company's spinoff of Seneca Resources Company, LLC (#9 producer).
𝐑𝐚𝐧𝐠𝐞 𝐁𝐲 𝐭𝐡𝐞 𝐍𝐮𝐦𝐛𝐞𝐫𝐬:
• ~$13.9B (including $0.9B in assumed debt)
• 20% premium, with 0.987 EQT shares for each RRC share
• 2.3 Bcfe/d net (67% gas, 33% liquids)
• 769,000 net acres
• RRC shareholders to own 27% of combined company
• Closing targeted for 1Q27
𝐁𝐞𝐲𝐨𝐧𝐝 𝐭𝐡𝐞 𝐍𝐮𝐦𝐛𝐞𝐫𝐬:
• Range was comfortable remaining independent but viewed EQT as a strong, strategic fit
• $423MM termination fee
• Per Toby Z. Rice, EQT CEO, “The asset base that Range has exceeded our expectation.”
• Why now? Growing power and data center demand in EQT’s “backyard”
• The all-stock deal strengthens EQT’s debt profile and supports its investment-grade ambition with projected YE2027 leverage of ~0.6x net debt/adjusted EBITDA
• Range’s assets have a strong operating and strategic fit with EQT’s
• ~$325MM in annual base synergies within two years, with a path to $600MM per year longer term
• Pro forma ~9.0 Bcfe/d (up 33% for EQT)
• 2.8MM net acres (up 37%)
• 30+ years of high quality drilling inventory
• >10 Bcf/d marketing capacity
Conventional Kansas...take a look!
EAG has been retained by the Dane G Hansen Foundation to market its Kansas operated, nonoperated and royalty package.
377-Wells; 106-Op; 65-NonOp; 206-Royalty
ARBUCKLE, MISSISSIPPIAN, LANSING-KANSAS CITY
Shallow Depths: 3,000-4,000 Ft.
Well-Maintained Operating Assets
100% Operated WI. High NRI Leases
Gross Prod.: ~550 BOPD & 27 MCFD; Net: ~169 BOPD & 8 MCFD
Net Cash Flow: ~$248,000/Month (L6M)
Seller Eng: PDP PV10: ~$21,926,431
𝐎𝐅��𝐄𝐑𝐒 𝐃𝐔𝐄 𝐍𝐎��𝐄𝐌𝐁𝐄𝐑 𝟏𝟖𝐭𝐡
https://t.co/ohx039Pkbo
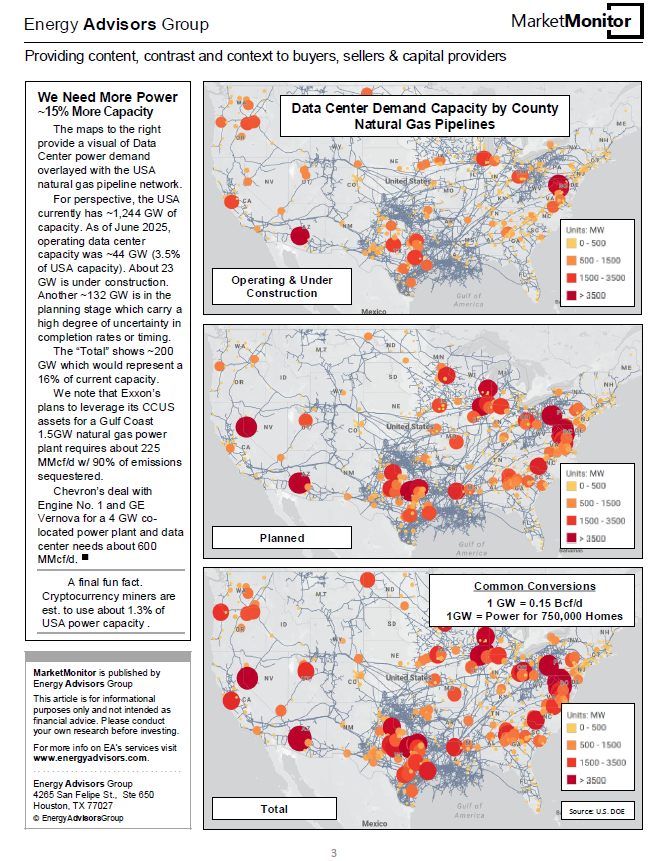
PJM, ERCOT and SPP recorded new peak electricity loads in July as growing demand from data centers and industrial projects adds pressure on U.S. power systems. https://t.co/HC8x7JGeOn
Our latest Industry Insight, 𝐓𝐡𝐞 𝐕𝐚𝐧𝐢𝐬𝐡𝐢𝐧𝐠 𝐈𝐧𝐝𝐞𝐩𝐞𝐧𝐝𝐞𝐧𝐭?, argues that consolidation will likely continue at a strong pace. The immediate driver is scale. The deeper issue is inventory.
𝐓𝐡𝐢𝐬 𝐢𝐬 𝐭𝐡𝐞 "𝐫𝐞𝐭𝐮𝐫𝐧𝐬" 𝐞𝐫𝐚 –
According to analysts, U.S. shales relentless pursuit of growth for growth's sake lost ~$300 billion in free cash flow and $450 billion in write downs. These losses, the pandemic and 2020 oil-price collapse cemented shareholder's pressure for discipline and returns. High return drilling inventory became increasingly valuable. The E&Ps, now, best positioned for this cycle are those controlling enough quality inventory to keep drilling for years.
𝐓𝐡𝐞 𝐫𝐨𝐥𝐥𝐮𝐩 𝐨𝐟 𝐩𝐮𝐛𝐥𝐢𝐜𝐬 𝐚𝐧𝐝 𝐩𝐫𝐢𝐯𝐚𝐭𝐞𝐬 –
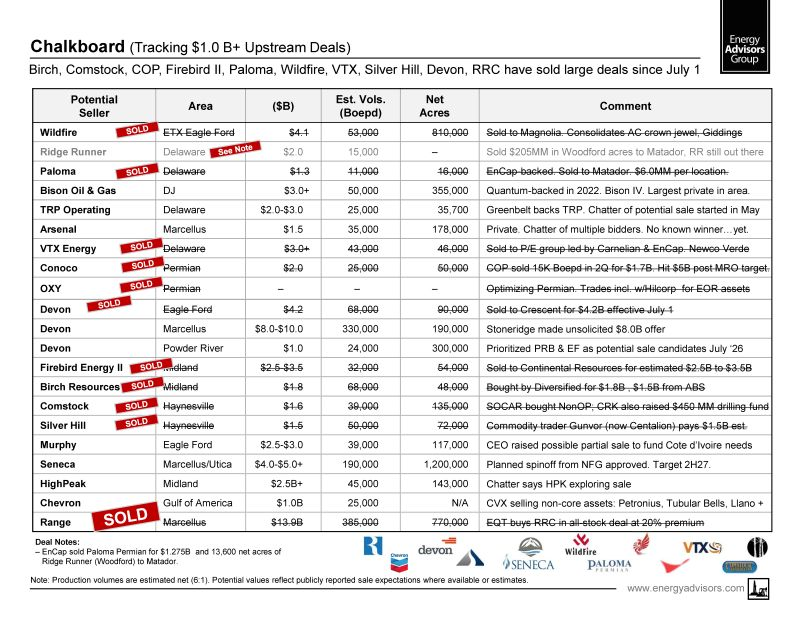
By our count (see table), 15 U.S. focused public E&Ps are gone ($225B) since 2023 or ~30% of those valued over $500MM. Like the 1980's, the largest current consolidators are firms like ExxonMobil (Pioneer, $64.5B), Chevron, (Hess, $60.0B) Devon Energy, (Coterra, $25.4B), ConocoPhillips (Marathon, $22.5B) , Expand Energy (Chesapeake/Southwestern, $11.5B) and more.
In addition to those 15 public rollups, ($226B), another 26 privates (>$500MM) were also acquired since 2023. The largest private buyouts are Diamondback Energy/Endeavor ($26.0B), Oxy/CrownRock ($12.0B), Mitsubishi Corporation/Aethon ($7.5B), EOG Resources/Encino ($5.6B), and Devon/Grayson Mill ($5.0B) to name a few.
𝐓𝐫𝐢𝐜𝐤𝐥𝐞 𝐝𝐨𝐰𝐧 𝐨𝐩𝐩𝐨𝐫𝐭𝐮𝐧𝐢𝐭𝐢𝐞𝐬 –
Mergers may be swallowing many trophy companies, but not all their assets fit neatly inside the parent's portfolio. Noncore packages, minerals, PDP and gas-weighted assets can return to the market as companies sharpen their focus. That circulating inventory creates opportunities for the right buyers.
Kimmeridge's new white paper, Shale's Golden Years Part II, touches on part of the same theme. Oil reserves are becoming harder to replace despite better drilling and lower costs while the industry is more than replacing gas reserves. That oil/gas differential will influence future consolidation and which inventory buyers pursue and what they are willing to pay.
Here's the full report: https://t.co/aEKDYkodSM
We've been on it...$BP and $DVN Eagle Ford Assets...
See here: https://t.co/fWBjGNTozu
If you want to know what's potentially coming up for sale and/or what is for sale...EAG.
#oil#gas#a&d #upstream